


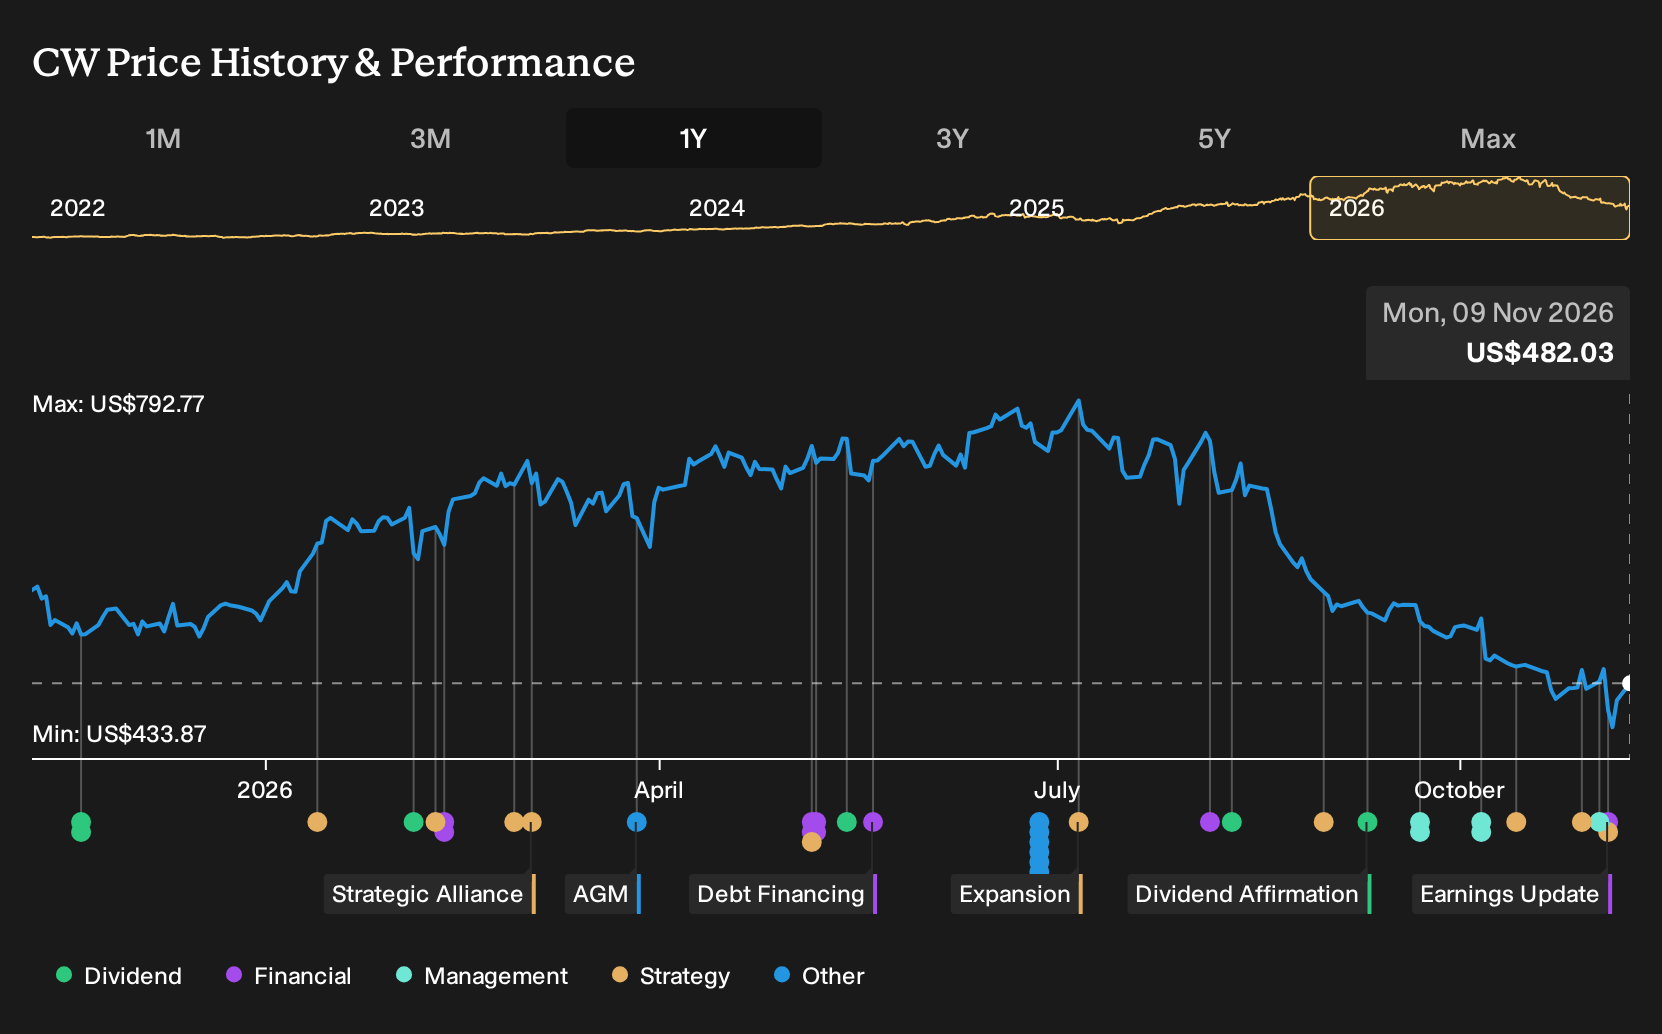
- Curtiss-Wright reported third quarter 2026 revenue of US$952.59 million and net income of US$138.89 million, alongside over US$225 million in new U.S. Navy propulsion and systems contracts.
- The combination of higher earnings per share from continuing operations and multi year naval awards extends Curtiss-Wright's visibility across defense and commercial nuclear focused segments.
- Next, the focus turns to how Curtiss-Wright's earnings strength and new Navy contracts might influence the longer term investment narrative.
Scan how Curtiss-Wright’s defense and nuclear exposure compares with peers by reviewing a curated set of 17 nuclear energy infrastructure stocks that share similar long-cycle infrastructure themes.
Curtiss-Wright Investment Narrative Recap
For Curtiss-Wright, the big picture that a shareholder needs to buy into is a long-cycle story in defense electronics, naval programs and commercial nuclear work. The analyst consensus Narrative on Simply Wall St points to backlog and order visibility as central to that view. The latest quarter, with US$952.59 million in revenue and US$138.89 million in net income, keeps that operational story intact.
The short term catalyst is execution on that growing workload without margin slippage or delivery issues. The biggest risk remains heavy reliance on large defense and nuclear contracts, where any budget shifts or timing delays could affect how quickly the reported US$4.3b backlog converts into revenue and earnings.
The most relevant recent update for that thesis is the US$225 million set of U.S. Navy contracts for Virginia class, Columbia class and Ford class programs. These awards tie directly into Curtiss-Wright’s Naval & Power segment, which already accounts for a large portion of group sales, and they extend work through 2030.
From a catalyst angle, those Navy awards support the idea of durable demand on key platforms, while still leaving execution and program timing as key watchpoints. Any disruption to these projects, or to related government funding plans, would feed straight into the main risks analysts already flag around contract concentration, backlog conversion and investor concern about sustaining current P/E levels.
Curtiss-Wright’s narrative projects US$4.6b revenue and US$739.5 million earnings by 2029, based on analysts’ assumed 8.1% yearly top line growth and an earnings increase of about US$198 million from US$541.2 million today.
Uncover why Curtiss-Wright's fair value indicates a 41% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on valuation risk. Some of the lowest Curtis-Wright analysts argued the stock already priced in rich expectations, even before this quarter’s US$952.59 million revenue and US$138.89 million net income. That group was working off a US$4.6b 2029 revenue path and about US$745.4 million in earnings, yet still guided to a much more cautious price target. Their stance shows how sharply opinions can diverge. Use that spread as a prompt to explore several different scenarios rather than anchoring on any single story.
Explore 4 other Curtiss-Wright fair value estimates, including one that suggests it could be worth just $488.16.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own analysis.
- A great starting point for your Curtiss-Wright research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Curtiss-Wright. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Curtiss-Wright's overall financial health at a glance.
Looking For More Investment Ideas Beyond Curtiss-Wright?
If Curtiss-Wright has sharpened your view on defense and infrastructure exposure, broaden your watchlist by scanning other opportunities through the Simply Wall St Screener. These filters can help you focus on the kind of businesses that best fit your risk tolerance and return goals.
- If capital preservation is your priority, start with stocks that have tended to show more resilient profiles by reviewing 30 resilient stocks with low risk scores.
- For investors who want stronger balance sheets and steadier fundamentals, filter the market using a list of solid balance sheet and fundamentals (25 results) that can handle tougher conditions.
- Those seeking mispriced opportunities can cast a wider net across quality companies trading at appealing valuations by assessing 33 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com