


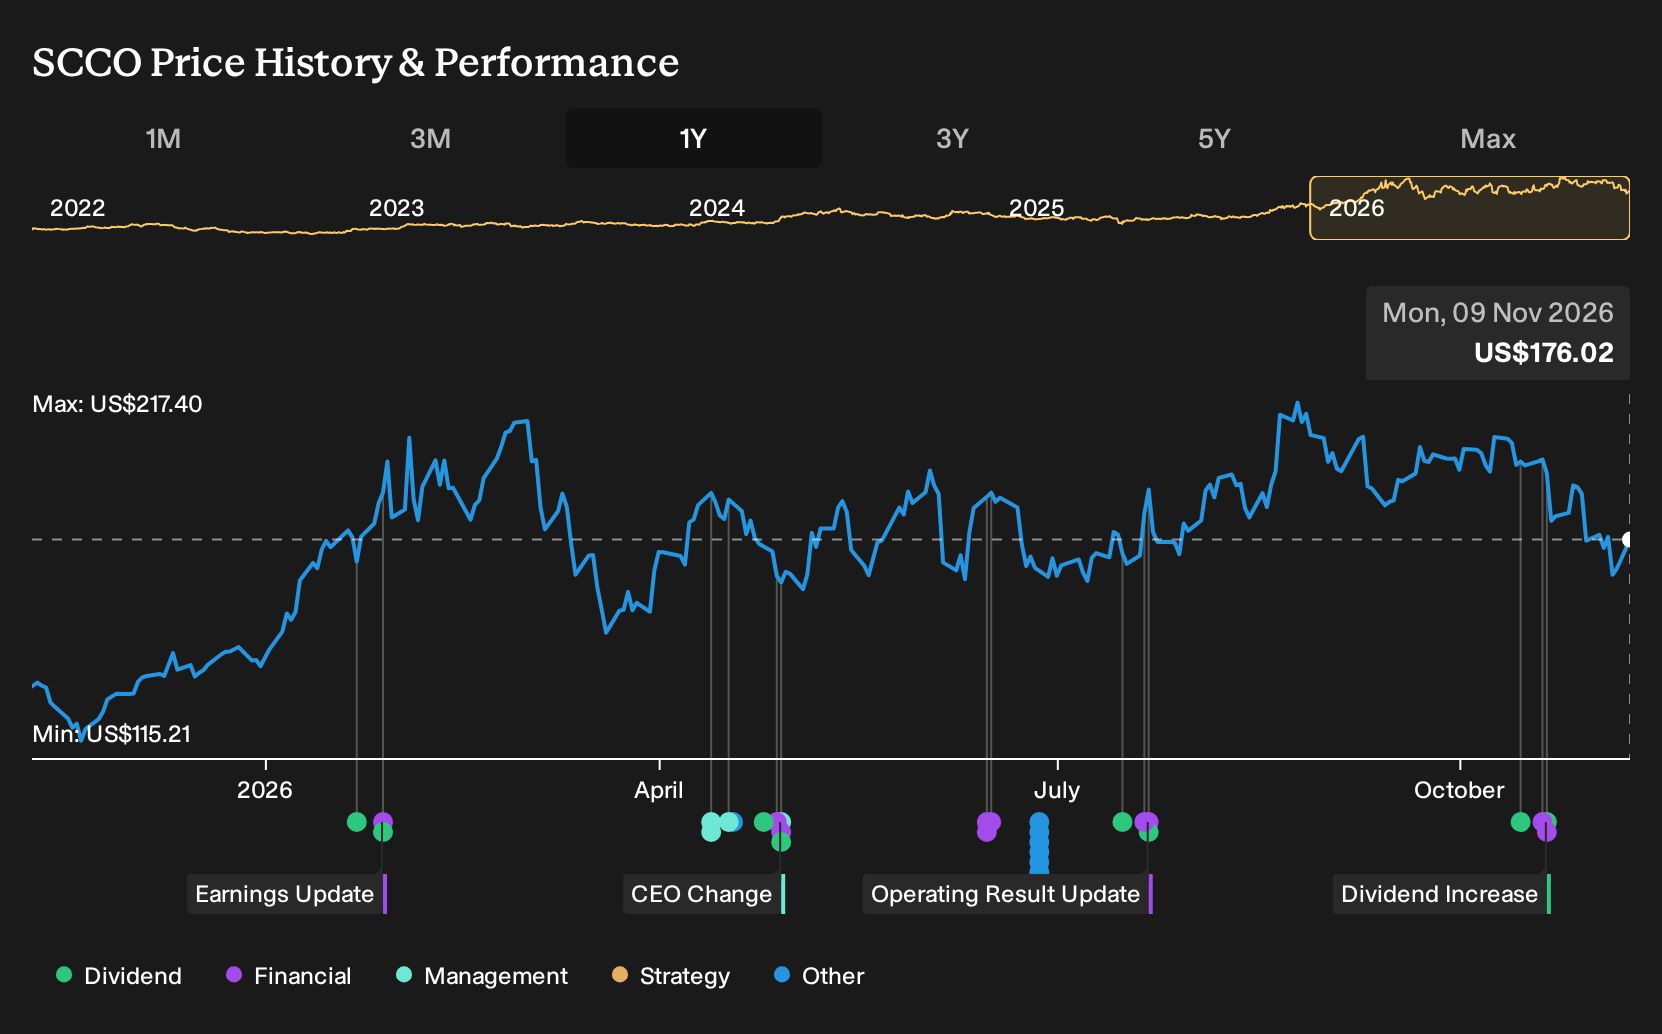
- Southern Copper reported record third quarter net sales and net income, supported by strong copper prices, low operating cash costs and progress on major projects such as Tia Maria in Peru and El Pilar in Mexico.
- The combination of very low reported operating cash costs, helped by by-product credits, and a growing pipeline of long-dated copper projects underpins a business model that leans heavily on future volume from Peru and Mexico.
- We will now see how Southern Copper's investment narrative could be influenced by record quarterly earnings and progress on its expansion projects.
Scan beyond Southern Copper and evaluate other potential winners in the copper story with a curated set of 16 top copper producer stocks aligned to this same supply and pricing theme.
Southern Copper Investment Narrative Recap
To own Southern Copper, you need to believe the current operating strength and very low reported cash costs can be carried into a much larger asset base in Peru and Mexico. Record net sales and income support that narrative in the near term. The key short-term catalyst is continued delivery of low-cost production without major operational hiccups. The latest quarter supports this but does not radically change the picture.
The analyst consensus narrative on Simply Wall St highlights a multi-year capex program of more than US$20.5b as both an opportunity and a stress point. The biggest risk right now is execution, including permitting, community issues and construction overruns at projects like Tia Maria, Los Chancas and Michiquillay, especially with much of the expected future volume still under development.
The recent recognition of Southern Copper among the 10 Best Copper Stocks to Buy according to Wall Street analysts intersects directly with these execution milestones. It draws extra attention to whether record EBITDA and net margins can remain supported by very low operating cash costs after by-product credits, particularly as new projects ramp and grades or unit costs shift.
For catalysts, Tia Maria in Peru and El Pilar in Mexico are central. Tia Maria is reported at 42% completion by mid 2026 with US$693m already invested from a planned US$1.8b, and both assets are referenced with start dates around 2028 and 2029. Your call is whether management can bring these online broadly on schedule and on budget, while managing country risk and keeping funding and dividend decisions balanced.
Southern Copper's narrative projects US$18.4b revenue and US$6.8b earnings by 2029. This rests on analysts assuming 5.3% yearly revenue growth and about a US$1.1b earnings increase from US$5.7b today.
Uncover why Southern Copper's fair value aligns with its current price.
Exploring Other Perspectives
One bullish twist in the Southern Copper story is how some analysts treat the stalled projects. You see Los Chancas as blocked today. The most optimistic models were already pencilling in about US$20.2b of revenue and US$7.6b of earnings by 2029. Record results and the ranking news could easily push those views to shift again.
Explore 4 other Southern Copper fair value estimates, including one that suggests there could be as much as 34% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Southern Copper research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Southern Copper. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Southern Copper's overall financial health at a glance.
Looking For More Investment Ideas Beyond Southern Copper?
If you want to put Southern Copper in context, it helps to line it up against other opportunities that share similar quality, income or risk traits. The Simply Wall St Screener lets you scan the market using the same kind of fundamentals you have just seen here, so you can build a watchlist that fits your own style instead of relying on a single ticker.
- If capital protection comes first for you, check out a curated set of 30 resilient stocks with low risk scores that aim to keep drawdowns in check while still offering room for upside.
- If quality at a sensible entry point is the priority, look through a hand picked group of 33 high quality undervalued stocks that combine stronger fundamentals with prices that screens suggest may not fully reflect them.
- If you are hunting for future leaders before the crowd focuses on them, scan through a focused pool of 19 high quality undiscovered gems that pair solid financials with relatively low current visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com