


Recent commentary around Johnson Controls International (JCI) focuses on strong data center orders and a record backlog near US$21b, with investors watching how this higher value mix affects future earnings power.
Set against that data center story, Johnson Controls International has had a choppy few weeks, with the share price falling about 10.1% over the past month and 8.6% over the last 90 days. This comes even though the year-to-date share price return is 15.7% and the 3-year total shareholder return is around 19x, suggesting longer-term holders have already seen strong value creation. Short-term momentum has cooled as investors reassess earnings quality, leadership changes in India and at the group level, and the latest full-year results.
Scan other building and data center plays showing similar backlog and earnings setups by running the hand picked 42 power grid technology and infrastructure stocks alongside Johnson Controls International in your research.
The recent pullback leaves Johnson Controls International caught between a story of strong data center demand and backlog strength, and a market that seems more cautious. Which side does the current valuation reflect?
Most Popular Narrative: 17% Undervalued
On the Simply Wall St analyst consensus Narrative, Johnson Controls International is priced below its implied fair value, with a fair value of $169.70 versus a last close of $141.49. The Narrative applies a 9.23% discount rate to analysts forecasts and earnings assumptions to reach that figure, then tests whether the current share price lines up with those cash flow and margin expectations.
The main factor that has to go right is continued execution on service attach and productivity, so that stronger equipment demand in areas like North America and data centers ultimately translates into the more profitable, higher margin mix the business system is designed to support.
The focus on expanding service capabilities and improving service attachment rates, especially on the growing installed base in AI and other mission critical data centers where uptime is critical, is likely to shift mix toward higher margin recurring revenue and support net margin expansion.
See why 30 investors see Johnson Controls International as 17% undervalued.
Result: Fair Value of $169.70 (UNDERVALUED)
Still, the bullish Johnson Controls International story can unravel if complexity in its product set slows margin progress or if weaker security demand continues to drag on overall earnings.
Find out about the key risks to this Johnson Controls International narrative.
Another View: What P/E Says About Johnson Controls International
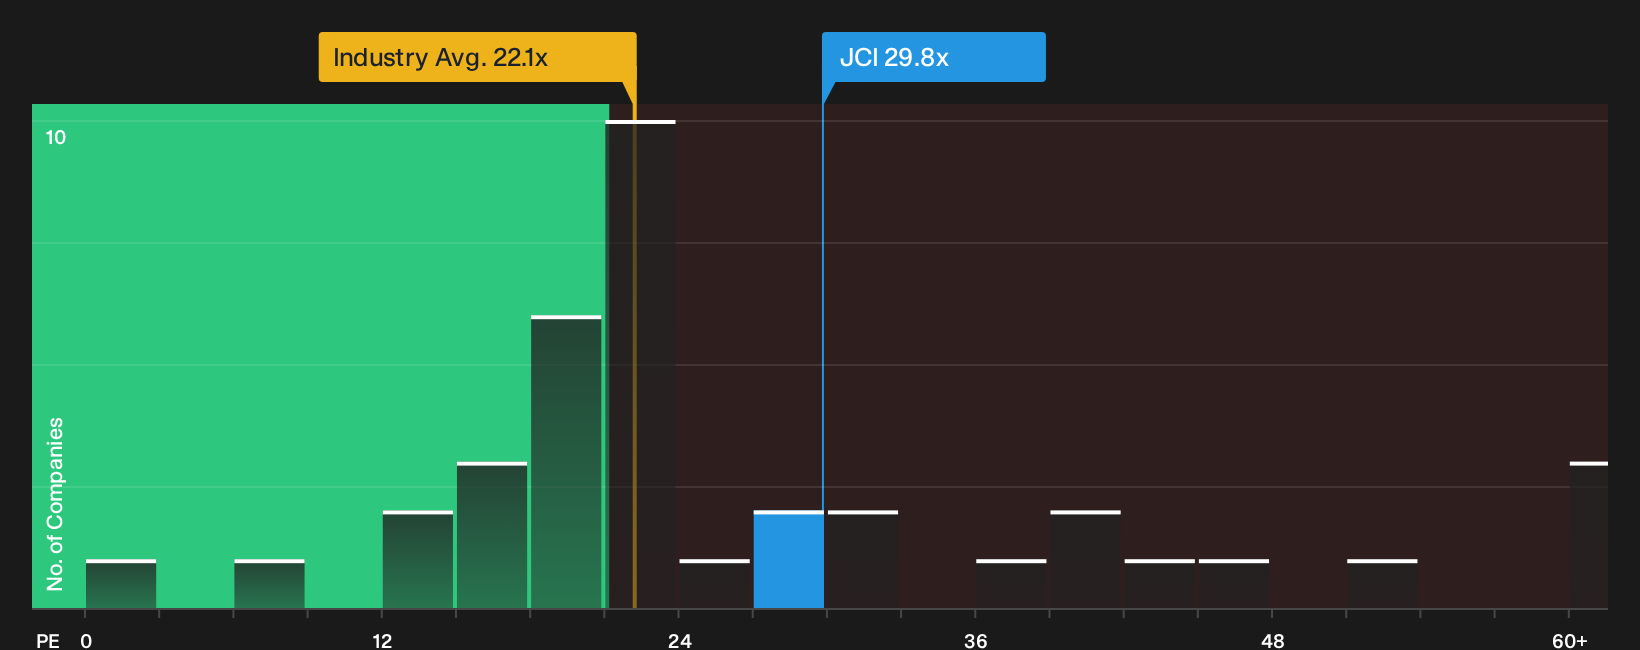
On cash flows, Johnson Controls International screens as undervalued, yet the picture shifts when looking at earnings multiples. The stock trades on a P/E of 29.8x against a US Building industry average of 22.1x and a peer average of 22.7x, while the fair ratio is 32.4x. That mix of premium vs peers and headroom vs fair ratio leaves a simple question for investors: Is this pricing closer to stretched optimism, or to a market that still has room to move toward that fair ratio target?
To pressure test that P/E story against the underlying numbers in a more structured way, take a look at See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals so far, right? If you want to move past the headline debate around Johnson Controls International and act while sentiment is still split, it is worth weighing the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Johnson Controls International?
Do not stop with Johnson Controls International. Broaden your watchlist now by checking out focused stock lists that target different return drivers and risk profiles.
- Identify potential mispricing by scanning a curated pool of companies that screen as attractively valued with quality fundamentals through the 33 high quality undervalued stocks.
- Prioritise resilience and support peace of mind by reviewing a 30 resilient stocks with low risk scores that highlights businesses with sturdier risk scores.
- Seek tomorrow's potential standouts early by using a 19 high quality undiscovered gems that surfaces overlooked companies with strong underlying numbers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com