


China’s trade surplus recently moved past $1 trillion on the back of strong exports linked to AI and high tech gear, and that kind of global demand can reshuffle where cash flows end up. Some Canadian companies quietly generate solid cash yet still trade at a discount to their estimated fair value. This article looks at three such Canadian stocks that our cash flow focused screener currently flags as potentially undervalued.
The three Canadian stocks covered below are just a sample. The same cash flow screen currently surfaces 2 more companies with similarly interesting stories that are not included in this article.
If you want to identify and analyze value ideas built around discounted cash flow estimates, head straight into the Undervalued Stocks Based On Cash Flows screener.
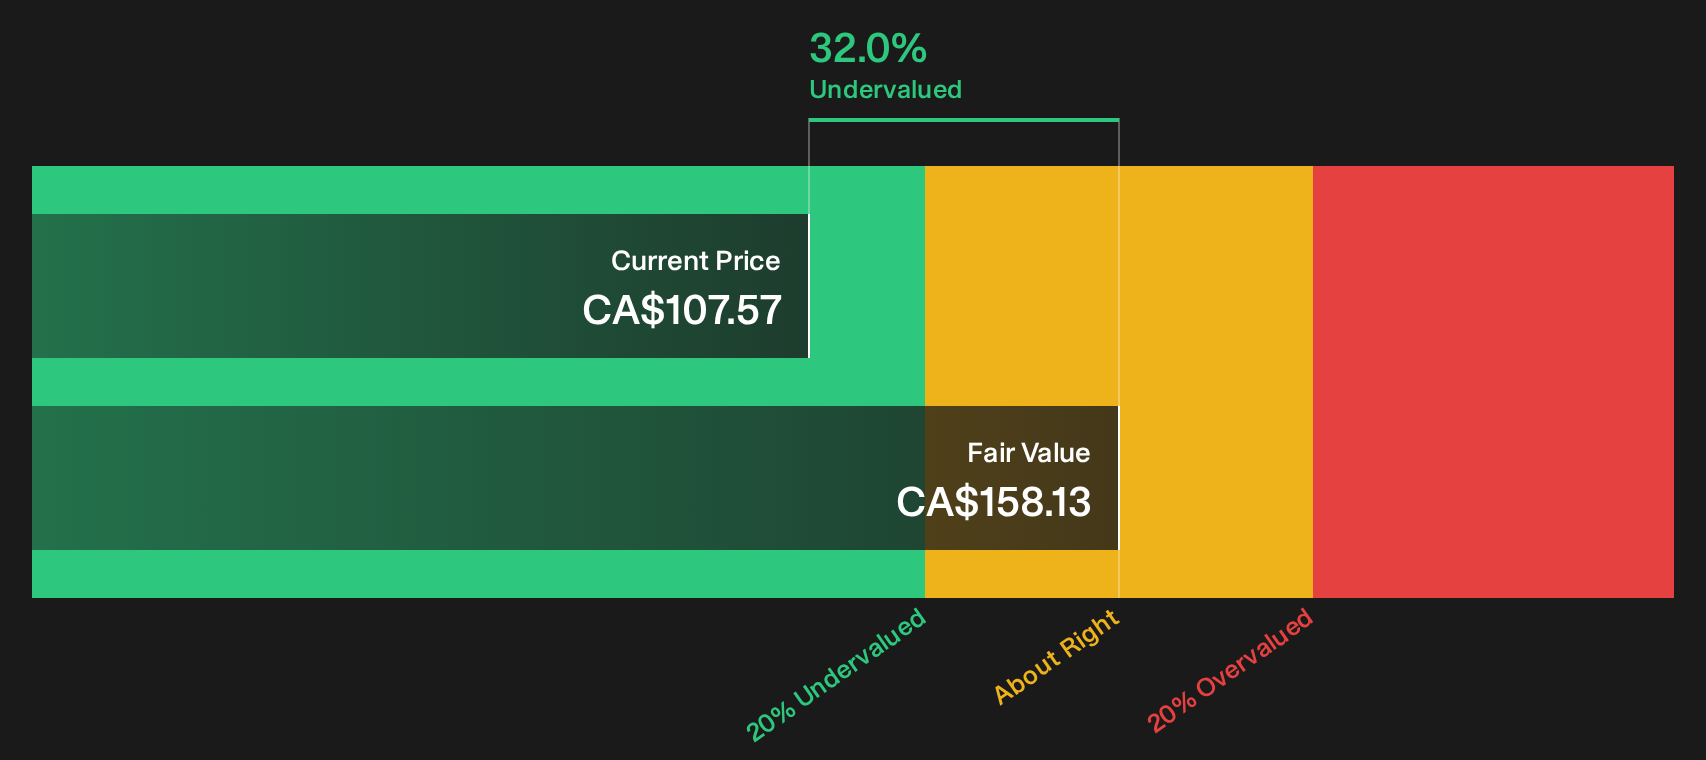
Stantec (TSX:STN)
Stantec is a global consulting and design firm focused on infrastructure, water and buildings projects. Its long contract cycles and fee based work align closely with the screener’s focus on cash flow potential, as highlighted in the analyst consensus Narrative on Simply Wall St.
Stantec earns about CA$3.6b from the United States, CA$1.6b from Canada and CA$1.7b from global operations, and has a market value of roughly CA$11.8b.
"Recent large acquisitions such as Page, Cosgroves and Ryan Hanley have significantly expanded Stantec's presence in the U.S., New Zealand and Ireland. With Page now performing strongly and Niche in Australia added in mid 2026, the larger platform can keep widening the revenue base and support future earnings growth as integration benefits continue to flow through to results."
The real swing factor is how one pressure on future profitability shapes the cash that ultimately flows from that expanding project backlog.
That pressure point is exactly what the Simply Wall St narrative unpacks in the full narrative for Stantec, showing where Stantec’s cash engine could accelerate or stall next.
Green Thumb Industries (CNSX:GTII)
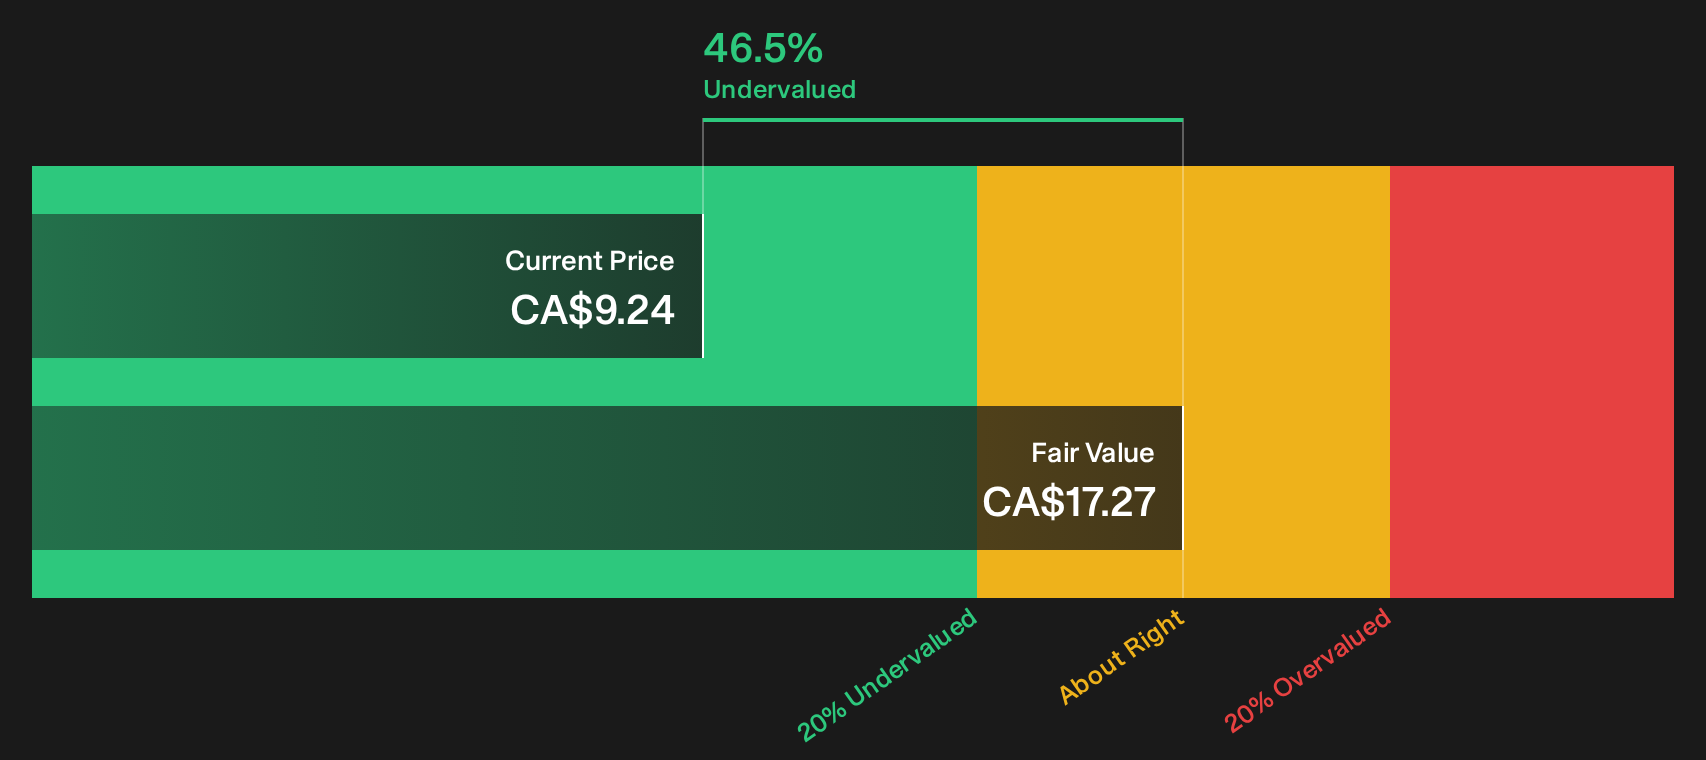
Green Thumb Industries is a Chicago based cannabis producer and retailer whose branded products and dispensary network sit firmly within the screener’s focus on recurring cash flows. The bullish analyst Narrative on Simply Wall St argues that this engine is not fully reflected in today’s valuation.
"Maintaining a net cash position with hundreds of millions of dollars in cash and an active share repurchase program that has already retired roughly 12 to 13% of shares creates capacity for further reductions in the share count. This can translate operating cash flow and EBITDA into faster growth in per share earnings metrics."
The real tension for Green Thumb Industries is how one unresolved shift in pricing and regulation shapes whether those cash flows actually deepen margins.
Whether that shift squeezes or accelerates Green Thumb Industries’ margins, the full narrative for Green Thumb Industries lays out how pricing, regulation and cash returns might be decoupling from headline sentiment.
IAMGOLD (TSX:IMG)
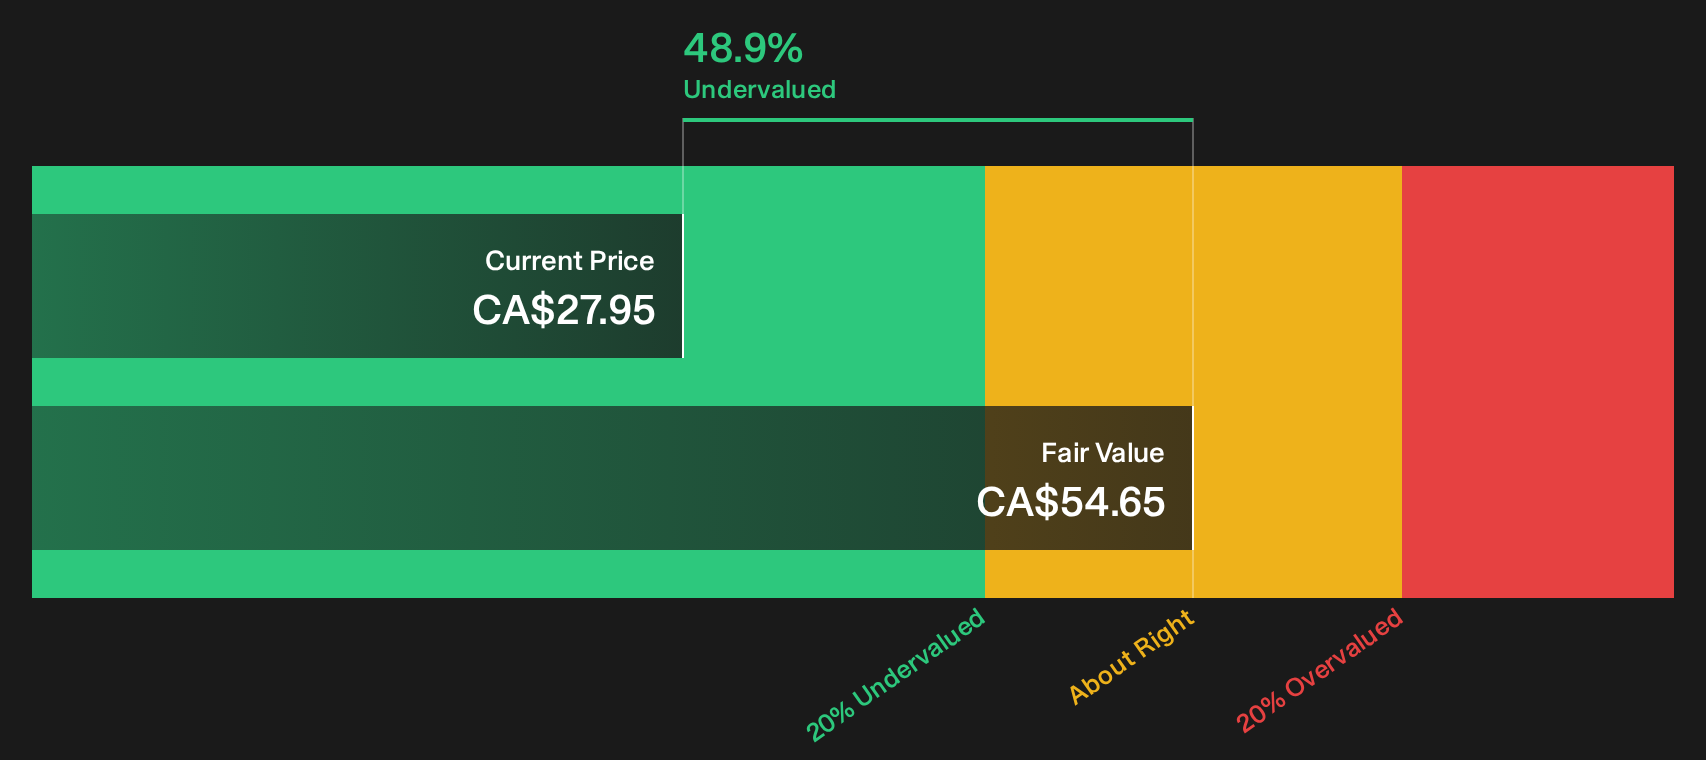
IAMGOLD is a Toronto based gold producer. Its Côté Gold development in Ontario anchors its future cash flow potential, while current income is primarily sourced from the Essakane operation at about $2.1b, Côté Gold at roughly $1.2b and Westwood at about $589 million, with a market value near $15.0b.
IAMGOLD slots into this cash flow focused screen because Côté Gold is designed as a large, long life project that could reshape how much free cash the business generates. The bullish analyst Narrative on Simply Wall St argues that execution on that plan is not yet fully priced in.
"Further reductions in Côté’s unit processing and mining costs, after the move away from external contractor crushing brought processing costs down to about $17.72 per tonne in June 2026 with internal targets of roughly $15 per tonne processing and $4 per tonne mining by year end, could shift IAMGOLD’s margin profile as more of the gold price flows through to operating income and net margins."
The real question is how one cost and capital decision around this build out shapes the cash that eventually reaches shareholders.
That decision point is exactly where the full narrative for IAMGOLD picks up, mapping how cost trends, capital choices and execution risk could turn IAMGOLD’s cash profile from stalled to accelerating.
Seeking Fresh Alternatives Before They Fly
Fresh ideas can move fast. The moment a breakout theme gains momentum, the best entries often get caught and repriced before the crowd even reacts. Scan these under the radar lists while it matters and get in early.
- Spot sturdier balance sheets before the crowd by running your own filter through the list of solid balance sheet and fundamentals (5 results) and see which businesses still pair strength with disciplined fundamentals.
- Track uranium and power names tied to the nuclear build out theme using the 17 nuclear energy infrastructure stocks so potential infrastructure candidates do not slip past you.
- Hunt for income ideas that aim to keep yields flowing with the 3 dividend fortresses and compare which payers line up with your own cash flow goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com