


Stagwell (STGW) has investor attention after its latest quarterly update, which paired higher sales with lower net income and reiterated full year 2026 net revenue guidance in the 8% to 12% growth range.
Recent trading suggests investors are still reacting to Stagwell’s guidance and leadership moves, with the share price delivering a 30 day share price return of 32.95% and a year to date share price gain of 143.13%. The 3 year total shareholder return of 149.46% points to momentum that has been building over a longer stretch.
Scan other agency and marketing stocks showing similar momentum to Stagwell by moving through our hand picked list of 19 high quality undiscovered gems.
Stagwell now has a bigger footprint and a much higher share price. The harder question is whether that recent surge already reflects what this business is worth.
Most Popular Narrative: 7% Overvalued
Stagwell last closed at $11.50, compared with the analyst consensus Narrative fair value of $10.71. This frames the stock as slightly ahead of that model. The analyst consensus Narrative on Simply Wall St ties that view directly to how much of the AI and government work story is already in the price.
The main thing that has to go right is that Stagwell continues to offset weakness in legacy marketing services by scaling AI-based offerings, government contracts and tech-led media so that these lines drive a larger share of revenue and profit.
See why 6 investors see Stagwell as 7% overvalued.
Result: Fair Value of $10.71 (OVERVALUED)
Still, the Stagwell narrative leans heavily on AI driven segments to offset weakness in legacy Marketing Services, and any pullback from major tech clients could quickly test that thesis.
Find out about the key risks to this Stagwell narrative.
Another View On Stagwell's Valuation
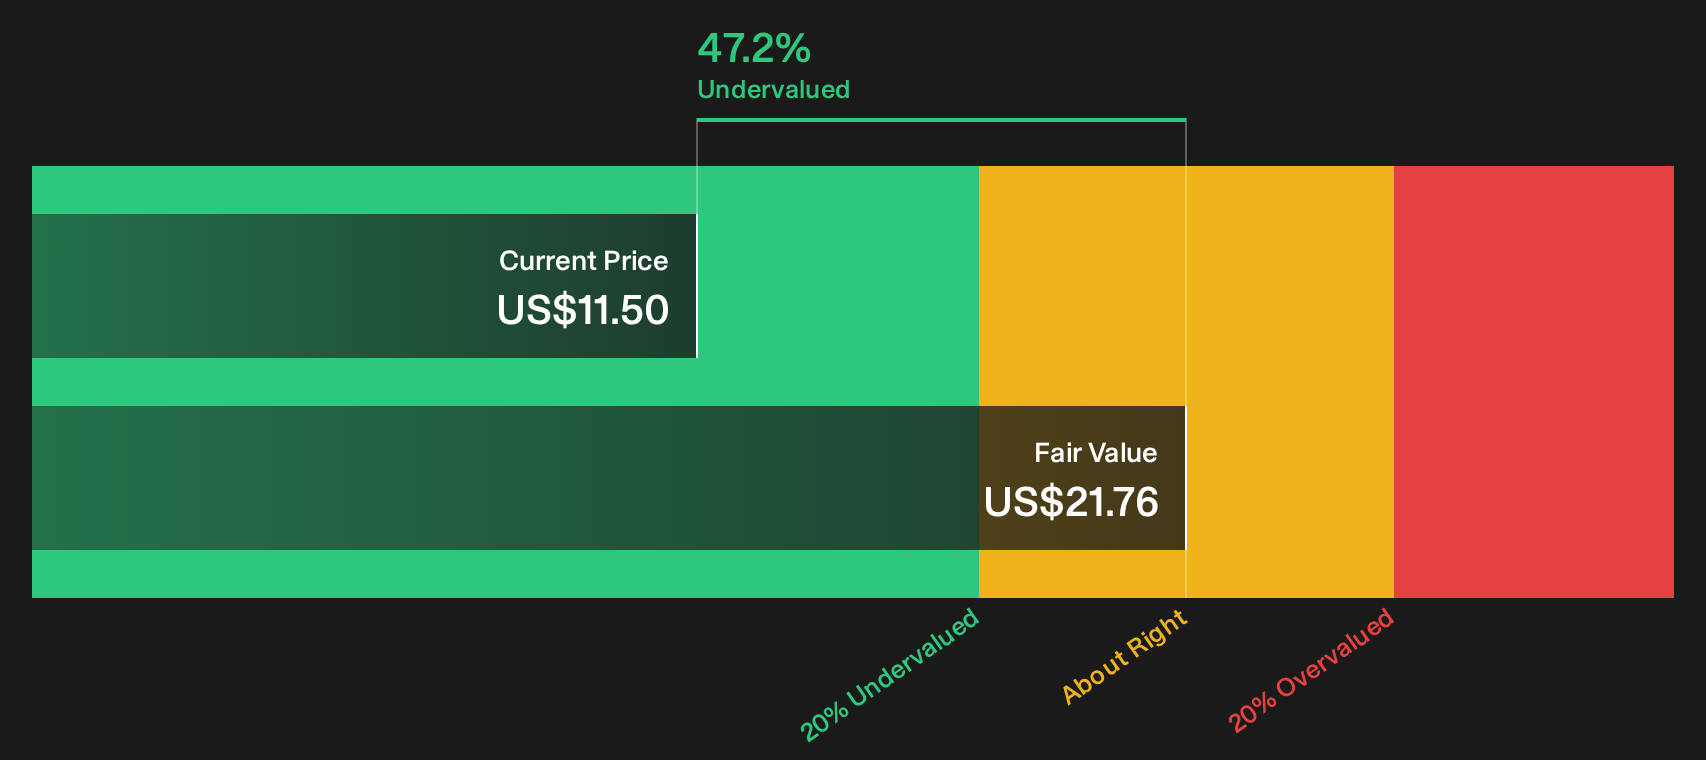
Analysts on Simply Wall St frame Stagwell as about 7% overvalued at $11.50 against a $10.71 fair value, yet the SWS DCF model points in the opposite direction. That cash flow view suggests the shares trade at a 47.2% discount to an estimated value of $21.76. Which lens do you trust more when the story hinges on long run cash generation rather than next quarter sentiment?
For a closer look at how that cash flow view is built, and where the main pressure points sit in the model, Look into how the SWS DCF model arrives at its fair value..
Next Steps
The debate on Stagwell’s value is already split, so move quickly, review the data points on both sides, and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Stagwell?
If you stop with Stagwell, you only see one angle. Broaden your watchlist with a few focused stock ideas that match how you like to invest.
- Target potential mispricings by scanning a curated pool of companies that pair quality with attractive entry points through our 33 high quality undervalued stocks.
- Build income into your portfolio by reviewing a focused group of stocks that offer strong yields in the 6 dividend fortresses.
- Reduce portfolio stress by concentrating on companies that carry resilient finances and fundamentals using the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com