


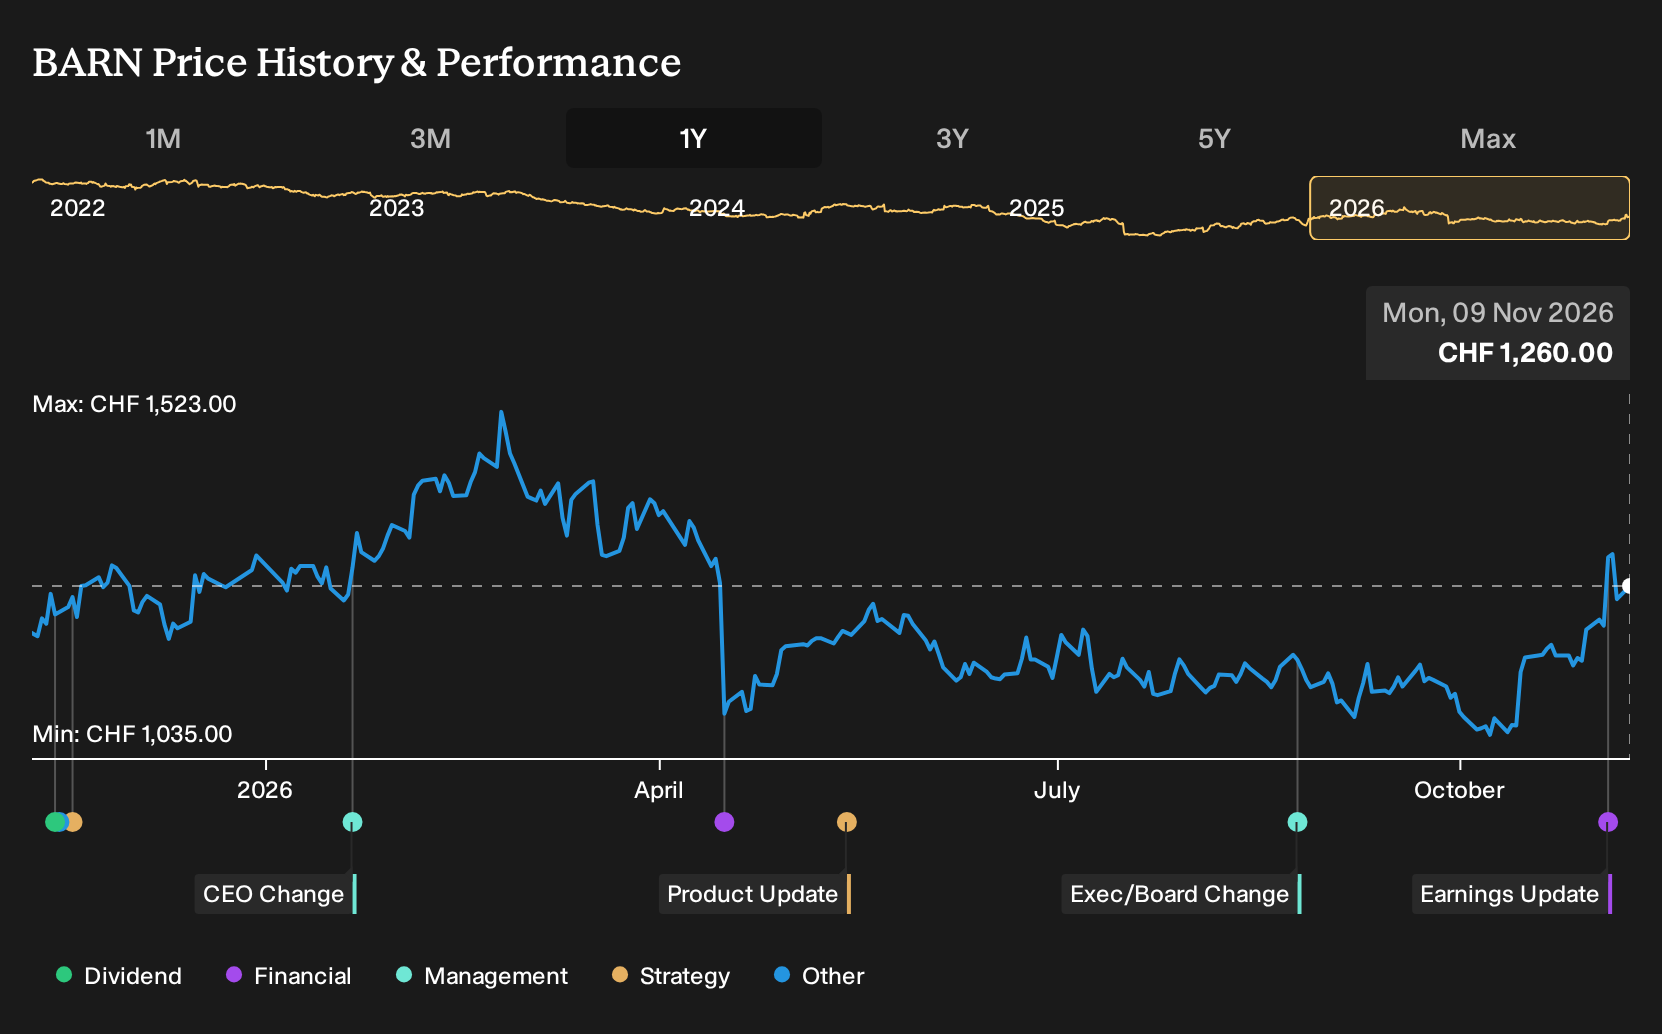
- Barry Callebaut reported full year 2026 results with sales of CHF 12,189.57 million and net income of CHF 157.24 million, both lower than the prior year.
- The drop in basic earnings per share from continuing operations to CHF 28.67 highlights pressure on profitability despite Barry Callebaut's focus on higher value chocolate and cocoa solutions.
- This article examines how Barry Callebaut's earnings decline and softer profitability may be reshaping the investment narrative built around mix and margin.
Compare Barry Callebaut's earnings reset with other resilient consumer stocks by scanning our hand picked list of list of solid balance sheet and fundamentals (194 results)
Barry Callebaut Investment Narrative Recap
To stay invested in Barry Callebaut, you need to believe the Focus for Growth plan can steadily lift profit per tonne even while volumes grow only modestly and cocoa markets stay volatile. The latest full year result, with weaker sales and earnings, keeps the main near term catalyst squarely on execution of mix improvement toward Gourmet, specialties and higher value cocoa solutions.
The biggest immediate risk remains cocoa price swings and elevated carry costs keeping net margins tight, especially while interest expenses are not comfortably covered by earnings. If sourcing tools and efficiency efforts do not gain traction quickly enough, the reset in profitability may linger without materially changing the longer term mix and margin narrative described in the analyst consensus Narrative on Simply Wall St.
The most relevant recent development for this story is the full year 2026 earnings announcement. Sales of CHF 12,189.57 million and net income of CHF 157.24 million sit against a backdrop in which analysts expect revenue to decline by 2.1% per year over the next 3 years. At the same time, they forecast faster earnings growth, with efficiency and mix expected to do more of the heavy lifting.
For you, the link to catalysts is direct. Management wants profit to run ahead of volume through higher value chocolate and cocoa platforms, while working toward net debt to recurring EBITDA of roughly 2.5x to 3x and lower finance costs. Execution on the Focus for Growth plan, cost control in a volatile bean market and balance sheet discipline all matter more after this earnings reset.
Barry Callebaut's narrative projects CHF 11.1b revenue and CHF 423.9m earnings by 2029. This assumes revenue declines 7.9% per year and an earnings increase of about CHF 180.7m from CHF 243.2m today.
Uncover how Barry Callebaut's fair value indicates a 9% potential downside to its current price, a premium that may not hold.
Exploring Other Perspectives
One alternate view puts less weight on cocoa volatility and more on weak end demand. Those bearish analysts were pencilling in revenue of about CHF 8.5b and earnings near CHF 403.8m by 2029, well below consensus. That tells you opinions on Barry Callebaut differ sharply and could shift again after this earnings reset.
Explore 2 other Barry Callebaut fair value estimates, including one that suggests as much as 65% downside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Barry Callebaut research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Barry Callebaut. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Barry Callebaut's overall financial health at a glance.
Looking for more investment ideas beyond Barry Callebaut?
Once you have a view on Barry Callebaut, it can help to cross check your thinking against other opportunities that fit different risk and income profiles. The Simply Wall St Screener lets you filter for balance sheet strength, income potential and quality so you can build a watchlist that matches your own playbook instead of someone else's.
- If capital protection sits near the top of your priorities, start with resilient businesses that score well on stability using our 202 resilient stocks with low risk scores.
- For readers hunting for mispriced quality, narrow the field to companies with solid fundamentals and room for sentiment to catch up through the 572 high quality undiscovered gems.
- If reliable income is more appealing than chasing rapid gains, focus your shortlist on companies that offer stronger yield profiles via the 222 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com