


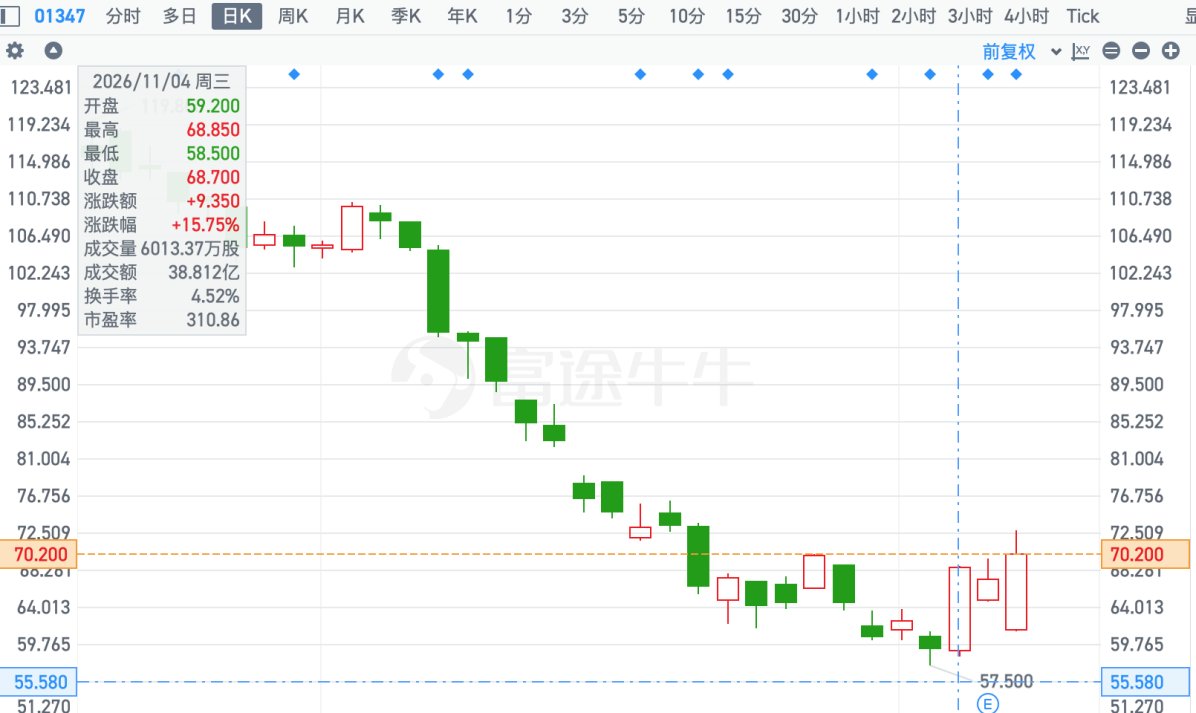
The Hong Kong stock market after the release of the third quarterly report of Huahong Hongli (01347) showed a positive signal among a set of differences: bears did not shrink due to the performance window on the day of the results announcement. However, on November 6, Citi immediately reiterated its “buy” and pushed the target price to HK$175, and the stock price immediately rose. Furthermore, in the past 90 days, 6 investment banks gave purchase ratings, and the target average price was HK$140.74.
It can be seen from this that the market disagreement is not about “good or bad” performance, but rather whether Hualiwei's “quality” of the first quarter can be continuously priced — revenue of 987 million US dollars in a single quarter, up 19.9% year on year, gross profit margin of 24.6%, up 7.6 percentage points year on year, and capacity utilization rate of 102.9%, while excluding Hualiwei's independent revenue of 803 million US dollars is still above the upper limit of previous guidelines. This provides a more solid fundamental anchor point compared to the scale of the consolidated table.
The parallel effect behind record revenue resonates with endogenous growth
According to the Zhitong Finance App, Huahong Hongli's third quarterly report confirmed with solid financial data that it achieved a leap in scale and an upward shift in profit center after completing Hualiwei's merger.
First, what needs to be clarified is the difference between the “before adjustment” and “after adjustment” data in the report. Since Hualiwei is a merger of enterprises under the same control, the report has retrospectively adjusted the data for the same period of the previous year. On top of the adjusted high base, the company still achieved revenue of 6.706 billion yuan in the third quarter, an increase of 13.95% year on year. The cumulative revenue for the first three quarters reached 18.611 billion yuan, an increase of 14.06% year on year. Combined with its record revenue performance of US$987 million in a single quarter, this increase not only includes the increase in scale brought about by the merger, but also reflects that the 12-inch business (which already accounts for more than 70.7%) achieved a sharp rise in volume and price with a capacity utilization rate of up to 102.9% at full load.
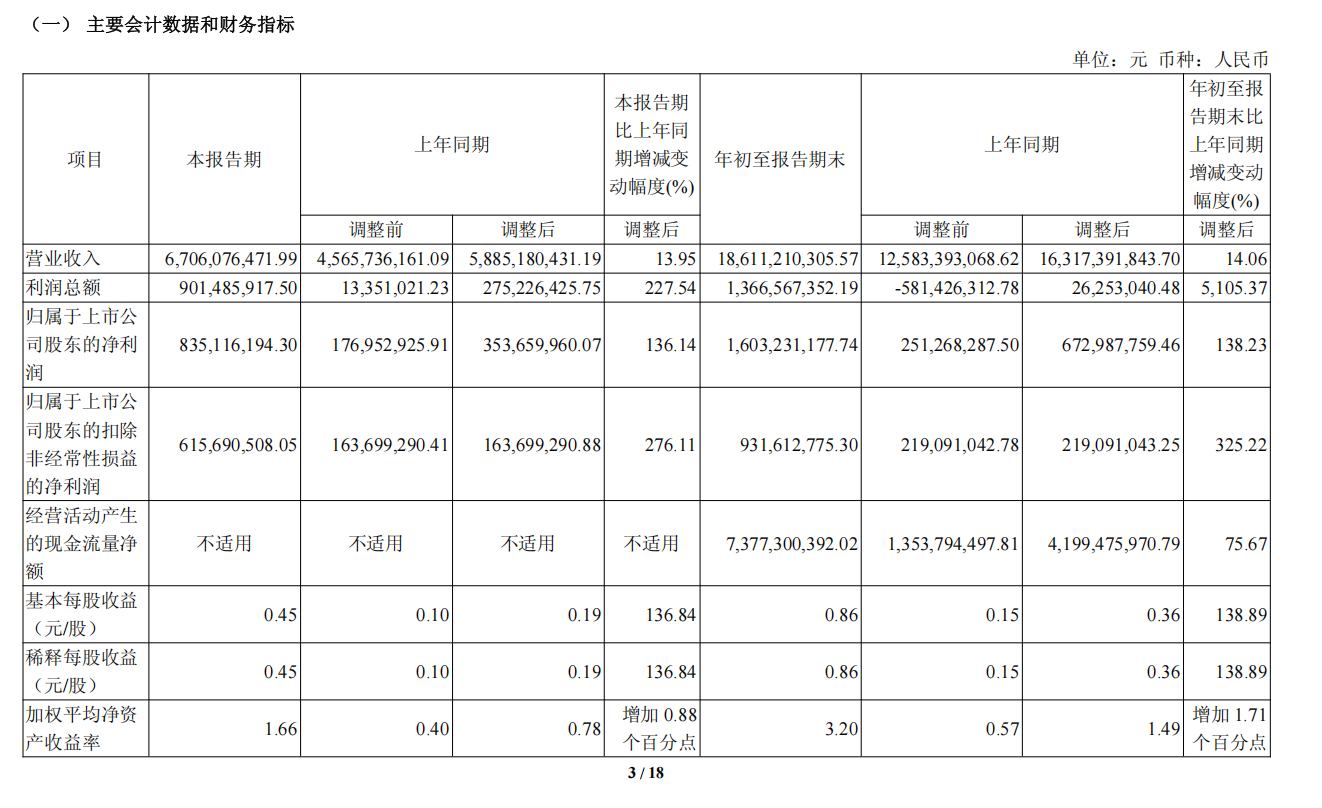
Second, the profit side of Huahong Hongli also ushered in an explosion. Net profit attributable to shareholders of listed companies in the third quarter reached 835 million yuan, up 136.14% year on year; net profit after deducting non-recurring profit and loss reached 615 million yuan, surging 276.11% year on year, and the increase in net profit deducted for the first three quarters also reached 325.22%. The growth rate after deducting non-net profit far exceeds revenue and net profit attributable to mother, indicating that the endogenous profit flexibility of the company's core foundry business is being unleashed at an accelerated pace. Behind this is the continuous improvement of the product portfolio of specialty process platforms and the direct dividends brought about by the rise in average sales prices due to a tight balance between supply and demand for mature processes.
For asset-heavy, long-cycle industries such as foundry, strong hematopoietic capacity is a lifeline through the production capacity cycle. In the first three quarters, net cash flow from the company's operating activities reached 7.377 billion yuan, a year-on-year increase of 75.67%. This abundant endogenous cash flow is not only a strong confirmation of the current profit quality, but also provides a solid financial guarantee for the entry and subsequent expansion of equipment for the Fab 9B production line in Wuxi. In a context where the industry has yet to completely break out of the bottom of the cycle, this “grain and grass” will effectively cushion the phased impact of depreciation and amortization on profit statements after future Fab 9B centralized consolidation, so that the company can maintain strategic strength during countercyclical expansion of production.
AI wave spillover effect+domestic supply chain restructure+production capacity release to build a moat leading foundry
In addition to focusing on Huahong Hongli's financial reports, the AI wave resonates with supply chain restructuring, and specialty process OEM ushered in a structural recovery, which is the foundation for strong business growth.
Although the explosion of global artificial intelligence models and intelligent computing centers has directly driven the explosion of advanced manufacturing processes, the more profound impact is the spillover of supporting demand around computing power. Demand for power management, microcontrollers, and standalone flash memory for AI servers is growing exponentially. This is the core hinterland of Huahong Hongli's “Featured IC+ Power Devices” moat.
According to the Huaxin Securities Research Report, the company's MCU, standalone flash memory and BCD process products are being vigorously promoted, directly driving the high utilization rate of production capacity. More importantly, in the context of geopolitics and deep restructuring of global supply chains, domestic chip design companies' demand for safety in the local foundry supply chain has reached an unprecedented level. As the fifth largest pure wafer foundry in the world and the second largest pure wafer foundry in mainland China, Huahong Hongli objectively undertook a large number of domestic replacement orders for mature processes and characteristic processes. This demand-side certainty provided a solid macroeconomic foundation for the company to absorb production capacity from 2026 to 2028.
In terms of horizontal expansion of technology and product matrices, Huahong Hongli did not stop at the price war of low-end mature manufacturing processes, but continued to penetrate high-value-added market segments. The company's 40nm ultra-low power specialty process has been successfully mass-produced, which will significantly extend the battery life of IoT and wearable devices and help the company seize the low-power blue ocean market. At the same time, stable mass production of the 55/40nm specialty process and RFCMOS process process, and the revenue of the 65nm RF SOI process platform continues to grow, indicating that the company's technical barriers on high-margin circuits such as simulation, RF and power management are getting stronger. This technological evolution not only optimized the product portfolio, but was also the core driving force behind the sharp recovery of gross margin to 24.6% in the three-quarter report.
What supports the above technology and order fulfillment is the pace of Huahong Hongli's production capacity expansion. The production capacity of the new 12-inch production line (FAB9) in Wuxi climbed extremely smoothly. The share of 12-inch revenue in the first quarter of 2026 had risen rapidly to 62.7%, and by the time of the three-quarter report, this ratio had already exceeded 70.7%. For an asset-heavy, long-cycle foundry, the new production line climbs rapidly and remains fully loaded, which means that the scale effect is rapidly diluting fixed costs. As the pace of Fab 9B equipment entering the factory accelerates, the company will usher in a more significant period of production capacity release in 2027. In response to market concerns about depreciation pressure, combined with operating cash flow of 7.377 billion yuan and a sharp increase of 75.67% year over year in the three-quarter report, it can be seen that with its strong endogenous hematopoietic capacity, the company is fully emboldened to cross the painful profit period brought about by the restructuring of the new production line.
More importantly, judging from the combined first-quarter performance of the three quarterly reports, Hualiwei not only brought in record revenue of US$987 million in a single quarter, but also showed significant financial gains and operational synergy. Hualiwei's deep accumulation on the 12-inch production line perfectly complements Huahong's original 8-inch and 12-inch specialty processes, enabling Huahong to leap forward in the scale and technical coverage of the 12-inch specialty process foundry field. This “endogenous production capacity release+epitaxial asset injection” two-wheel drive enables the company to have stronger order acceptance capacity and ASP (average selling price) bargaining power in the face of a tight balance between supply and demand in 2027 or even 2028. The management's guidance of expecting an ASP increase of 10% to 15% in 2027 is based on this.
Looking at marginal changes in financial statements, Huaxin Securities predicts that the company's revenue from 2026 to 2028 will reach 21,635 billion yuan, 26.194 billion yuan, and 29.947 billion yuan, respectively. Net profit to mother is also expected to jump from a low in 2025 (377 million yuan) to 1,825 billion yuan in 2028. In this forecast trajectory, we can see not only an expansion in revenue volume, but also a steady recovery of ROE from 0.6% to 2.9%, and a substantial upward shift in net profit from negative to positive.
In summary, in the macro context of the spillover demand for AI edge applications and global supply chain restructuring, Huahong Hongli is moving towards more definitive structural growth with a “8+12” inch characteristic process matrix and deep collaboration with Hualiwei. However, the depreciation pressure brought about by the centralized consolidation of Fab 9B in 2027 is still a litmus test for its profitability. Fortunately, the current abundant operating cash flow has built a solid financial cushion for it. With the gradual implementation of the 2027 average price increase guidelines and the continuous penetration of high value-added process platforms, the upward trajectory of Huahong Hongli as a leading local foundry manufacturer is already clear.