


ConnectOne Bancorp has seen its share price move sharply over recent years, which puts fresh attention on whether the current valuation is supported by the returns it earns on its capital. For investors watching a regional bank with this kind of share price history, the core issue is how much of that move lines up with the underlying profitability of the business.
- Over the past 3 years the stock has returned about 106.2%, which puts real weight on the question of whether those gains are matched by the bank's ability to earn attractive returns on the capital it deploys.
- As a lender that depends on how efficiently it puts deposits and equity to work, ConnectOne Bancorp's future value case rests heavily on whether it can keep earning solid spreads on its loan book without taking on disproportionate risk, since that is what ultimately drives its return on capital.
- If you'd rather focus on earnings, this one's for you. See what ConnectOne Bancorp's 11.5x P/E says about the price.
The stock's next move may depend on whether the returns ConnectOne Bancorp earns on its capital are strong enough to justify where the share price sits today.
If you are weighing whether ConnectOne Bancorp's 3 year return of 106.2% is supported by its capital returns, it can help to compare that question across 30 resilient stocks with low risk scores.
Does ConnectOne Bancorp Look Undervalued on Excess Returns?
The Excess Returns model examines how profit on equity compares with the cost of that equity. For ConnectOne Bancorp, the key inputs show a Book Value of $29.66 per share and a Stable EPS estimate of $3.85 per share, based on Return on Equity forecasts from 4 analysts. Those earnings are measured against a Cost of Equity of $2.69 per share, which leaves an Excess Return of $1.16 per share.
An average Return on Equity of 11.55% on a Stable Book Value projected at $33.33 per share points to a bank that the model treats as able to earn more than its equity charge on a sustained basis. With the Excess Returns output indicating an intrinsic value substantially above the current share price of $33.02, the model is flagging a gap between what the market is paying and what these projected returns on capital might support over time. Find out what ConnectOne Bancorp could be worth using our Excess Returns estimate.
The ConnectOne Bancorp Narrative: What Would Justify Today's Price?
Narratives pick up where the valuation puzzle for ConnectOne Bancorp leaves off, by explaining which paths for growth, profitability and earnings would need to occur for the shares to trade meaningfully higher or lower than today’s price. These narratives are hosted on Simply Wall St's Community page. Rather than relying on a single multiple or model line, each one lays out the assumptions behind its estimate so you can compare those to actual results over time.
One of the top narratives on ConnectOne Bancorp: 10% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"ConnectOne Bancorp is working through a large pipeline of adjustable rate and fixed loans that are repricing at higher yields, with about US$700m already repriced in 2026 at an average 255 basis point increase…"
Discover why this Narrative puts ConnectOne Bancorp at 10% undervalued.
ConnectOne Bancorp’s price story is only one side of the decision
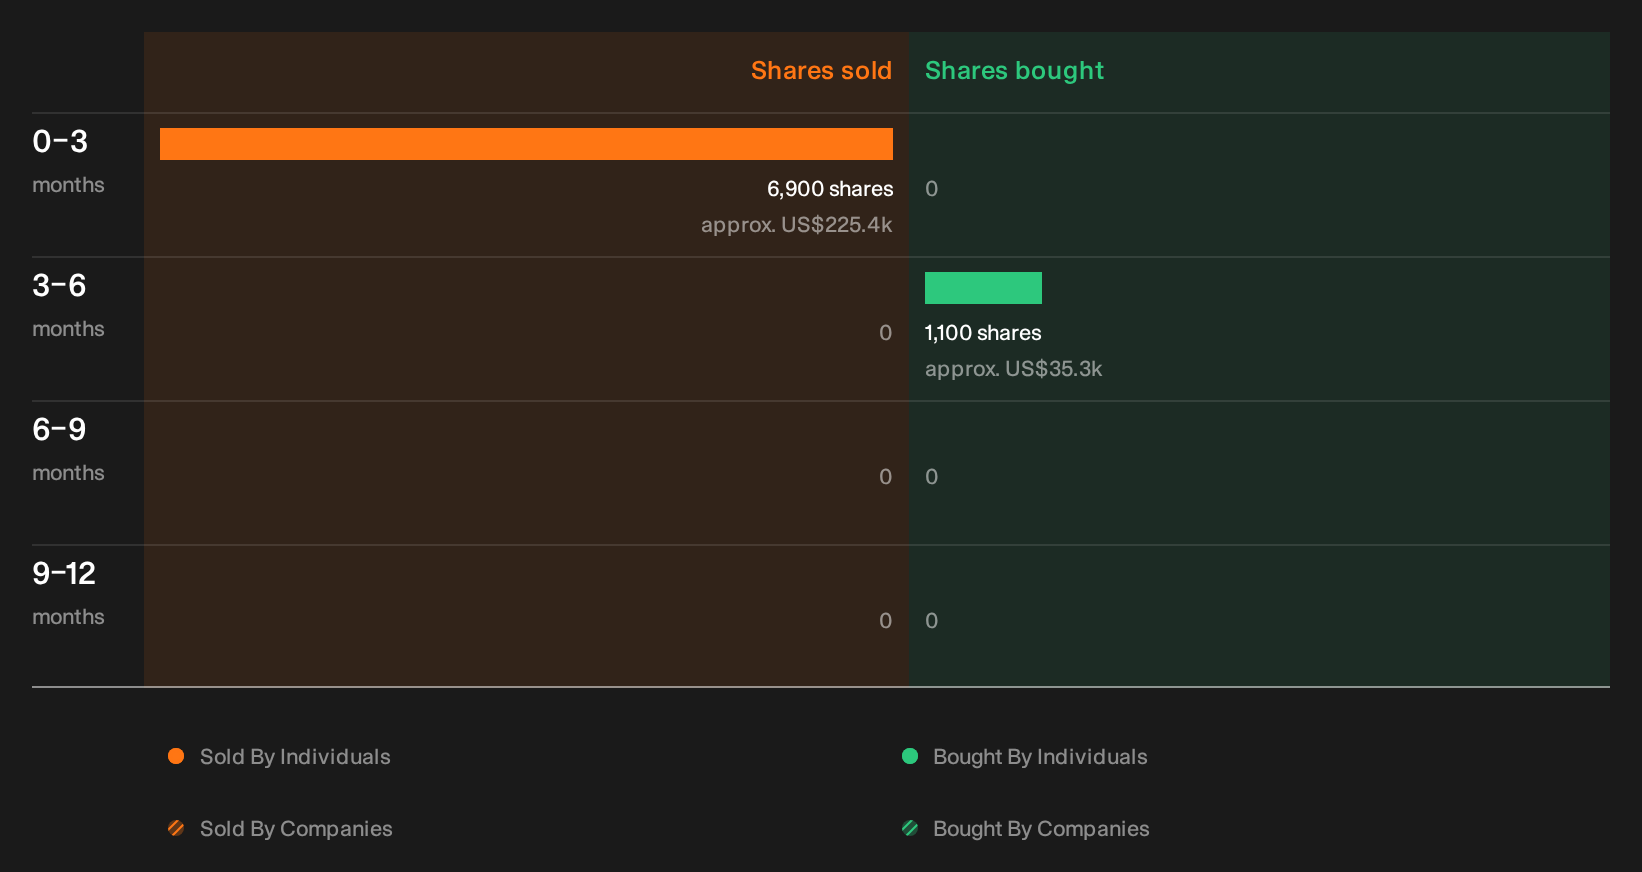
Before you focus solely on what the market is willing to pay for ConnectOne Bancorp, it is worth checking what recent moves by its own insiders might be signalling about the risk and reward balance. See the recent insider selling flagged for ConnectOne Bancorp.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com