


Pandora (CPSE:PNDORA) drew fresh attention after raising its EBIT margin guidance for 2026 and updating 2027 targets, alongside reporting higher third quarter sales and earnings per share compared with the prior year.
The guidance upgrade and stronger third quarter have landed alongside a clear shift in market sentiment. Pandora’s share price is at DKK925.2, with a 7 day share price return of 9.8% feeding into a 33.01% year to date gain and 21.73% 1 year total shareholder return, which points to momentum building rather than fading.
Position your next move alongside Pandora by scanning a focused short list of 204 high quality undervalued stocks that also show solid momentum in their recent returns.The guidance shift and price surge leave Pandora trading above the average analyst target, yet still at a discount to one estimate of fair value. Is investor caution now misplaced, or is the valuation gap there for a reason?
Most Popular Narrative: 7.8% Overvalued
Pandora's analyst consensus Narrative on Simply Wall St points to a fair value of DKK858, which sits below the latest DKK925.2 close. This frames the recent rally as stretching above that estimate, using a 7.45% discount rate to pull future cash flows back into today's terms.
The main factor that has to go right is that the shift to platinum plated jewelry and lower promotional intensity protects gross margins near 80% and EBIT margins above 21%, while demand in mature regions absorbs this reset.
The planned increase in inventory of up to DKK 3 billion in 2026 to support the platinum transition means higher net working capital for a period. This could weigh on free cash flow before the expected margin benefits are reflected in earnings.
See why 17 investors see Pandora as 8% overvalued.
Result: Fair Value of DKK858 (OVERVALUED)
Still, the narrative breaks if commodity and FX pressures squeeze Pandora margins harder than expected, or if the platinum inventory build lingers and drags on cash generation.
Find out about the key risks to this Pandora narrative.
Another View on Pandora’s Valuation
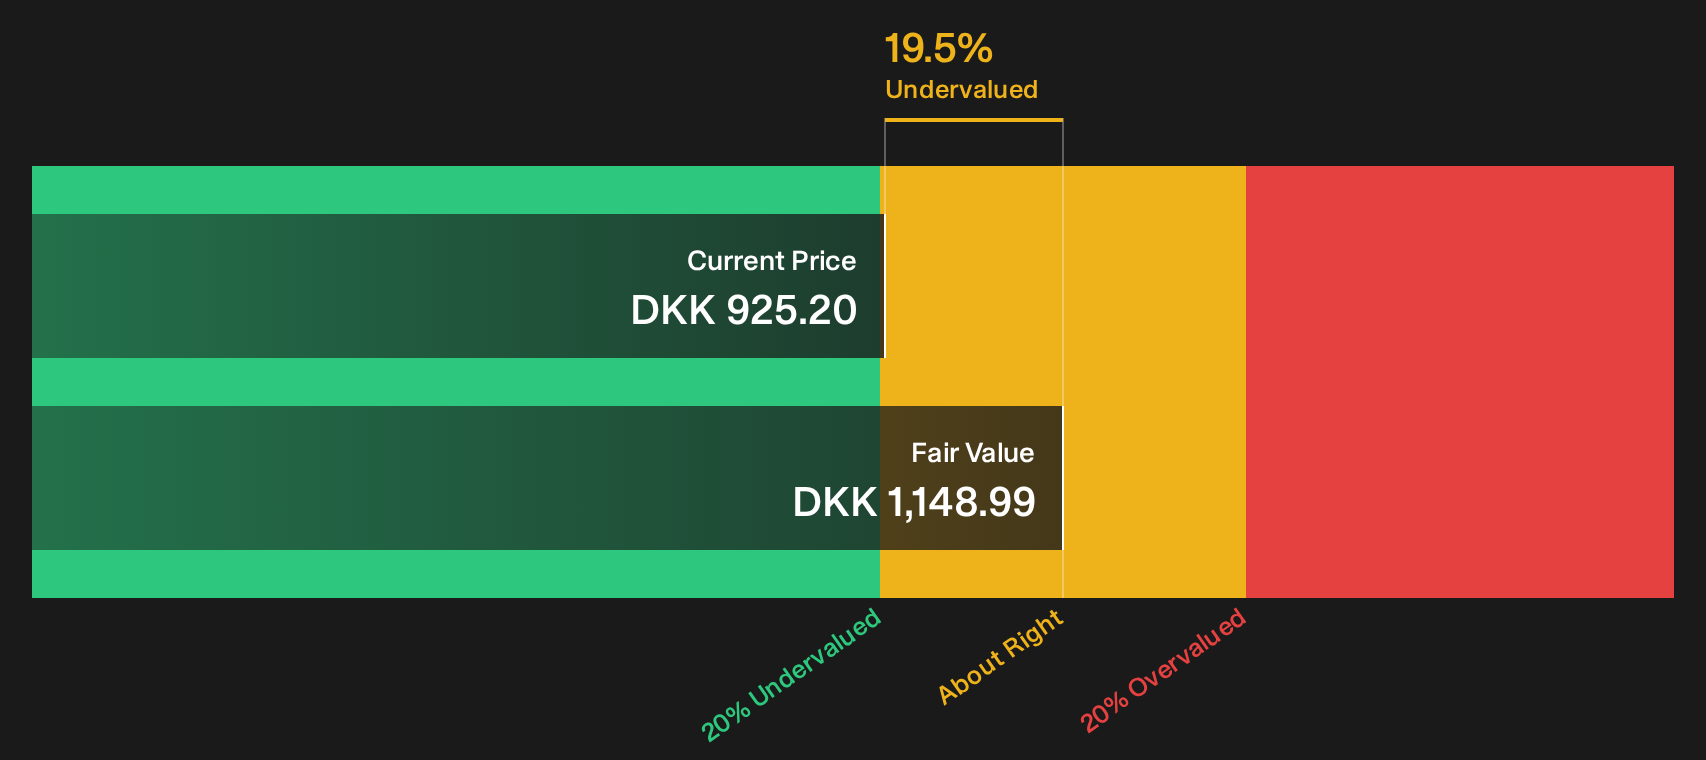
The Simply Wall St DCF model points in the opposite direction to the analyst consensus Narrative. On that framework, Pandora at DKK925.2 trades around 19.5% below an estimated future cash flow value of DKK1,148.99, which frames the stock as undervalued rather than mildly overvalued. Which lens do you trust when the signals clash?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the split verdict on Pandora leaves you torn, move quickly from reading to testing the numbers yourself and pressure test both sides of the story. For a sharper view of where conviction and concern meet, start with the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Pandora?
Consider broadening your search beyond Pandora. Use these focused stock lists to quickly surface other opportunities that align with your priorities on value, income, and resilience.
- Explore potential mispricings by reviewing the 204 high quality undervalued stocks that pair quality fundamentals with room for sentiment to catch up.
- Strengthen your income stream by scanning the 217 dividend fortresses that combine higher yields with disciplined payout profiles.
- Seek greater portfolio stability by focusing on the 202 resilient stocks with low risk scores that score well on balance sheet strength and business stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com