


- L'Air Liquide was recently added to the Zacks Rank #5 (Strong Sell) list after analysts revised current year earnings estimates 6.8% lower over the past 60 days.
- The sharper earnings downgrade raises questions about near term cost pressure, demand trends and execution against the BEYOND investment and efficiency program.
- We will now explore how L'Air Liquide's investment narrative compares with this earnings downgrade driven shift in analyst expectations.
Balance that downgrade signal on L'Air Liquide by scanning a curated set of resilient businesses in our 202 resilient stocks with low risk scores that could be better positioned to handle similar earnings pressure.
L'Air Liquide Investment Narrative Recap
To own L'Air Liquide, you need to believe in a long build out of gas and services tied to electronics, healthcare and the energy transition, supported by the BEYOND efficiency and investment plan. In the short term, the key swing factor is how quickly new semiconductor and low carbon projects translate into higher volumes while existing customers, especially in European Large Industries, keep plants running and renewing contracts.
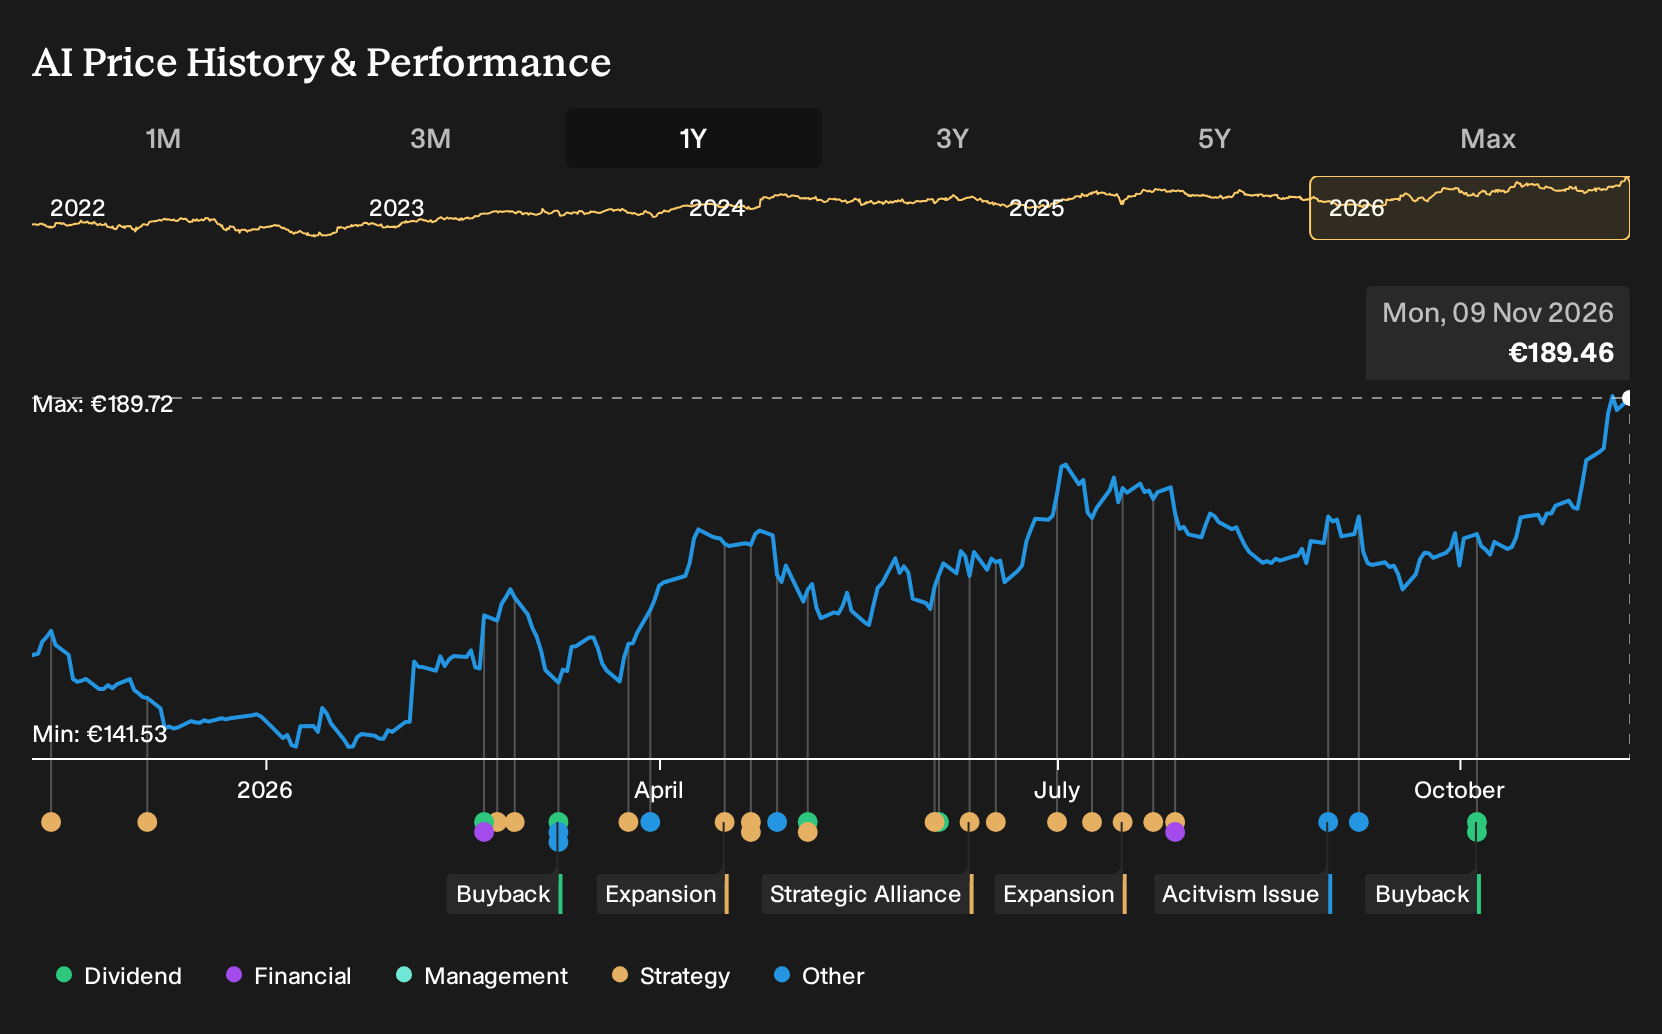
The biggest current risk is that volumes stay soft in several core lines or energy intensive customers shut more assets, which would challenge the sales growth narrative in the analyst consensus Narrative on Simply Wall St. The recent earnings downgrade points to near term pressure, but it does not on its own rewrite that longer term investment case if the €40b project pipeline continues to move into execution.
With no fresh corporate announcements tied directly to the Zacks downgrade, the most relevant reference point remains the BEYOND plan and its €40b of planned investments through 2030 highlighted in the analyst consensus Narrative on Simply Wall St. Those projects in electronics, hydrogen and carbon capture form the operational backdrop against which any earnings revision should be viewed, because they frame capacity, capital spend and future revenue mix.
That same plan includes a targeted 400 to 600 basis point uplift in operating margins by 2030, supported by AI enabled process changes, shared service centers and prior headcount reductions. For you, the practical question is whether the near term earnings reset hints at slower progress on those efficiencies or simply reflects timing and cost tension as L'Air Liquide moves large electronics and energy transition projects from backlog into active plants.
L'Air Liquide's narrative projects €31.8b revenue and €5.1b earnings by 2029. That profile lines up with analysts assuming 5.6% yearly revenue growth and an earnings increase of about €1.6b from €3.5b today.
Uncover how L'Air Liquide's fair value indicates a 5% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Five fair value views from the Simply Wall St Community range from about €137 to €202, so retail investors are clearly not clustered around a single price for L'Air Liquide. Those opinions were set before the Zacks Rank #5 downgrade. As a result, you are weighing them against fresh earnings estimate pressure and reassessing what really drives future resilience.
Explore 4 other L'Air Liquide fair value estimates, including one that suggests as much as 27% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your L'Air Liquide research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for L'Air Liquide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate L'Air Liquide's overall financial health at a glance.
Looking for more investment ideas beyond L'Air Liquide?
If the L'Air Liquide story has sharpened your thinking about risk, value and income, you can use that momentum to widen your opportunity set with a few targeted stock searches on Simply Wall St.
- For investors who care most about financial resilience and balance sheet strength, start with a curated list of solid balance sheet and fundamentals (194 results) to help you focus on businesses built to withstand pressure.
- If potential mispricing is your priority, scan a concentrated pool of 204 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them.
- Income-focused portfolios can begin with a hand-picked group of 217 dividend fortresses and then filter for the payout profiles that best match personal goals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com