


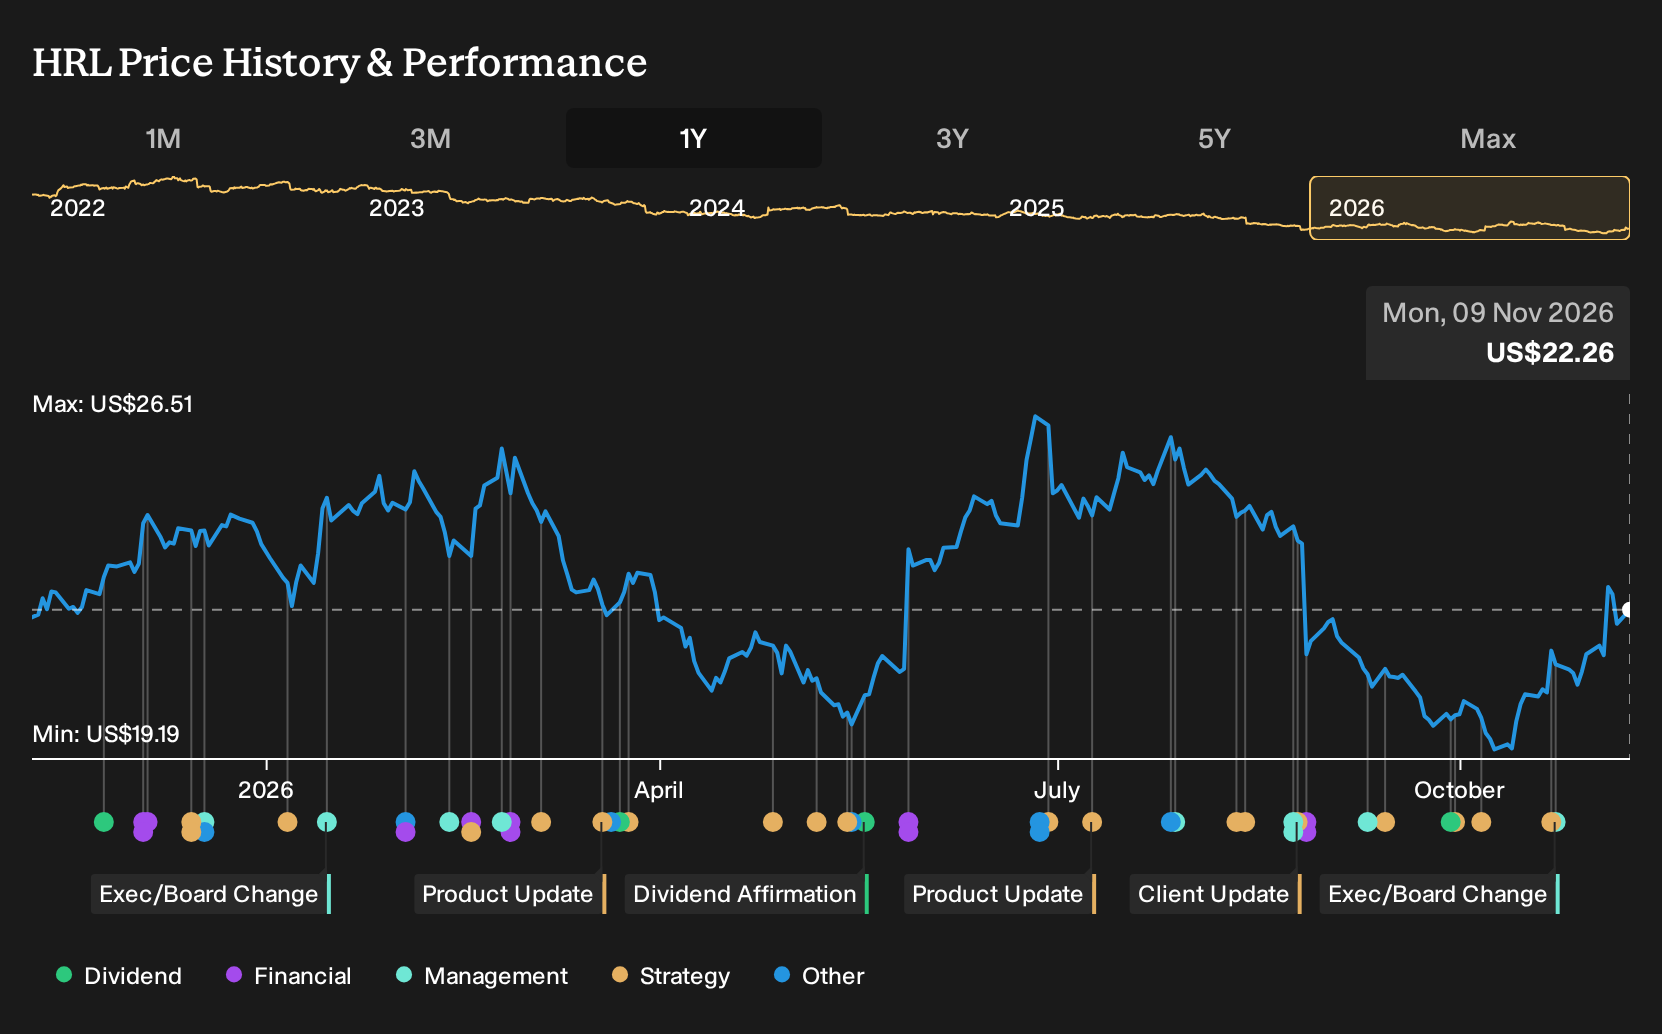
- Hormel Foods has drawn fresh attention from long term investors after restructuring moves and portfolio simplification efforts aimed at streamlining operations and improving margins, along with the appointment of new CEO John Ghingo to guide a potential turnaround.
- The combination of margin focused portfolio changes and a leadership transition gives investors a clearer view of how Hormel Foods might respond to shifting consumer preferences and cost pressures across its protein and packaged foods categories.
- We will now look at how Hormel Foods' investment narrative could be influenced by John Ghingo's leadership and recent restructuring.
Compare Hormel Foods' turnaround pitch with other income focused opportunities by scanning a hand picked list of 6 dividend fortresses that may better balance yield and resilience.
Hormel Foods Investment Narrative Recap
To own Hormel Foods, you need to be comfortable with a slow growing top line, a focus on value added protein, and a heavy tilt toward brands and foodservice. The analyst consensus Narrative on Simply Wall St leans on earnings forecasts that assume portfolio simplification and better mix eventually show up in cleaner margins and steadier profit, though the recent net margin of 2.8% keeps that an open question.
The most important near term swing factor is whether restructuring and cost work can stabilize earnings while retail volumes remain under pressure and foodservice grows into a larger role. The clearest risk is still commodity and freight costs, together with any renewed pushback on pricing that could keep profit margins stuck well below prior levels.
The recent focus on restructuring and leadership change under CEO John Ghingo sits against a backdrop of big portfolio moves already in motion. Management is simplifying Hormel Foods by exiting lower margin and more volatile revenue streams, with roughly US$300m of sales removed from areas such as whole bird turkey, Brazil operations and private label snack nuts.
That clean up matters for the same catalysts investors are watching today. A leaner mix can make it easier to see whether value added protein, foodservice expansion such as the planned Brakebush Brothers acquisition, and product development actually translate into better blended margins, stronger earnings coverage of the 5.26% dividend, and less sensitivity to swings in individual categories or regions.
Hormel Foods' current analyst narrative projects US$12.6b in revenue and US$1.3b in earnings by 2029, which implies 1.2% yearly revenue growth and an increase in earnings of roughly US$957m from the US$342.7m reported today.
Uncover how Hormel Foods' fair value indicates a 14% potential upside to its current price, a discount that could close sooner than many expect.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between US$25.31 and US$47.99, which shows how far views on Hormel Foods can spread. Before the recent leadership and portfolio news, some members focused on catalysts such as foodservice expansion, while others flagged commodity and pricing risks. Use these contrasting opinions to pressure test your own view.
Explore 2 other Hormel Foods fair value estimates, including one that suggests potential upside of as much as 116% from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hormel Foods research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Hormel Foods. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hormel Foods' overall financial health at a glance.
Looking For More Investment Ideas Beyond Hormel Foods?
Once you have a view on Hormel Foods, it can help to compare that thesis with other opportunities that match your income, quality, or risk tolerance preferences. The Simply Wall St Screener lets you filter for those traits directly, so you can quickly see which listed businesses line up with the kind of portfolio you actually want to build.
- If you care most about dependable balance sheets and robust fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can help you stress test quality across sectors.
- For investors looking to tilt toward value opportunities with stronger fundamentals, review a 19 high quality undiscovered gems that might not be widely followed yet.
- When capital preservation and stability take priority, narrow your search using a 30 resilient stocks with low risk scores that filters for companies with more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com