


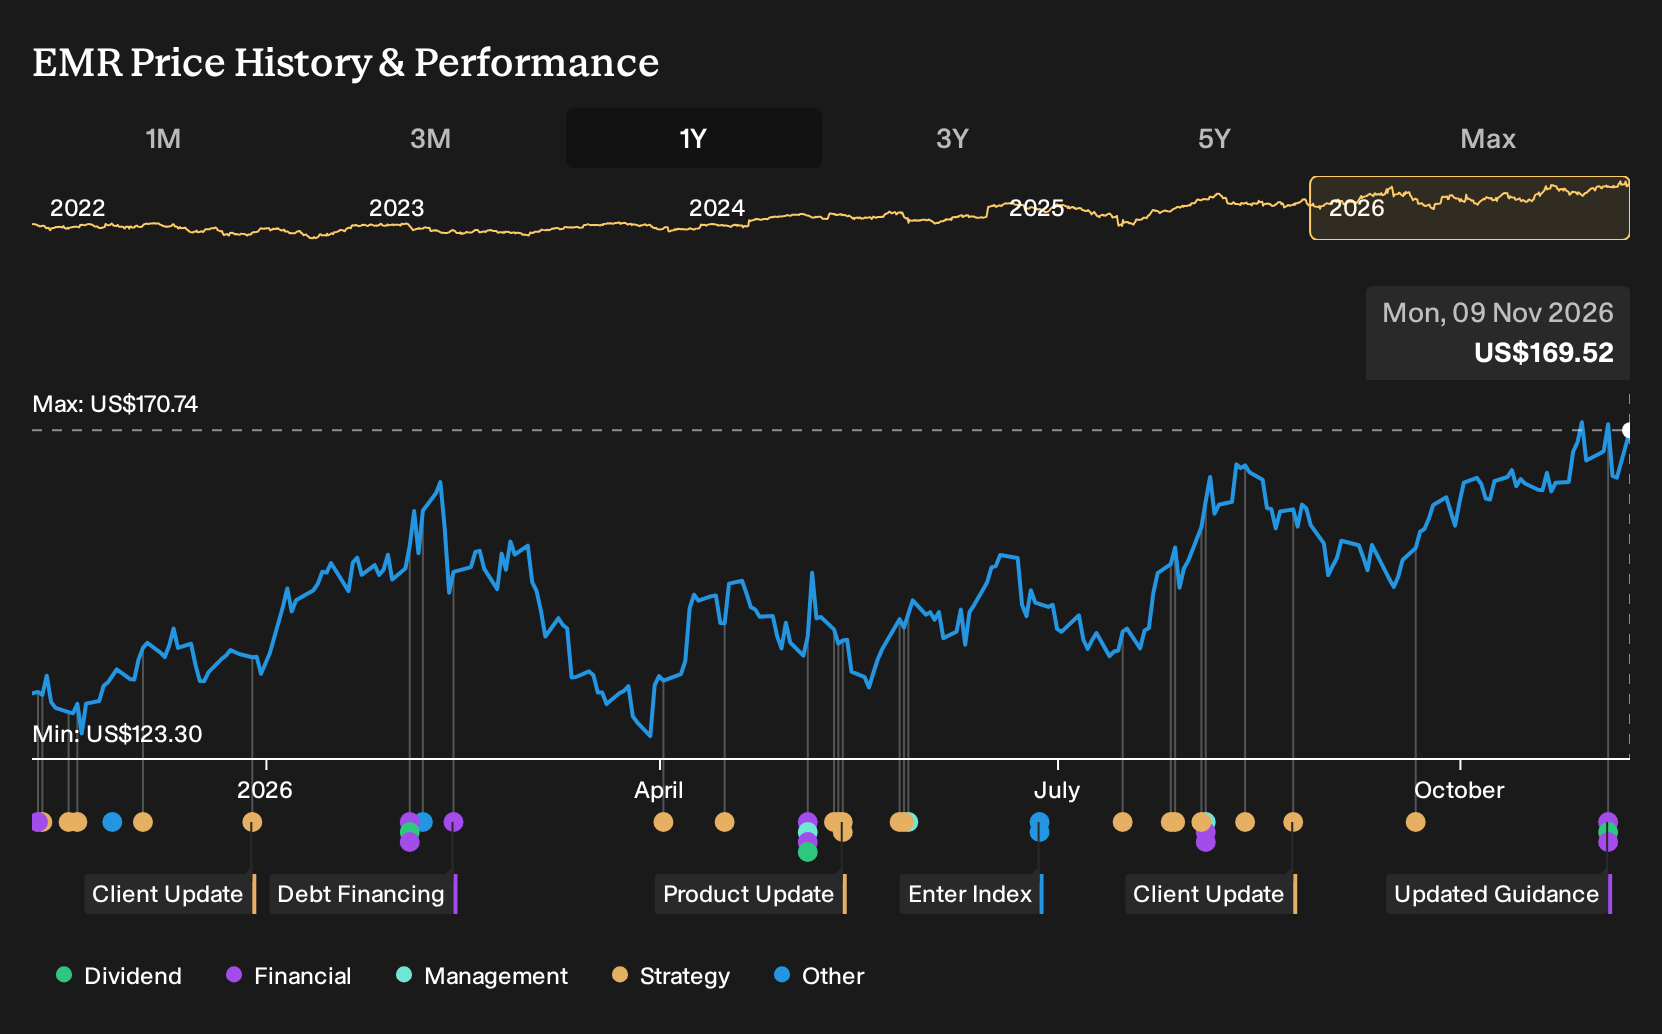
If you noticed Emerson Electric win a multi million dollar automation contract for BP’s Shah Deniz compression project and focused on that development, you saw a concrete piece of long cycle work added to the backlog. Holding Emerson Electric over the past year would have returned 32.5%, including dividends. If you had been deciding on 9 November 2025, what would you have needed to believe about contracts like Shah Deniz to justify buying before that news arrived?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
Emerson Electric is not the only name tied to this theme. Zero in on 91 robotics and automation stocks and compare how each one is priced.
The Argument You Would Have Been Weighing Up On Emerson Electric
The shares cost US$129 at the start of the period. Anyone looking at Emerson Electric then had to decide which story felt more realistic.
The bullish Narrative saw Fair Value at US$151, or 16% above the start price. This was built on an assumption that revenue could grow 6.2% a year with margins reaching 15.5% and a future P/E of 32.3x.
The bearish view put Fair Value at US$108, or 17% below the start price. This view focused on tariff pressure, rising competition and integration risk around AspenTech potentially squeezing profitability.
What The Results Changed In The Emerson Electric Story
The Shah Deniz automation award backed the optimistic view that Emerson Electric could keep winning large, long contract work. Later, Q4 2026 results showed revenue at US$5.20b and net income at US$744m versus US$4.86b and US$635m a year earlier, with net margin rising from 13.1% to 14.3%. The evidence supported the optimistic case more than the cautious one.
The practical takeaway is clear. When a thesis leans on long projects and higher profitability, you track contract wins and the reported net margin. That pairing tells you whether the backlog story and the promised economics are actually showing up in the financials at any industrial stock you follow.
What Emerson Electric's Run Now Assumes
Emerson Electric trades at US$170 after returning 32.5% over the past year. The bearish analyst Narrative on Simply Wall St sees its fair value below that level, since it frames the current quote as already baking in upbeat outcomes on projects and software-driven earnings.
The same Narrative leans on worries about long-cycle power and LNG awards, software renewals, and regional friction. A buyer today is effectively assuming the large project funnel turns into dependable profit, so how much weight do you put on execution risk around those contracts and future software renewal cycles?
"The numbers indicate that Emerson Electric’s current share price already reflects optimistic outcomes on long-cycle power, LNG, and software growth, so the valuation leaves limited room for disappointment on execution or macro shocks."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Where Emerson’s Theme Extends Next
Looking at Emerson Electric, you might already picture industrial plumbing for energy and automation. The same mindset can reach into data centres.
AI facilities need more than sensors and control systems. They depend on power and cooling gear that keeps dense hardware operating safely.
One specialist builds power units, thermal equipment and integrated infrastructure to support those server halls.
Its engineers work on liquid cooling and other dense thermal solutions, helping operators manage heat instead of simply using more water.
If you want to extend the Emerson Electric story into digital infrastructure, that is where your research list might head next.
One Narrative has already put a figure on it. → Uncover the company trading 51% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com