


MARA Holdings has seen its shares under pressure over the past few years while the business shifts away from pure Bitcoin exposure toward AI and high performance computing. This puts the spotlight squarely on what investors are paying for its sales today. With that backdrop, the key issue is whether the current valuation of the stock is adequately supported by the revenue the company is generating and expects from its changing operations.
- Over the past 5 years the share price has fallen 88.0%, which raises a direct question about how much of the original sales expectations are still being reflected in today's market value.
- The planned US$1.5b Long Ridge gas plant acquisition and the broader move toward AI and computing services can reshape MARA Holdings' revenue mix and timing. This matters for how investors weigh its price against its existing sales base.
- The analysts covering MARA Holdings have run their own numbers. See what analysts think MARA Holdings's shares could be worth.
The stock's next move may depend on whether MARA Holdings' current share price is well supported by its sales, given this shift in how the business uses its assets and power capacity.
To pressure test whether MARA Holdings' price really lines up with its sales story, you can compare it against a wider set of AI infrastructure plays using 53 AI infrastructure stocks.
Has MARA Holdings Run Too Far on Sales?
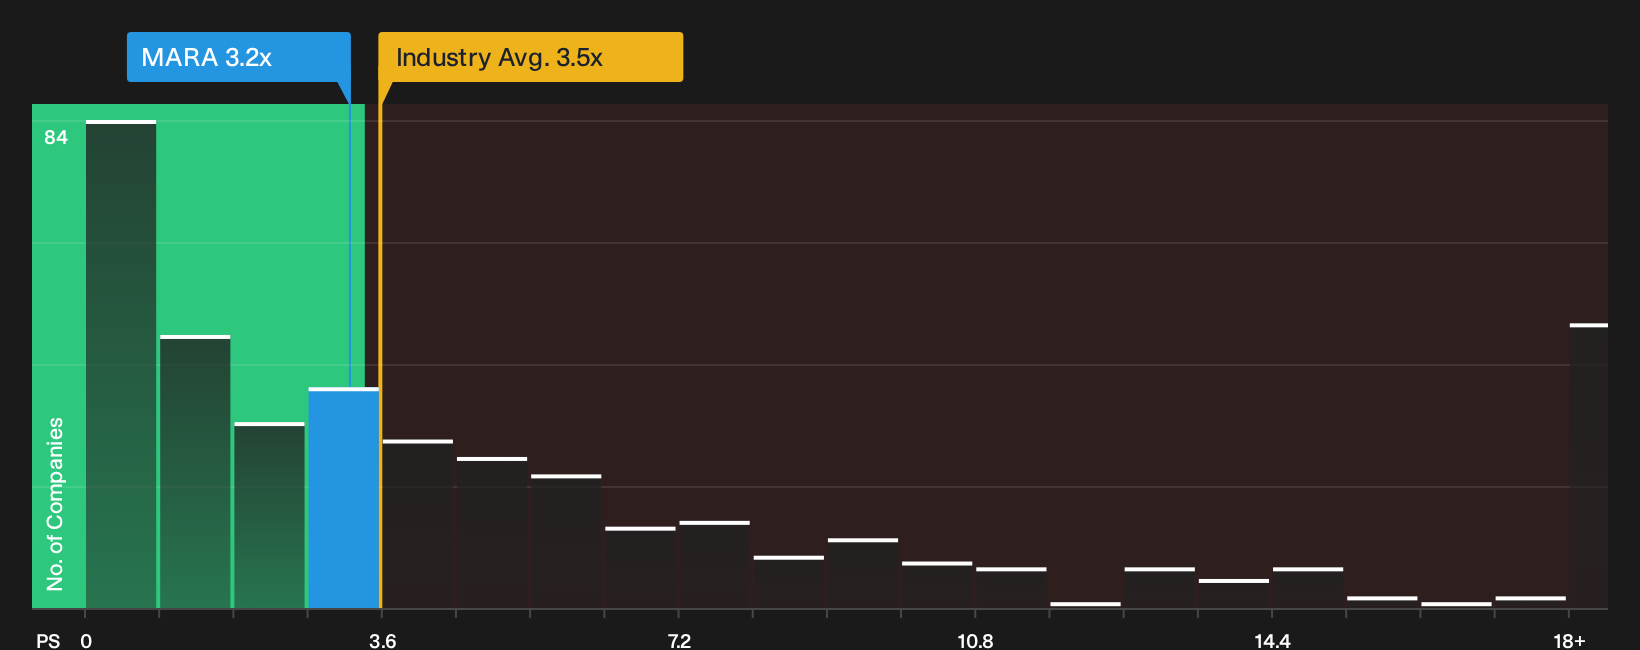
P/S is the cleaner yardstick for MARA Holdings right now because earnings and free cash flow are both in the red, while revenue still provides a clearer anchor. The stock trades on a P/S of 3.2x, a small discount to the wider software industry on 3.5x and a much lower level than the peer group average of 12.3x for similar AI and infrastructure plays.
That gap looks less generous once the tailored fair multiple is taken into account. On this framework, MARA Holdings screens overvalued on sales relative to what its mix of growth prospects, margins, size and risk profile would usually justify. Despite the FERC approval for the US$1.5b Long Ridge gas plant lifting interest in the AI and power story, the current P/S still asks investors to pay a premium compared with what the model implies for this revenue base. Explore the numbers behind MARA Holdings's P/S valuation.
The MARA Holdings Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for MARA Holdings pick up where the P/S debate leaves off and explain which combinations of future growth, margins and earnings would need to occur for the stock to be worth materially more or less than today’s price. Each idea on the Community page presents MARA Holdings' fair value as a thesis about how the business could develop over time, allowing you to see how that view holds up as new information emerges.
One of the top narratives on MARA Holdings: 62% undervalued
This Narrative is the analyst consensus Narrative on Simply Wall St, which compiles analysts' consensus price target and revenue and earnings forecasts, not one person's view.
"The valuation in this narrative implies that the market is not fully pricing in MARA Holdings’ potential to monetize its energized power, data center campuses and digital infrastructure platforms..."
Discover why this Narrative puts MARA Holdings at 62% undervalued.
MARA Holdings: one more question the valuation alone cannot answer
MARA Holdings' share price and P/S ratio tell only part of the story, because analyst models already sketch out where they think this business could be a few years from now. Explore where analysts expect MARA Holdings to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com