


- SEI Investments recently introduced the SEI Charitable Fund, a donor-advised fund solution powered by TIFIN Give and sponsored by GiveClear Foundation, adding charitable giving tools to its wealth, tax, estate, and legacy planning platform.
- The fund ties philanthropy directly into SEI Investments broader advisory workflows, which may deepen client relationships, support multigenerational engagement, and strengthen the appeal of its outsourced wealth platform to banks and advisors.
- We will now look at how SEI Investments investment narrative could shift as donor-advised fund technology becomes embedded in its platform.
Compare SEI Investments' push into digital-first philanthropy with other wealth platforms leaning into similar themes by scanning our hand-picked list of solid balance sheet and fundamentals (25 results).
SEI Investments Investment Narrative Recap
To own SEI Investments, you need to believe in a fee based platform that can keep adding services around wealth, data and outsourced operations without letting pricing pressure swamp margins. The analyst consensus Narrative on Simply Wall St points to growing earnings and high forecast return on equity, but also to slower expected top line growth than the broader US market.
In the short term, the key swing factor looks like execution on higher margin services and cost efficiency, set against risks from lower fee products, insider selling and any hit to free cash flow that could limit buybacks. The SEI Charitable Fund launch plugs directly into SEI Investments wealth platform, yet on its own it does not look like a material shift in that near term risk reward balance.
The most relevant recent move for this donor advised fund launch is SEI Investments earlier partnership with TIFIN Give, which supplies white labeled charitable solutions for SEI bank and wealth clients. That arrangement ties philanthropy tools into existing custody, advisory and investment workflows, so the new SEI Charitable Fund effectively rides on infrastructure already in place.
For catalysts, the interesting angle is how this sits alongside efforts in ETFs, Data Cloud and AI to deepen SEI Investments role as a full stack provider. If advisors use these giving tools to keep assets on platform and engage younger family members, it could support the analyst consensus Narrative on Simply Wall St over time, while fee mix, margin pressure and capital return discipline remain important watchpoints.
SEI Investments' narrative projects US$3.1b revenue and US$942.1m earnings by 2029. This is based on an assumed 7.0% yearly revenue growth rate and an earnings increase of about US$231.2m from US$710.9m today.
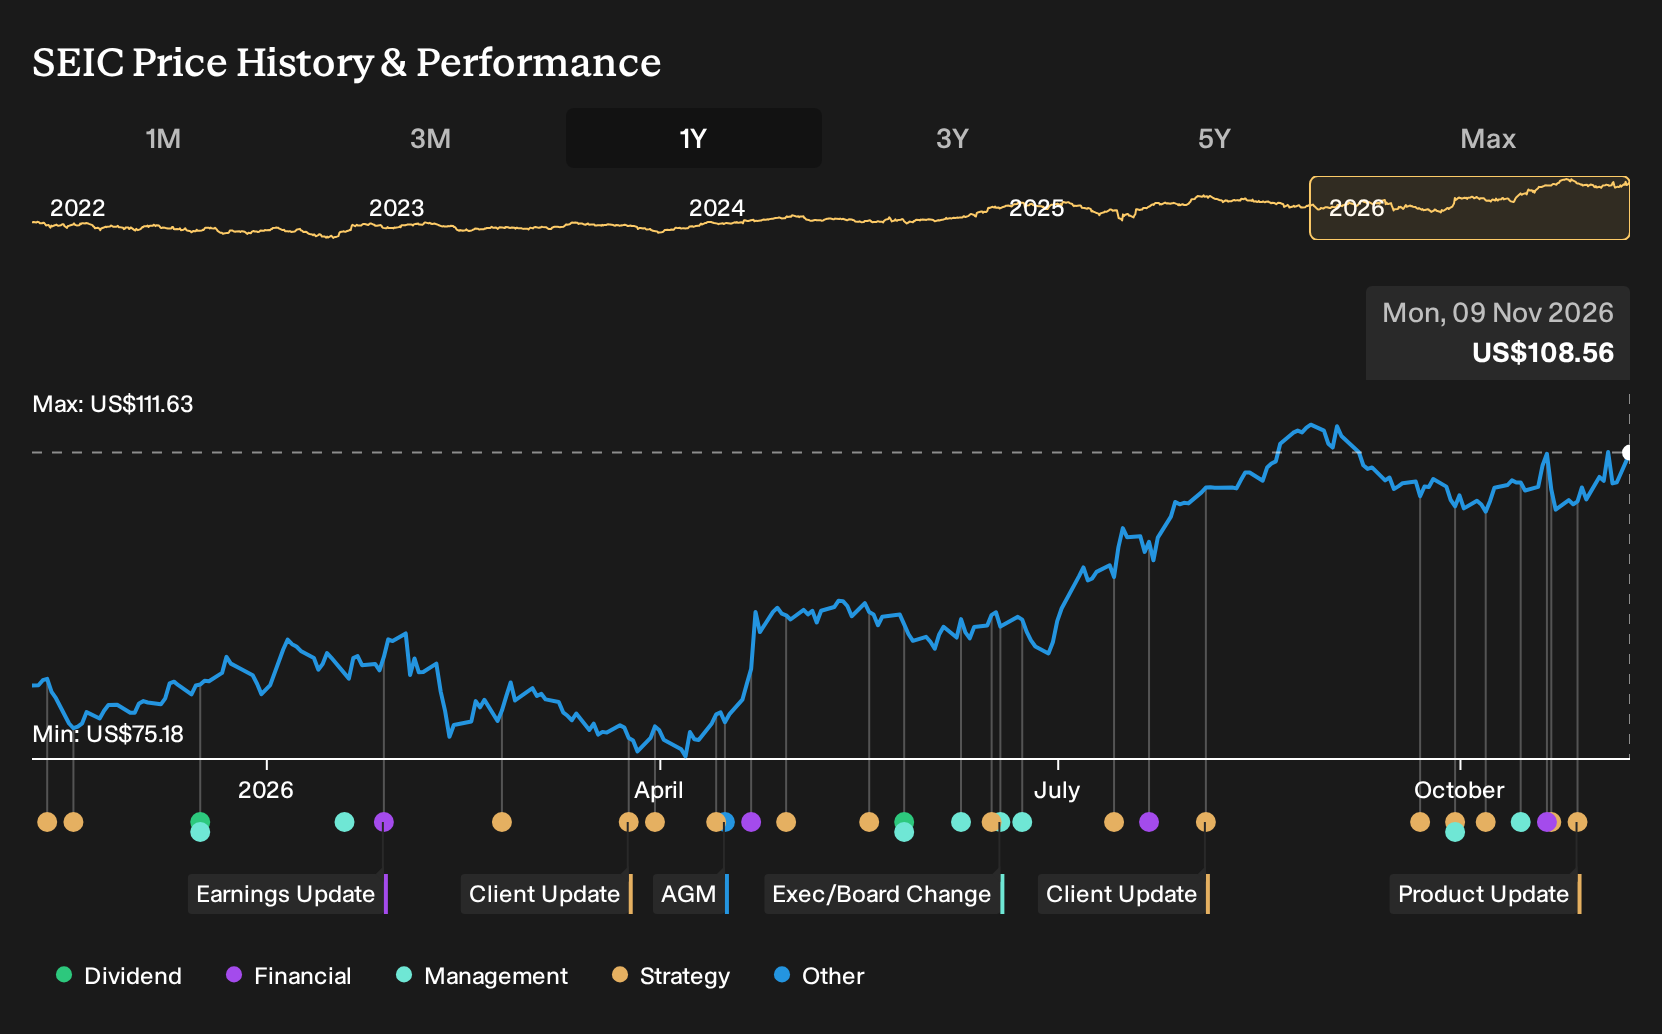
Uncover how SEI Investments' fair value indicates a 12% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the lowest ranked analysts lean hard into the risk that SEI Investments asset mix keeps shifting to lower fee ETFs and SMAs. They were only baking in 6.5% yearly revenue growth and about US$905.7m of earnings by 2029. The new charitable fund could nudge those expectations either way, so it makes sense to weigh both stories before deciding what you believe.
Explore 3 other SEI Investments fair value estimates, including one that suggests as much as 6% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your SEI Investments research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SEI Investments. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SEI Investments' overall financial health at a glance.
Looking For More Investment Ideas Beyond SEI Investments?
If the SEI Investments story has sharpened how you think about quality, capital allocation and platform economics, it can help to apply the same lens across a broader watchlist using the Simply Wall St Screener.
- For investors who care most about balance sheet strength and business resilience, start with a hand picked 30 resilient stocks with low risk scores that already clear our filters for lower risk profiles.
- If you are hunting for potential mispricing opportunities with solid fundamentals, scan a curated 33 high quality undervalued stocks that combine quality metrics with a valuation tilt.
- If you prefer to focus on businesses that fly under the radar yet have robust financial traits, then shortlist ideas from a targeted 19 high quality undiscovered gems that may warrant a closer look.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com