


If you only glanced at headlines about Deutsche Lufthansa cutting 20,000 flights, shutting CityLine and wrestling with pilot strikes and soaring jet fuel costs, the past year might look like a write off. Holding Deutsche Lufthansa over the past year would have returned 20.2%, including dividends. If you had been deciding on 9 November 2025, before the TAP and ITA deals progressed and Q3 2026 margins were on record, what exactly would you have needed to believe about this group’s capacity to absorb higher costs and still grow earnings?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
Deutsche Lufthansa has already moved. See which of 202 high quality undervalued stocks still trade below our estimates.
The Two Stories Investors Had To Choose Between On Deutsche Lufthansa
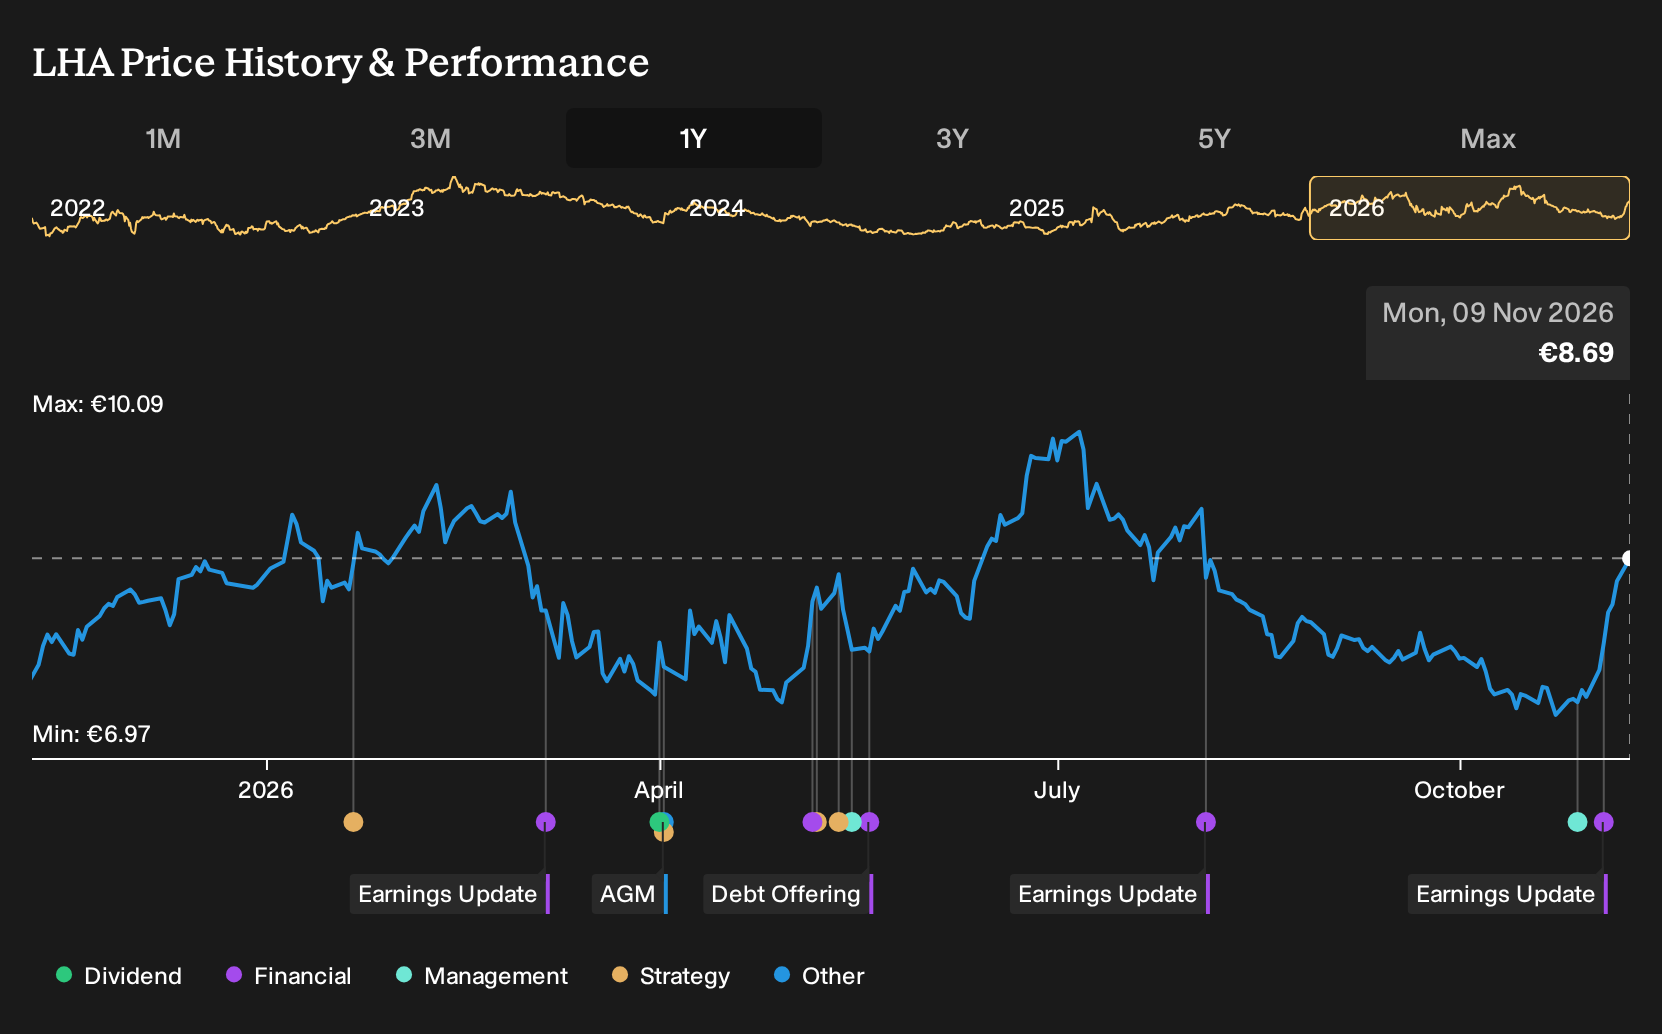
The shares cost €7.27 at the start of the period, and anyone looking at Deutsche Lufthansa then had to decide which earnings path felt more realistic.
One bullish narrative saw Fair Value at €7.65, about 5% above the start price. This was based on revenue rising 3.9% a year, profit margin settling at 4.2%, and the group reaching a 6.5x future P/E.
A bearish story put Fair Value at €5, 31% below the start price. This view relied on revenue growth of 3.1% and margin compression toward 2.8% as rising EU costs reduced profitability.
What The Results Changed For Deutsche Lufthansa
The clearest new fact was Deutsche Lufthansa’s Q3 2026 net margin of 10.3% on €12,240 million of revenue and €1,257 million of net income. That profitability level challenged both the bull case’s 4.2% margin assumption and the bear case’s 2.8% view, even as fuel cost headlines and flight cuts kept the cautious story alive. Overall, the evidence cut both ways.
The key assumption here was margin resilience under higher fuel and regulatory costs. For any other airline, you would track reported net margin against earlier forecasts and check whether acquisitions and cost cuts offset those external pressures.
What Today's Deutsche Lufthansa Price Already Assumes
Deutsche Lufthansa now trades at €8.69, with this bearish analyst Narrative on Simply Wall St placing its Fair Value below that level based on its own modelling. The Narrative focuses on how fuel costs, labour disputes and integration work around TAP and ITA could strain profitability.
Anyone paying €8.69 today is effectively assuming the airline converts fleet renewal and premium cabins into a lasting margin lift. The open question is how the fuel and labour risks flagged in the Narrative affect the odds that this margin story actually holds.
"The current valuation implies that Deutsche Lufthansa shares already price in successful execution on fuel hedging, integration of ITA and other growth projects, so there is limited room for disappointment on earnings delivery. What Deutsche Lufthansa Does: Deutsche Lufthansa operates an aviation business that sells passenger flights, airfreight and logistics services, aircraft maintenance, repair and overhaul services, training, and IT solutions to travelers, cargo customers, aircraft operators, governments, armed forces, and other corporate clients worldwide."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 30% below our estimate - uses a unified technology platform to expand adviser-led and self-directed investment flows.
- Company 2 - 38% below our estimate - wins specialised science consulting mandates combining failure analysis, regulatory insight and AI-enabled projects.
- Company 3 - 40% below our estimate - leans on recent supply chain disruption to reshape expectations for peripherals and collaboration hardware demand.
Three companies from the same screener. Open all 194 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com