


- On October 29, 2026, Tanabe Pharma announced an exclusive sublicense granting Nippon Shinyaku rights to commercialize loncastuximab tesirine-lpyl (MT-2111) in Japan for relapsed or refractory diffuse large B-cell lymphoma after at least two prior systemic therapies.
- The arrangement adds a first-in-class CD19-directed antibody drug conjugate to Nippon Shinyaku's oncology lineup, in connection with a marketing application in Japan supported by Japanese and overseas clinical data.
- This article examines how Nippon Shinyaku's investment narrative is influenced by gaining exclusive Japanese commercialization rights for MT-2111.
What Is Nippon Shinyaku's Investment Narrative?
Nippon Shinyaku’s appeal today rests on a simple belief. You need to think this is a disciplined, cash generative pharma player that can refresh its portfolio fast enough to offset pressure on earnings, while using a relatively low P/E of 7.3x and a 3.6% dividend yield as a cushion. The loncastuximab tesirine sublicense fits that story, because it leans into hematology where the group already operates, without taking on early stage development risk or heavy upfront capital build out.
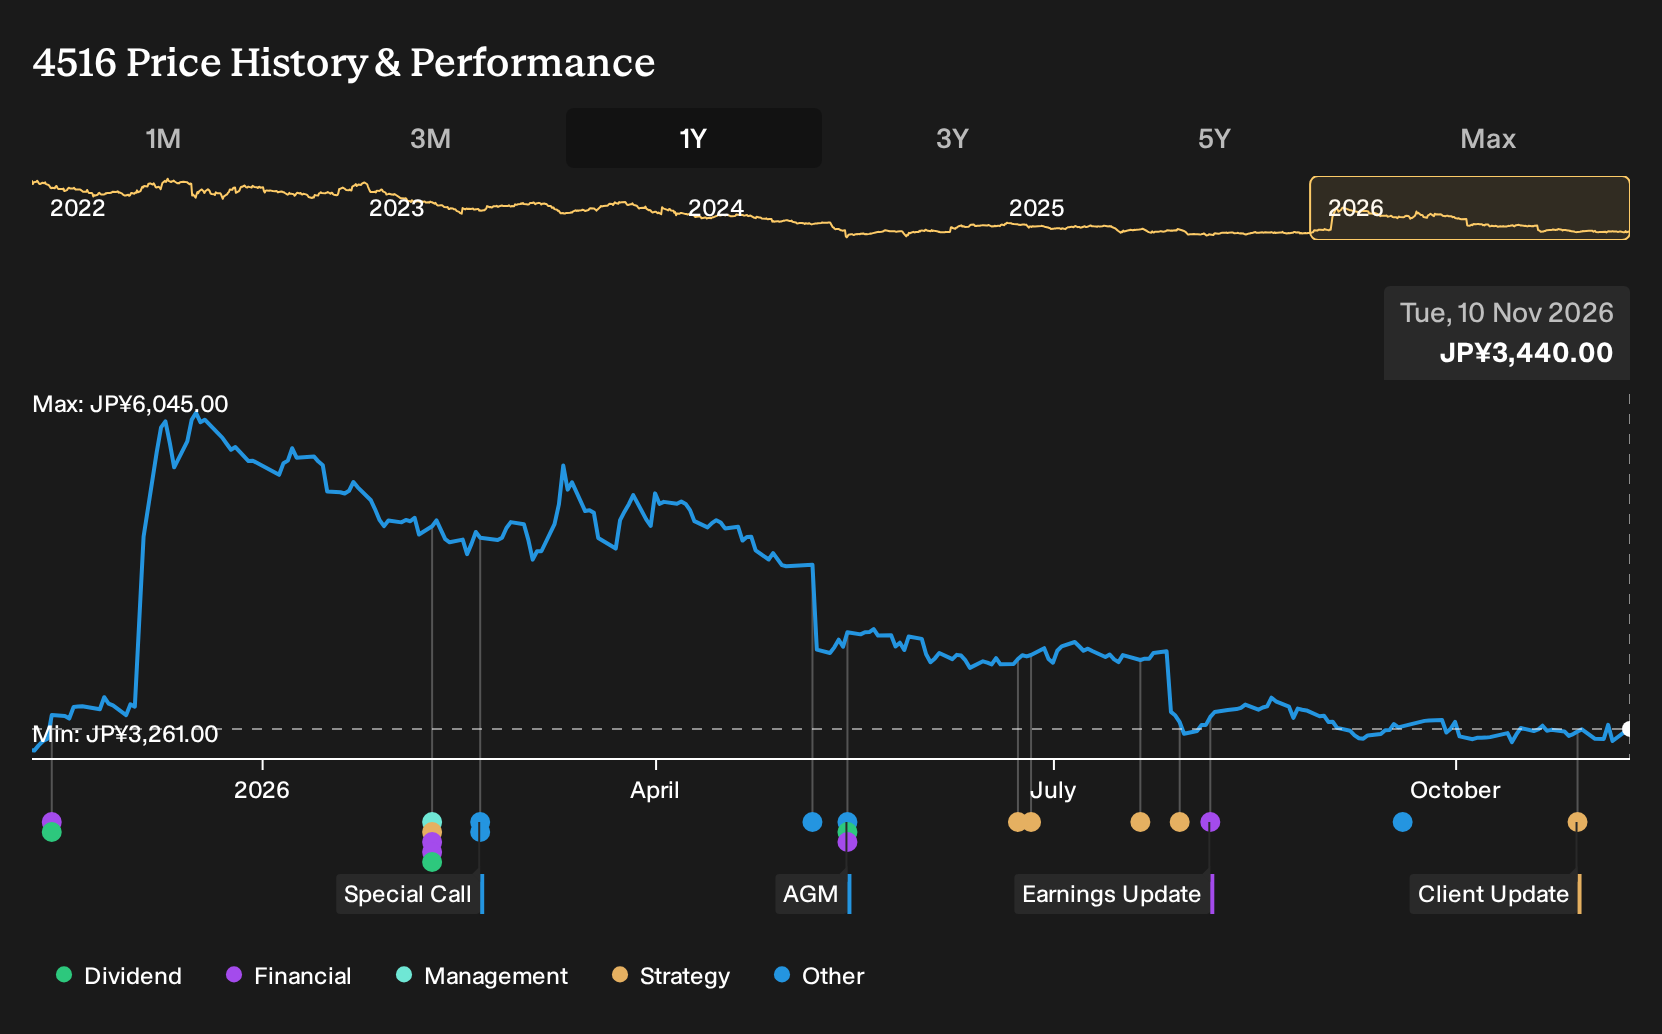
The challenge is timing. Earnings are forecast to decline over the next three years and recent net income already moved lower, so near term catalysts are more about execution on launches and defending pricing than blue sky growth. MT-2111 could support the oncology narrative if commercialization in Japan scales, yet it lands against forecasts of revenue contraction and a share price that has still fallen about 38% year to date. This keeps the burden of proof squarely on management delivery rather than on story alone.
That said, the one thing that can still unsettle the Nippon Shinyaku thesis is the way...
There's only one way to know the right time to buy, sell or hold Nippon Shinyaku. Head to Simply Wall St's company report for the latest analysis of Nippon Shinyaku's Fair Value.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Nippon Shinyaku research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Nippon Shinyaku. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Nippon Shinyaku's overall financial health at a glance.
Looking for more Nippon Shinyaku sized ideas?
If you want to round out your watchlist beyond Nippon Shinyaku, the Simply Wall St Screener can help you quickly filter for other stocks that fit your risk profile and income goals.
- For investors who care most about steady income, start with companies offering robust payout profiles by scanning 27 dividend fortresses and see which could complement a healthcare heavy portfolio.
- If capital preservation matters more than chasing every headline, focus on businesses with stronger balance sheets using the list of solid balance sheet and fundamentals (23 results) to find candidates that may handle stress better.
- When you are hunting for potential future leaders before the crowd, use the 76 high quality undiscovered gems to spot lesser known stocks with solid fundamentals that might be worth deeper research.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com