


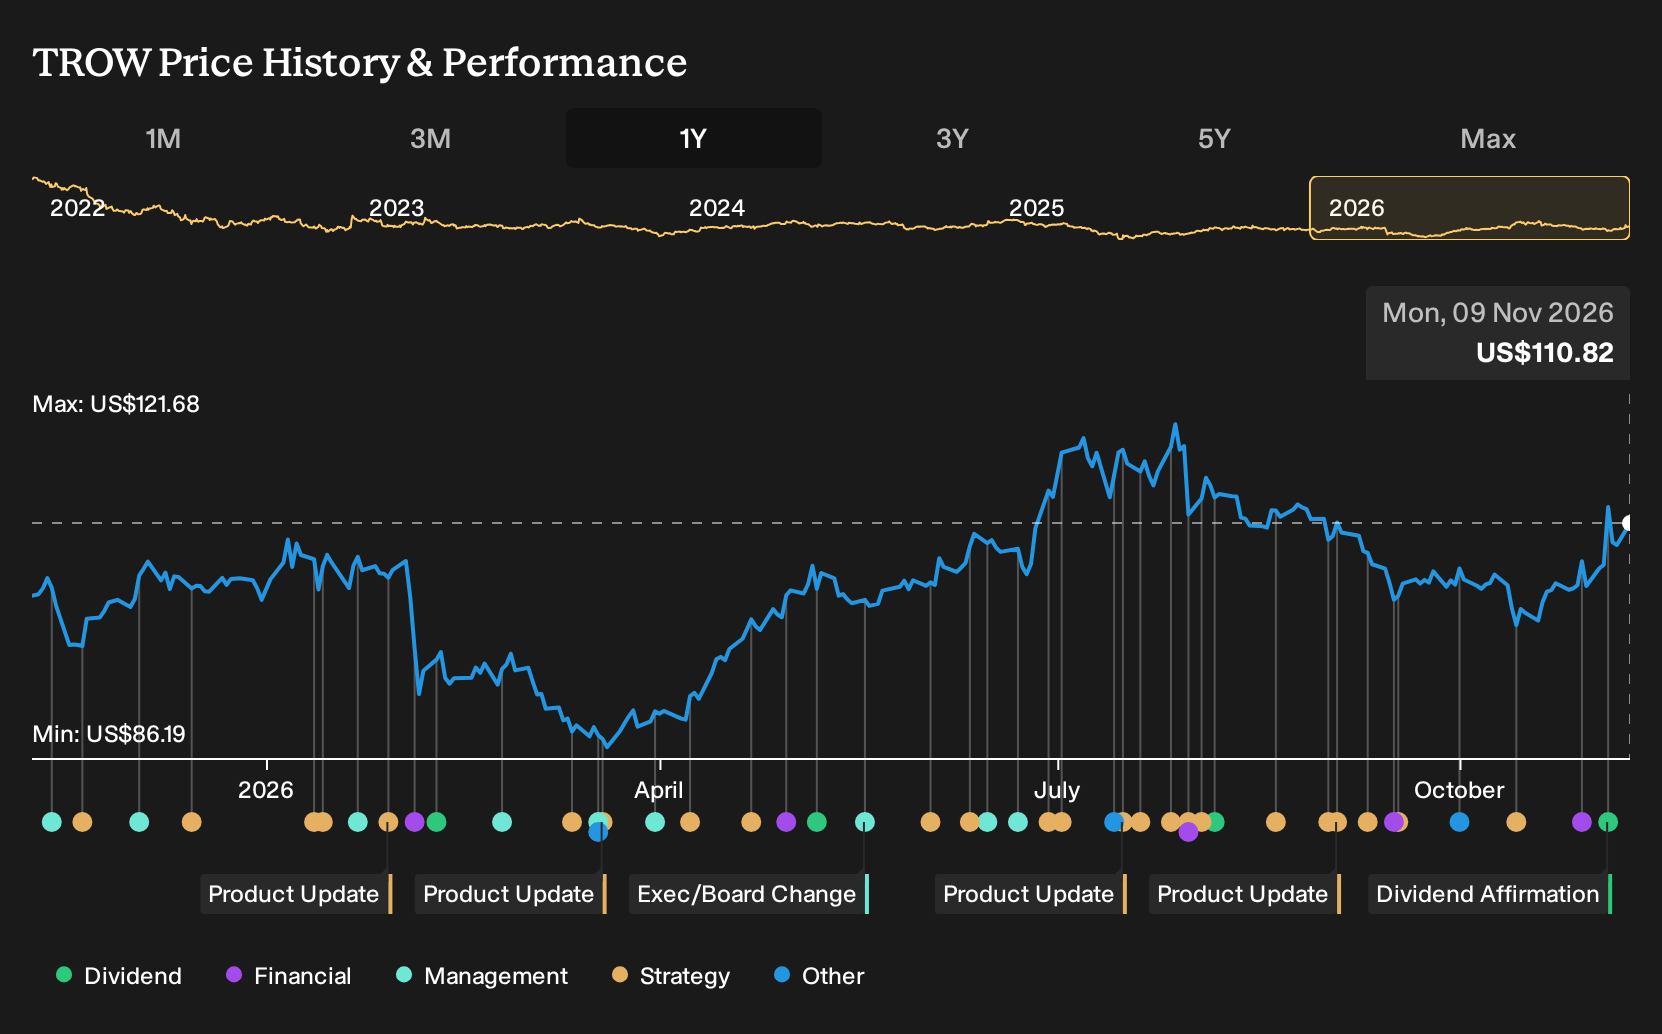
- T. Rowe Price Group reported third quarter 2026 revenue of US$2,004.9 million and net income of US$612.3 million, alongside a declared quarterly dividend of US$1.30 per share payable on December 29, 2026.
- The latest figures show higher revenue for both the quarter and the first nine months of 2026, while earnings per share moved differently over these periods. This highlights how product mix, fee levels, and costs shape T. Rowe Price Group's profitability.
- We will look at how T. Rowe Price Group's recent earnings mix and maintained dividend policy interact with its broader investment narrative.
Scan how T. Rowe Price Group's latest dividend and earnings profile compares with other income focused opportunities by reviewing our curated 6 dividend fortresses list.
T. Rowe Price Group Investment Narrative Recap
To own T. Rowe Price Group, you need to be comfortable with an asset manager in transition. The analyst consensus Narrative on Simply Wall St leans on retirement assets, ETFs, SMAs, and alternatives offsetting pressure from active mutual fund outflows, lower fee rates, and rising costs. The latest quarter shows that revenue and earnings can move differently as mix, fee levels, and expenses shift.
In the short term, the key swing factor is whether net outflows and fee compression ease enough for modest margin improvement to show through. Recent earnings do not appear to change that catalyst in a major way. The main operational risk remains persistent outflows from higher fee strategies while expenses grow in the mid single digit range.
The recent quarterly earnings release is the most relevant update. Revenue of US$2,004.9 million for the third quarter of 2026 and net income of US$612.3 million sit alongside softer quarterly EPS than a year earlier, while nine month EPS is higher. That mix lines up with a business leaning more on diversified product lines with different economics.
For readers, the question is whether the product expansion in ETFs, SMAs, retirement offerings, and alternatives can keep revenue broadly stable while costs rise 4% to 7% in 2026. If that balance holds, it supports the narrative that T. Rowe Price Group can fund its dividend and ongoing investments, even if top line growth expectations stay muted.
T. Rowe Price Group's current earnings are about US$2.2b, with analysts expecting consensus earnings of US$2.3b by 2029, which implies an increase of roughly US$0.1b. That projection sits alongside a forecast revenue figure of US$7.6b in 2029 and an assumption that revenue remains fairly flat over the next few years.
Uncover why T. Rowe Price Group's fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
Some of the most optimistic analysts frame T. Rowe Price Group as an earnings growth story tied to faster expansion in ETFs and alternatives, rather than focusing solely on containing active fund outflows. Before this dividend affirmation and quarterly update, that group was estimating revenue of about US$8.5b and earnings of roughly US$2.5b by 2029, a level that was higher than consensus. You can use this range of expectations to consider where you personally sit on the risk and reward spectrum, and how fresh results might eventually influence those views.
Explore 3 other T. Rowe Price Group fair value estimates, including one that suggests potential upside of up to 69% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your T. Rowe Price Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for T. Rowe Price Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate T. Rowe Price Group's overall financial health at a glance.
Looking for more investment ideas beyond T. Rowe Price Group?
If T. Rowe Price Group fits part of what you want but not the whole picture, it can help to line it up against other companies with different income, valuation, and risk profiles using the Simply Wall St Screener.
- For investors who care most about balance sheet resilience and cleaner fundamentals, review our curated list of solid balance sheet and fundamentals (25 results) to see which businesses meet that test.
- If your priority is cushioning volatility with cash returns, scan income opportunities through the 6 dividend fortresses and see how they compare with T. Rowe Price Group's payout profile.
- When you want potential mispricings backed by underlying quality rather than pure speculation, sort through the 19 high quality undiscovered gems and build a broader watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com