


DCC Energy (LSE:DCC) just posted half year results to 30 September 2026, reporting sales of £7,288.17m alongside a net loss of £269.17m, putting profitability firmly in focus for investors.
Despite the half year loss, DCC Energy’s share price has climbed strongly, with a year to date share price return of 42.17% and a 1 year total shareholder return of 40.66%. This suggests investors have been pricing in a more positive long term story, even as recent filings show increased interest from large institutional holders and derivative traders.
Scan how DCC Energy stacks up against other companies investors are watching for resilient balance sheets and fundamentals with our hand picked list of solid balance sheet and fundamentals (9 results) today.
DCC Energy has a rising share price set against a growing loss in the latest half year. Are investors backing the underlying business, or has sentiment simply sprinted ahead of what the valuation supports?
Most Popular Narrative: 1% Overvalued
DCC Energy closed at £64.60, slightly above the analyst consensus Narrative fair value of £64.20. This frames the latest move in the share price as almost exactly in line with the analyst consensus Narrative on Simply Wall St that aggregates earnings and cash flow expectations.
Management is progressing a long term plan to increase exposure to cleaner energy solutions such as liquid gas, biofuels, solar, storage and optimization. These are tied to customer demand for secure and lower carbon energy and could gradually shift the revenue mix toward higher value services and potentially support margin resilience.
See why 30 investors see DCC Energy as 1% overvalued.
Result: Fair Value of £64.20 (ABOUT RIGHT)
Still, weak Energy Services profitability and softer Energy Products volumes could upset the current DCC Energy narrative if these pressures persist or deepen.
Find out about the key risks to this DCC Energy narrative.
Another View: What Multiples Say About DCC Energy
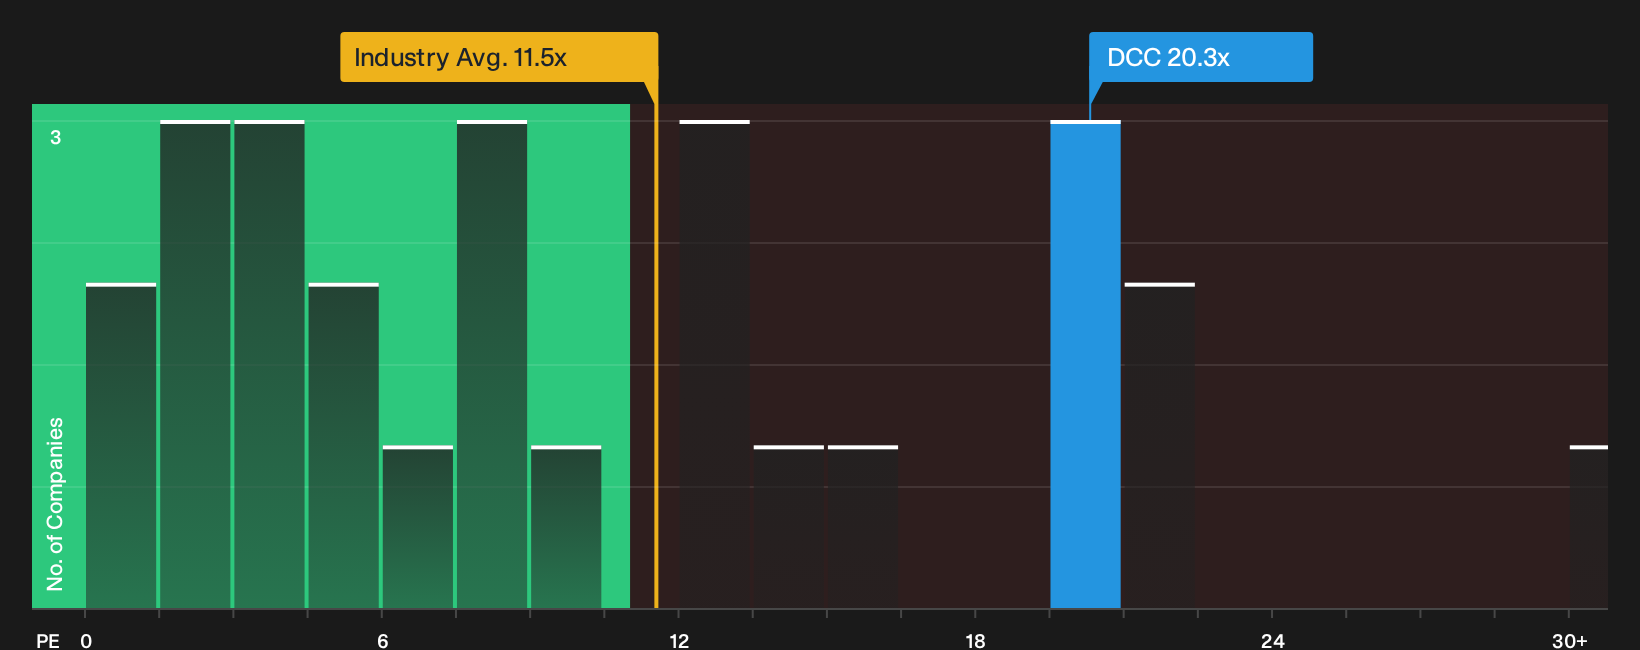
On earnings multiples, DCC Energy trades on a P/E of 20.3x. That is above the peer average of 19.2x and well ahead of the wider European Oil and Gas group at 11.5x, even though the fair ratio sits higher at 24.4x. This hints at both upside room and valuation risk if sentiment cools.
For anyone weighing these mixed signals against their own expectations, it is worth stress testing whether this richer P/E really matches the quality and growth profile you see for the next few years. Consider whether the market has already done most of the heavy lifting on the rerating, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed tone around DCC Energy leaves you unsure, act promptly: review the underlying numbers and test your own thesis against the 3 key rewards.
Looking for more investment ideas beyond DCC Energy?
Do not stop with a single stock. Use the Simply Wall St Screener to pressure test your next ideas and keep your watchlist one step ahead.
- Target quality at a discount by scanning a curated set of 16 high quality undervalued stocks that pair strong fundamentals with prices that may not fully reflect them yet.
- Prioritise resilience by checking a 4 resilient stocks with low risk scores that tilts toward businesses with sturdier financial profiles and fewer red flags.
- Hunt for underfollowed potential by reviewing a 5 high quality undiscovered gems that many investors may not be watching closely yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com