


The Zhitong Finance App learned that the overall and core CPI monthly rates of the US in October were higher than market expectations, indicating that price pressure is still high, strengthening the reason for the Federal Reserve to continue to raise interest rates. According to data released by the US Department of Labor (BLS) on Tuesday, the US CPI rose 0.4% month-on-month, higher than market expectations of 0.3%, and the previous value was 0.6%; excluding volatile projects such as energy and food, the increase in core CPI was 0.3% month-on-month, higher than market expectations of 0.2%, and the previous value was 0.3% (there was no year-on-year data for the CPI and core CPI in October last year).
Looking at the breakdown, according to the official BLS data sheet, the month-on-month increase in energy prices in October narrowed sharply from 5.2% in September to 0.7%, with gasoline falling back from 9.1% to 1.0%. However, food prices changed from being flat month-on-month in September to rising 0.5% month-on-month. Within core inflation, housing rose 0.3% month-on-month (owners' equivalent rents increased 0.3% month-on-month, rents increased 0.2% month-on-month), transportation services rose 0.8% month-on-month, motor vehicle insurance rose 0.7% month-on-month, airline tickets rose 0.4% month-on-month; used car prices fell 1.2% month-on-month.
After the release of the US CPI data for October, the market raised its bet on the Fed's interest rate hike. In addition to the almost 100% pricing that the Federal Reserve will raise interest rates in December, the market has raised the bet that the Fed will raise interest rates by 50 basis points next month, and further increased the bet that the Fed will raise interest rates at least twice by mid-2027.
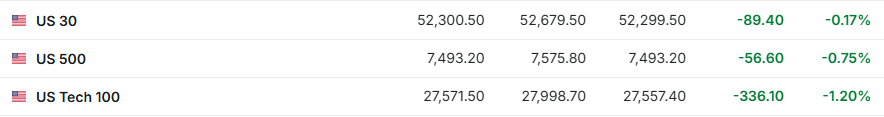
In terms of financial market reactions, US bond yields rose — two-year US Treasury yields, which are sensitive to monetary policy, rose 16.54 basis points to 4.715%; 10-year US Treasury yields rose 9.03 basis points to 4.952%. The US dollar index DXY rose nearly 30 points in the short term to 101.97. Futures on the three major US stock indexes fell, Dow futures fell 0.17%, S&P 500 futures fell 0.75%, and Nasdaq 100 futures fell 1.20%. The intraday decline of spot gold widened to 2% to 4043.4 US dollars/ounce; the decline in spot silver extended to 3% to $51.75 per ounce.
It is worth mentioning that this CPI data is the last inflation data before the Federal Reserve's December 8-9 interest rate meeting (the November CPI is scheduled to be announced on December 10, the day after the resolution, and the year-on-year caliber will be restored at that time). In October, which was announced last week, 165,000 new jobs were added, far exceeding expectations. The unemployment rate fell to 4.1%. Combined with the current core inflation not cooling down, the market focus has turned to whether the December rate hike was 25 or 50 basis points.
More importantly, this CPI data may also have hit the threshold for a sharp interest rate hike just mentioned by Federal Reserve Governor Waller on Tuesday. Waller said on Tuesday that he supports raising interest rates in December and warned that if inflation continues to accelerate, he will support a 50 basis point increase to preserve the Federal Reserve's credibility.
Waller said that despite a strong economy and a stable labor market, inflation is still too high. Waller said, “If inflation improves month-on-month in October, as I expected, I am inclined to support raising the policy interest rate by 25 basis points.” “But if the October CPI data released later today is similar to the previous two months' readings — core CPI inflation is around 0.3% or higher — then stronger policy action may be needed. In this case, I think a 50 basis point increase in interest rates should be considered at the December meeting.” Waller's blunt statement is the strongest signal from Federal Reserve officials so far — not only do policymakers need to raise interest rates in December, but the rate increase may exceed market expectations by 25 basis points.