


- Becton Dickinson reported past fourth quarter 2026 sales of US$5,274 million and net income of US$696 million, along with full year revenue of US$19,457 million and updated guidance for low single digit GAAP revenue growth in fiscal 2027.
- Alongside this result, the business combined a modest dividend increase and a new 10,000,000 share repurchase authorization with stronger quarterly earnings per share, tightening the focus on capital returns as well as operating performance.
- Attention now turns to how Becton Dickinson's stronger quarterly earnings and new capital return plans could influence the broader investment narrative.
Scan how Becton Dickinson's latest earnings, dividend bump, and buyback plan compare with other mature healthcare stocks in the 30 resilient stocks with low risk scores that prioritize resilience and balance sheet strength.
Becton Dickinson Investment Narrative Recap
To stay on board with Becton Dickinson, you need to be comfortable with a slow and steady medtech story where execution and product quality really matter. The analyst consensus Narrative on Simply Wall St leans on productivity gains and higher margin platforms, and the strong fourth quarter earnings give that story a bit more support in the near term.
The key short term catalyst is whether core platforms can offset expected revenue headwinds from the Alaris replacement cycle and weaker China, while keeping the BD Excellence productivity engine intact. The biggest near term risk is further product quality or legal setbacks, highlighted by the recent PowerPort verdict and ongoing infection prevention issues.
The most relevant update for this story is Becton Dickinson's new guidance for low single digit GAAP revenue growth in fiscal 2027. That outlook, paired with a full year sales figure of US$19.457b, frames expectations around a measured growth path rather than a step change in demand. This matters if you are tracking execution against the analyst consensus Narrative.
Layered on top of that guidance, the 1.0% dividend increase and the new 10,000,000 share buyback authorization signal that management is comfortable committing more cash to shareholders while funding new launches like the BD Liverty TIPS Stent Graft. For catalysts, the question is whether ongoing product rollouts and the BD Excellence program can offset legal, pricing and Alaris headwinds without stretching a balance sheet that already carries a high level of debt.
Becton Dickinson Earnings Outlook And Valuation Anchors
Becton Dickinson's narrative projects US$21.7b revenue and US$2.8b earnings by 2029. This rests on analysts assuming 3.7% yearly revenue growth and earnings roughly doubling from US$1.4b today to the US$2.8b consensus forecast.
Analysts are effectively tying the investment story to two levers. The first is a gradual compound in sales at 3.7% a year as medtech platforms, biologic delivery work and diagnostic launches scale over time. The second is a profitability reset, with profit margins that are expected to move from 7.3% today toward 12.8% in three years as the BD Excellence program and a richer mix of higher margin platforms flow through the income statement.
On those numbers, the implied earnings path is quite clear. Consensus calls for profit to rise from US$1.4b today to US$2.8b by 2029, with the spread between the bullish US$3.2b view and the more cautious US$2.3b estimate highlighting how differently analysts weigh execution and risk around recalls, legal outcomes and pricing pressure.
The valuation overlay builds directly from that earnings bridge. To line up with the current analyst targets, Becton Dickinson would be trading on a P/E of 24.3x those 2029 earnings, compared with about 40.8x today. That P/E would sit slightly below the quoted 25.7x for the US medical equipment peer group. This implies the stock is being modeled as a solid but not aggressively priced medtech compounder once margin expansion and capital returns are further along.
Revenue assumptions tell a similar story. For the analyst targets to make sense, investors would need to be comfortable with Becton Dickinson generating US$21.7b of sales and US$2.8b of earnings in 2029. That profile, combined with an 8.0% to 8.01% discount rate, is being used to frame a consensus price target of US$224 per share, with a range from US$165 on the cautious end to US$242 on the more optimistic side.
One subtle but important input is capital structure. Forecasts build in a 4.37% annual decline in the share count over the next three years, which lines up with the new 10,000,000 share repurchase authorization and prior buybacks. Fewer shares outstanding can lift earnings per share even if total profit grows more slowly, so readers tracking Becton Dickinson need to separate per share metrics from absolute earnings when judging how much of the improvement is operational versus financial engineering.
Uncover why Becton Dickinson's fair value indicates a 4% potential upside to its current price that may not last much longer.
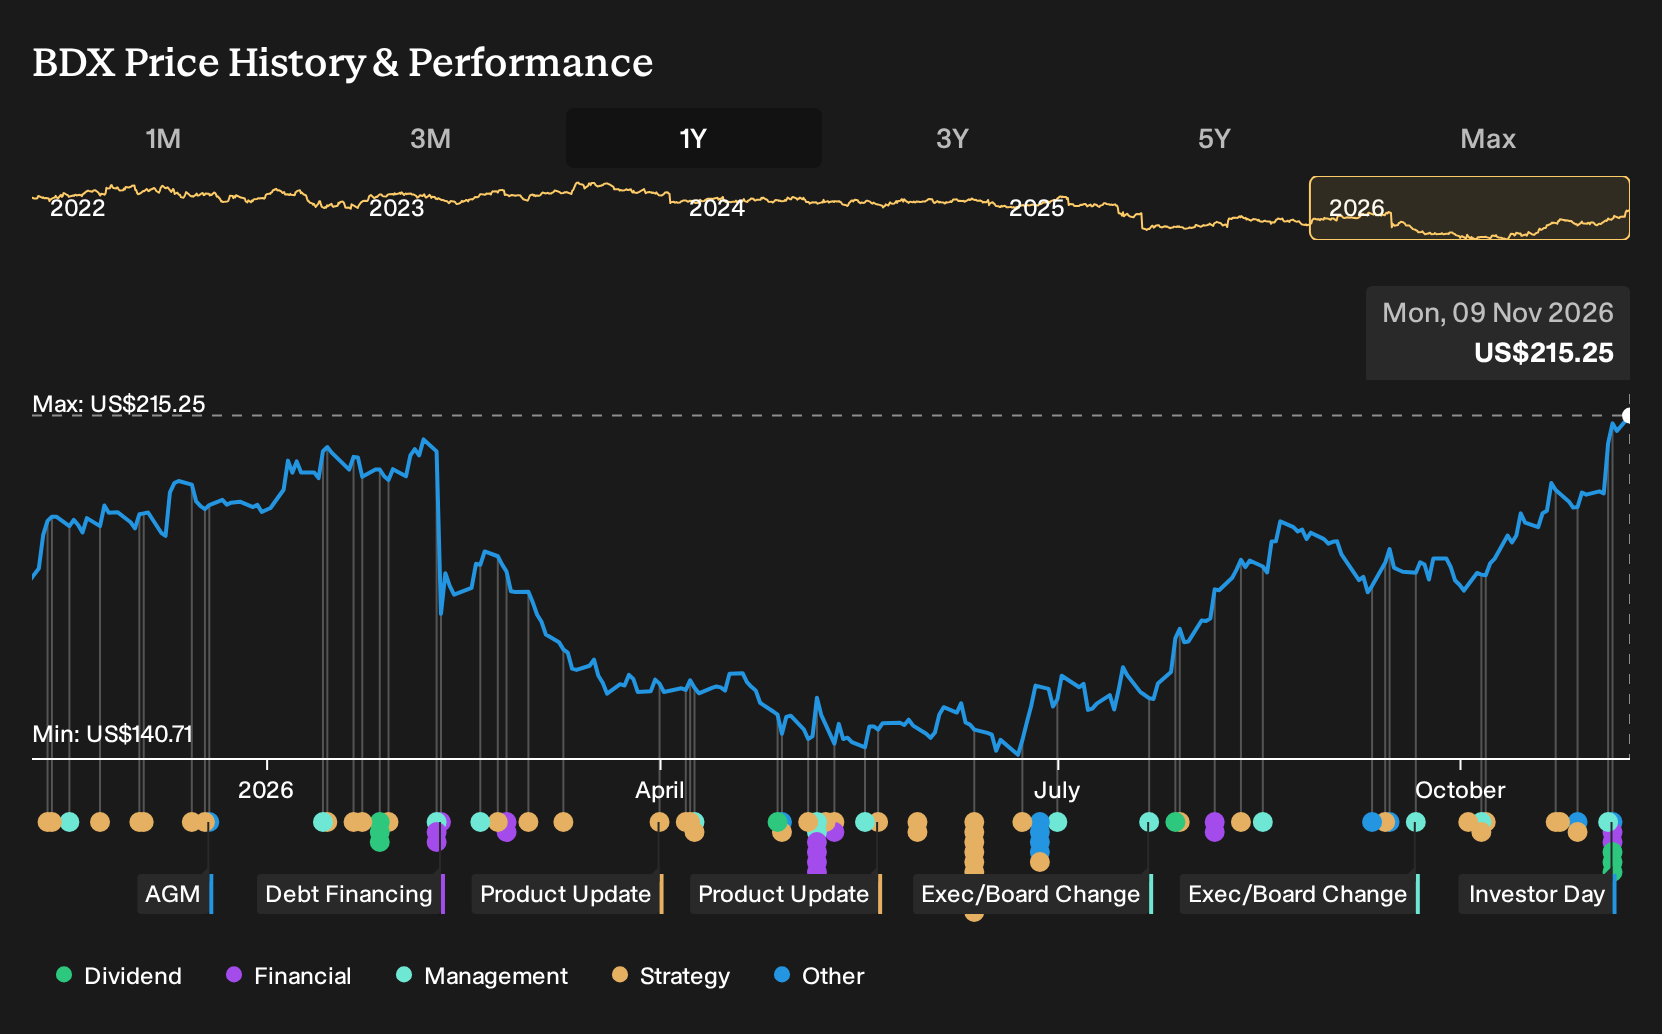
Exploring Other Perspectives
One alternate angle you might explore is the legal risk around PowerPort and other quality issues. The most cautious analysts, who were using about US$21.2b of 2029 revenue and US$2.3b of earnings before this quarter, effectively assume these headwinds keep biting. You now have fresh results and guidance, so it is worth comparing both stories yourself.
Explore 2 other Becton Dickinson fair value estimates, including one that suggests as much as 15% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Becton Dickinson research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Becton Dickinson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Becton Dickinson's overall financial health at a glance.
Looking for more Becton Dickinson style investment ideas?
If the Becton Dickinson story has sharpened your thinking about quality, income, and risk, use that same lens across the wider market. The Simply Wall St Screener helps you narrow the field quickly so you can focus on a short list of stocks that fit your own criteria rather than trying to track everything at once.
- For investors who care most about capital strength and steadier profiles, start with a list of solid balance sheet and fundamentals (25 results) that may better match a cautious approach to downside risk.
- If income is your main priority, scan for higher yielding opportunities built on more resilient cash flows with a focus on 6 dividend fortresses that aim to combine payout potential with staying power.
- Readers hunting for something earlier in its story can filter for smaller companies with stronger fundamentals using a 19 high quality undiscovered gems that could add a different return profile alongside larger holdings.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com