


Shimano (TSE:7309) is back in focus after reporting nine month 2026 earnings and lifting its full year guidance, pointing to recovering demand, currency tailwinds, and easing inventory pressures in key regions.
The upgraded guidance has arrived alongside a sharp swing in sentiment around Shimano, with the 30 day share price return of 23.70% and year to date share price return of 29.83% suggesting momentum has picked up as investors reassess earnings resilience. That renewed optimism sits against a mixed longer record, with a 1 year total shareholder return of 39.33% contrasting with a 5 year total shareholder return that is down 26.08%, which hints that some holders are only now seeing a recovery take shape.
Capitalize on Shimano’s rebound by scanning a curated group of 20 high quality undervalued stocks that also pair earnings momentum with balance sheet strength.After a 30 day surge and a richer earnings outlook, the real tension around Shimano now is simple: Has the bulk of the rerating already played out, or does the current valuation still leave meaningful upside on the table?
Preferred P/E of 31.8x: Is it justified?
The market is attaching a P/E of 31.8x to Shimano at a last close of ¥21,895. This level lines up with a stock priced for solid earnings power rather than a deep value setup.
The P/E multiple compares the current share price to earnings per share and acts as a shorthand for how much investors are willing to pay for each unit of profit. For a business like Shimano, which generates earnings from bicycle components and fishing tackle, that ratio effectively reflects what the market thinks about the durability of its profit stream and the quality of those earnings.
Recent numbers give investors some support on the quality side. Earnings grew 13.3% over the past year, current net profit margins sit at 11.8% compared to 10.9% last year, and the business is flagged as having high quality earnings. Forecasts also point to earnings growth of 10.9% per year, which is faster than the 9.2% expected for the broader JP market, even though this pace is not classified as significant and comes after earnings declined by 23.9% per year over the past 5 years.
The issue for valuation is how much investors are paying for that profile. Shimano is described as expensive based on its P/E of 31.8x relative to the peer average of 22.9x, and expensive again compared with the JP Leisure industry average of 15.7x. The stock is also trading above an estimated fair P/E ratio of 19.9x, a level the market could eventually move towards if sentiment softens or earnings growth underwhelms what the current multiple implies.
Explore the SWS fair ratio for Shimano.
Result: Price-to-earnings of 31.8x (OVERVALUED)
Still, the story can break if demand softens again or if Shimano’s premium P/E multiple compresses quickly as investor enthusiasm cools.
Find out about the key risks to this Shimano narrative.
Another view on Shimano’s value
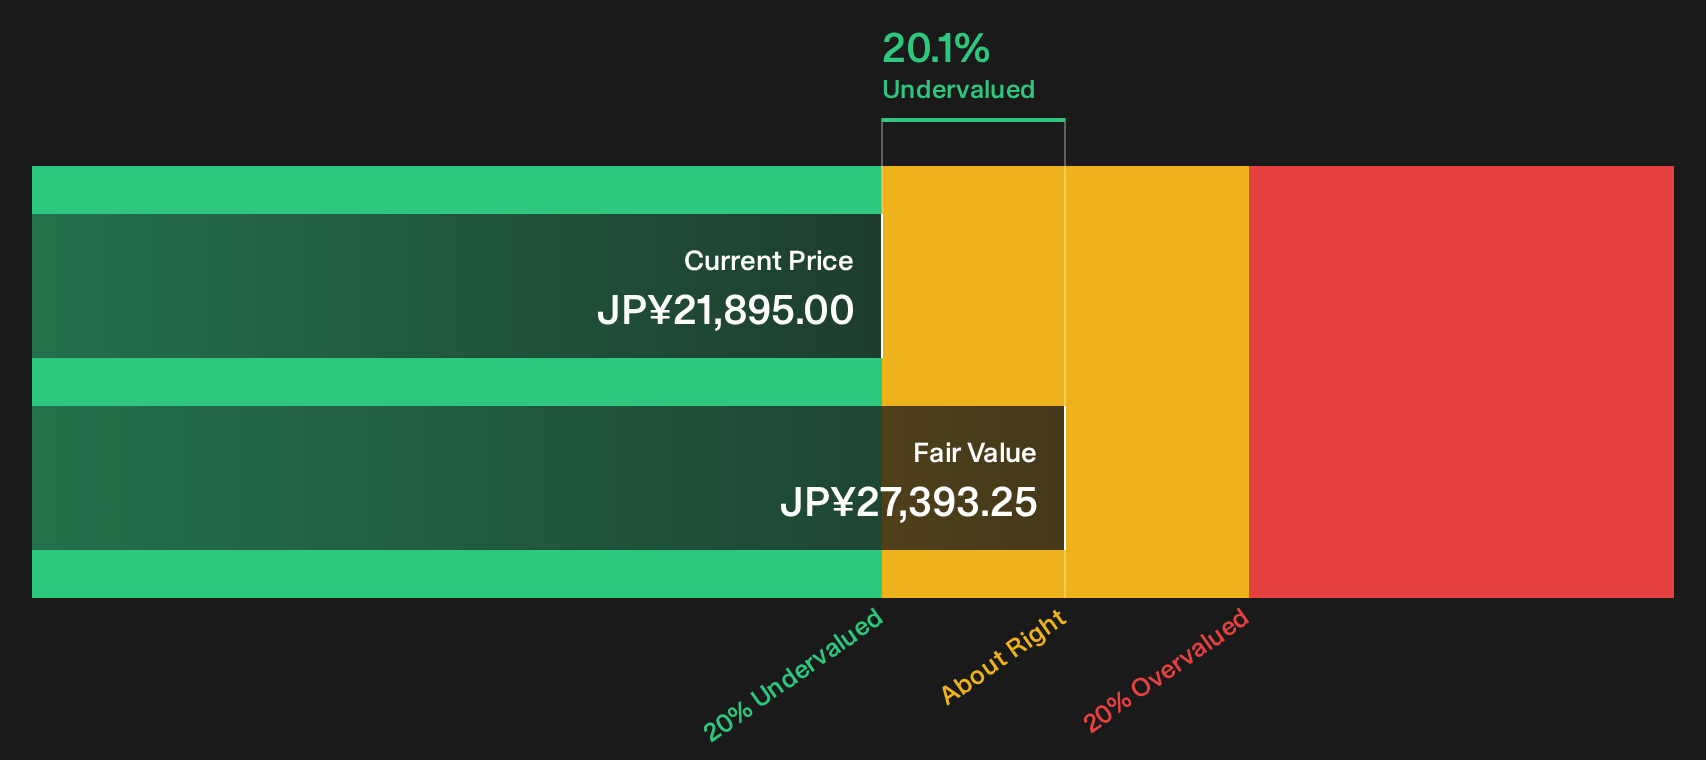
The P/E makes Shimano look expensive, yet the SWS DCF model points the other way. With the share price at ¥21,895 and the future cash flow value estimate at ¥27,393.25, the stock appears to be trading at a 20.1% discount on this framework. Which lens do you trust more when cash flows and sentiment pull in different directions?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shimano for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 20 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment this upbeat around Shimano, you should pressure test the numbers yourself and decide whether the optimism lines up with your risk appetite. To see what is drawing investors toward the positives in this story, review the 3 key rewards
Looking for more investment ideas beyond Shimano?
If Shimano has sharpened your focus on quality opportunities, do not stop here. Broader idea hunting can help you build a stronger, more resilient portfolio.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (23 results) that can help anchor the risk side of your portfolio.
- Hunt for strong yield potential with companies screened as 27 dividend fortresses that may support your income goals while you watch capital returns play out.
- Chase upside in underfollowed opportunities by reviewing a 76 high quality undiscovered gems where fundamentals, quality, and market attention are not yet aligned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com