


Lundin Gold (TSX:LUG) just reported record third quarter gold production of about 154,000 ounces, alongside higher sales and net income, as well as a reaffirmed 2026 output outlook that anchors the latest earnings story.
Lundin Gold’s latest earnings update landed alongside a sharp shift in trading. The share price is now about CA$101.15 after a 7 day share price return of 18.72% and a 90 day gain of 9.36%. This contrasts with a year to date decline of 9.57%, while longer term holders have seen total shareholder returns of 4.31% over 1 year and very large gains over 3 and 5 years. This suggests recent momentum is rebuilding after a softer stretch as investors weigh record output, reaffirmed production guidance, the latest dividend declaration and new exploration results against prior share price weakness.
Scan how Lundin Gold compares to a wider set of producers by checking our hand picked list of 34 elite gold producer stocks reacting to similar production and dividend catalysts.
After a move like this, Lundin Gold leaves you weighing fresh earnings strength and dividends against a richer share price. Does the current valuation still offer an appealing risk reward for new buyers?
Most Popular Narrative: 6% Overvalued
Lundin Gold’s last close at about CA$101.15 sits above the analyst consensus Narrative fair value of roughly CA$95.45, which is built using a 7.83% discount rate and detailed earnings and revenue forecasts in the analyst consensus Narrative on Simply Wall St.
The main thing that has to go right is that Lundin Gold sustains high margin production at Fruta del Norte and converts recent reserve additions and exploration success into a longer mine life despite single asset and Ecuador specific regulatory risks.
The current numbers imply the share price reflects a business with robust free cash flow, a net cash position, and generous dividends. The narrative views this as undervalued relative to the concentration and tax risks the market appears to be pricing in.
See why 44 investors see Lundin Gold as 6% overvalued.
Result: Fair Value of CA$95.45 (OVERVALUED)
Still, the Ecuador tax assessment and Lundin Gold’s reliance on a single asset at Fruta del Norte could quickly challenge the current overvaluation story.
Find out about the key risks to this Lundin Gold narrative.
Another View: SWS DCF Signals Underpricing
The analyst consensus Narrative calls Lundin Gold about 6% overvalued at CA$95.45, yet the Simply Wall St DCF model points the other way. On that cash flow view, Lundin Gold at CA$101.15 trades roughly 9.9% below an estimated future cash flow value of CA$112.23. Which lens do you trust more when cash returns and single asset risk pull in opposite directions?
Our DCF model is fully laid out so you can test the inputs for yourself, stress test the cash flows, and see how sensitive Lundin Gold’s valuation is to your own assumptions, not just the consensus view. Look into how the SWS DCF model arrives at its fair value.
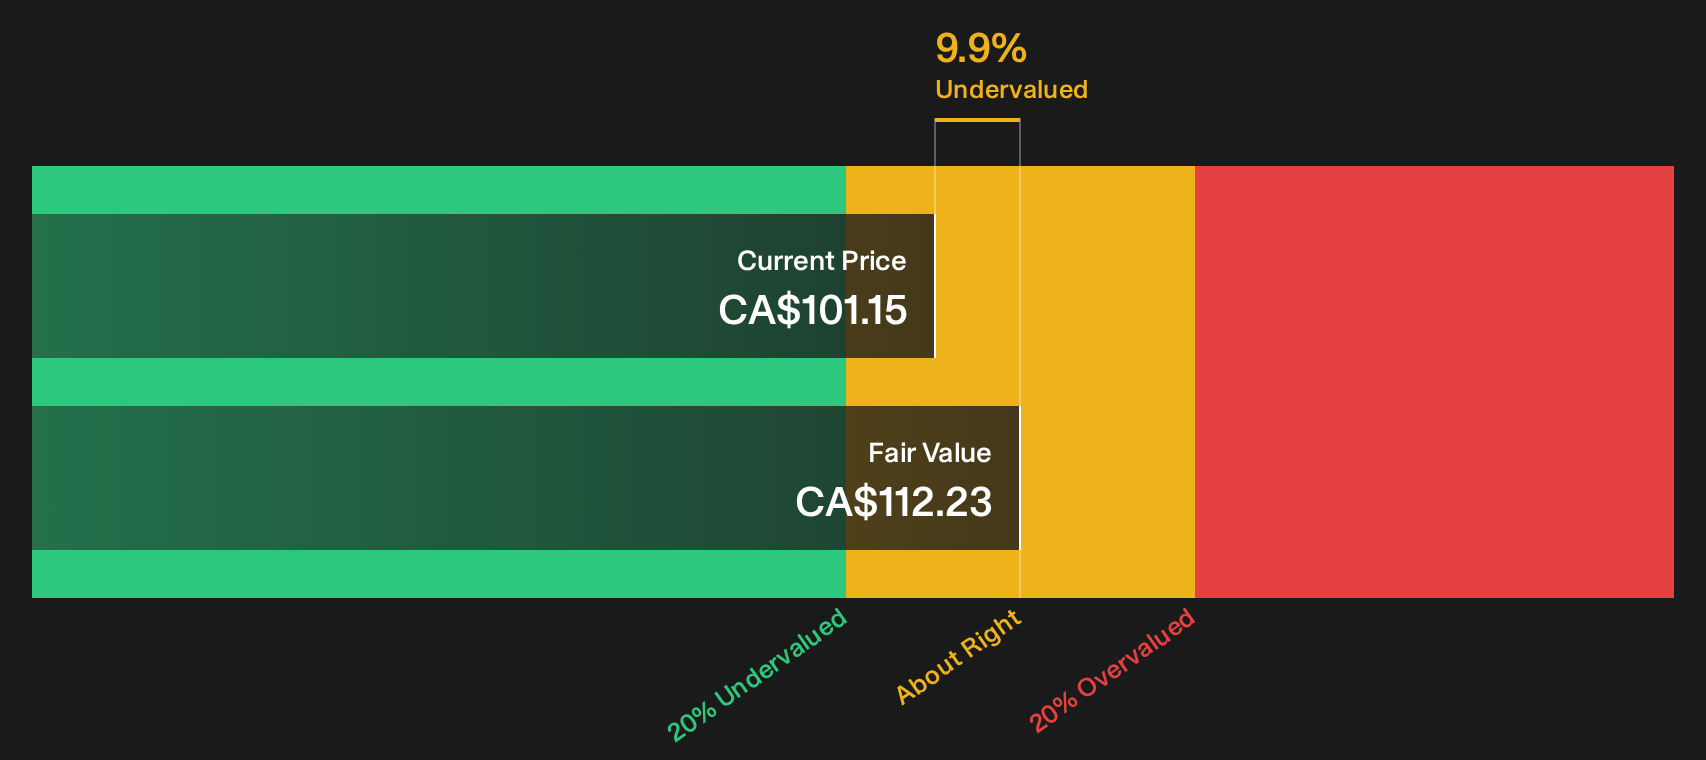
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Lundin Gold for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling conflicted by Lundin Gold’s mix of risks and rewards in this report is normal. Move quickly, review the data for yourself, and pressure test both sides of the thesis with the 3 key rewards and 2 important warning signs.
Hunting for more ideas beyond Lundin Gold?
If Lundin Gold has your attention, do not stop there. Use this move as a prompt to scan other opportunities that match the way you like to invest.
- Target quality at a discount by reviewing the 6 high quality undervalued stocks that combine solid fundamentals with pricing that has not caught up yet.
- Secure cash flow today by checking the 3 dividend fortresses that focus on higher yields supported by underlying business strength.
- Protect against shocks by researching the 9 resilient stocks with low risk scores that screen for resilient balance sheets and more stable risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com