


Q3 results and dividend update set the tone for Extendicare
Extendicare (TSX:EXE) just delivered third quarter and year to date results, highlighted by higher sales, earnings and adjusted EBITDA, alongside a reaffirmed monthly dividend and fresh expansion plans in long term care and home healthcare.
Investors have reacted quickly to the earnings jump and raised guidance, with the share price up 2.39% over the last day and a 7 day share price return of 5.68% placing Extendicare at CA$28.27. However, a 90 day share price decline of 10.85% contrasts with a strong year to date share price return of 34.11% and a 1 year total shareholder return of 78.51% that builds on multi year total shareholder returns above 4x.
Scan how Extendicare's momentum compares with other healthcare and income-focused opportunities by checking the hand picked 3 dividend fortresses that investors are watching right now.
Extendicare’s sharp bounce after a weak 90 day stretch could either reflect investors finally catching up to the stronger earnings profile, or a sentiment swing that has run ahead of the numbers.
Price-to-Earnings of 20.5x: Is it justified?
On simple earnings terms, Extendicare trades on a P/E of 20.5x, which sits below both its Canadian and wider North American healthcare peer averages.
The P/E ratio compares the share price to earnings per share and helps you see how much investors are paying for each dollar of profit. For a senior care operator like Extendicare, where revenue often comes from long term care contracts and home healthcare services, that earnings multiple becomes a shorthand for how the market is weighing its income reliability and growth runway.
EXE is described as good value versus both its direct peer group on 31.6x and the broader North American Healthcare industry on 24.6x. That gap suggests investors are paying a lower price for each dollar of earnings than they are for comparable healthcare stocks, which could indicate the market is applying a discount to Extendicare's higher debt levels or its funding mix, even as earnings quality is assessed as high.
Result: Price-to-Earnings of 20.5x (UNDERVALUED).
Still, rising long term care and home health care exposure leaves Extendicare sensitive to funding changes and labour costs. This could pressure earnings and sentiment.
Find out about the key risks to this Extendicare narrative.
Another view on Extendicare's valuation
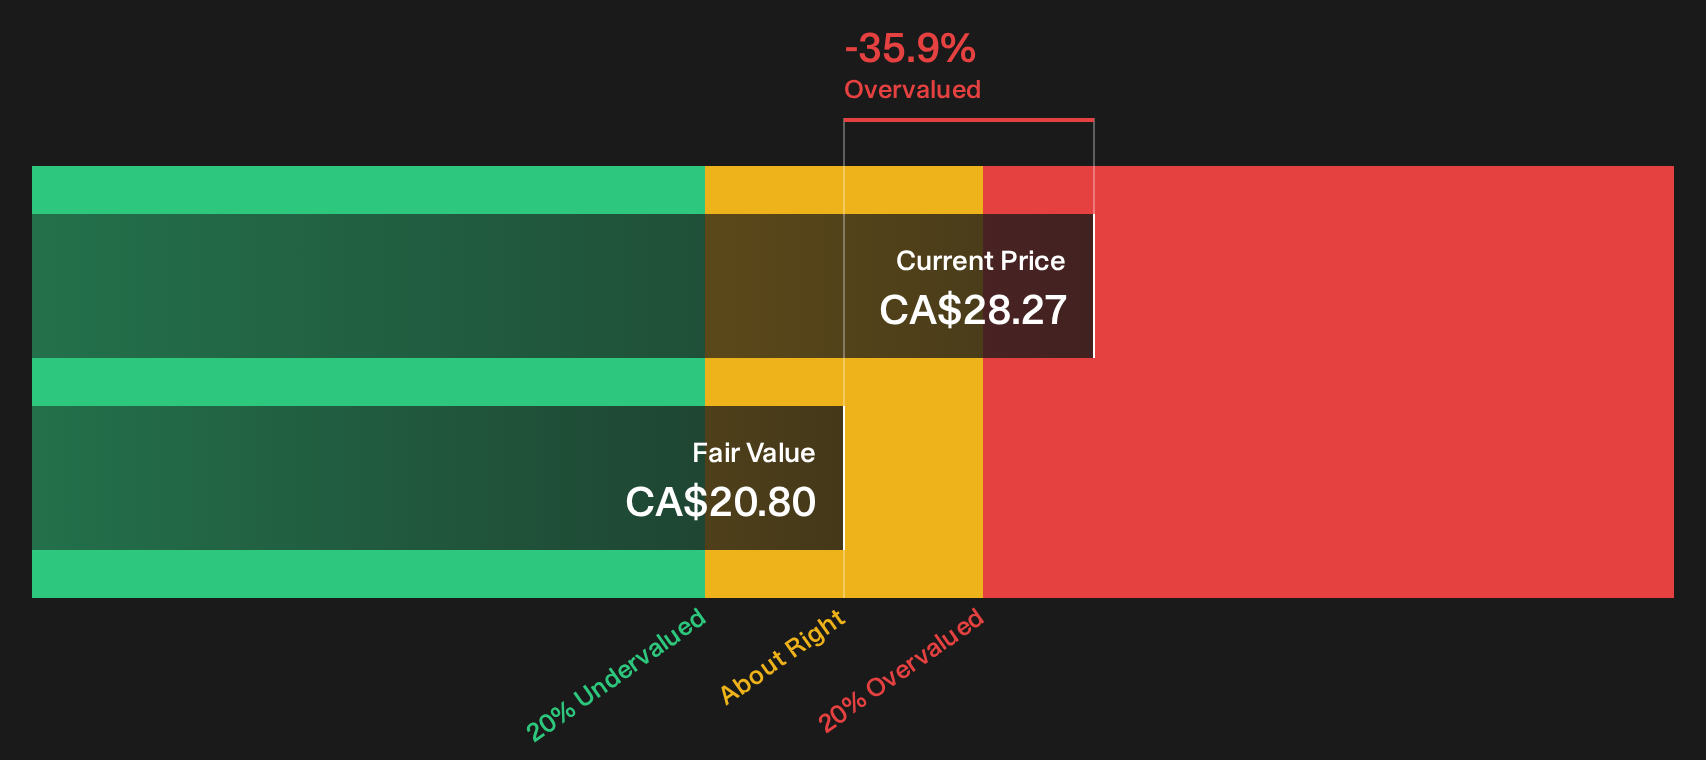
The P/E comparison presents Extendicare as inexpensive relative to its healthcare peers. The SWS DCF model gives a different result. On that framework, EXE at CA$28.27 trades above an estimated future cash flow value of roughly CA$20.80, which suggests an overvalued reading instead.
This difference between earnings-based and cash-flow-based views raises a straightforward question for investors: which lens matters more for a senior care operator that relies heavily on funding structures and long-term contracts, the current profit multiple or the cash flows our DCF model is aiming to capture over time?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Extendicare for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 6 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals across valuation, cash flows and returns can leave Extendicare looking both appealing and risky at the same time, so move quickly, review the underlying data and decide where you stand using the 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Extendicare?
If Extendicare's mix of dividends, valuation and cash flow trade offs caught your attention, broadening your watchlist with other focused ideas can sharpen your edge.
- Spot potential mispriced opportunities early by scanning a curated pool of high quality prospects through the 6 high quality undervalued stocks.
- Target resilience first by filtering for companies with strong finances using the list of solid balance sheet and fundamentals (5 results).
- Hunt for under-the-radar potential by reviewing the 7 high quality undiscovered gems before other investors catch on.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com