


- A. O. Smith reported third quarter 2026 sales of US$940.5 million and net income of US$126.3 million, with earnings per share from continuing operations at US$0.93. Nine month figures showed slightly lower sales and profit compared with the prior year.
- The company also updated full year 2026 guidance to exclude its China business, with net sales projected between US$3.27b and US$3.29b. This update places more focus on the underlying North American franchise that had already been carrying much of the investment narrative.
- We will examine how A. O. Smith's investment narrative is affected by the updated 2026 guidance that now excludes the China business.
Compare how A. O. Smith’s steady North American focus stacks up against other resilient operators with 30 resilient stocks with low risk scores in similar conditions.
A. O. Smith Investment Narrative Recap
To own A. O. Smith, you need to believe the North American water heater and boiler business can keep doing the heavy lifting while any China drag is contained. According to Brunhilde_Wagner, an investor in the Simply Wall St Community, the real story sits in that concentrated, replacement driven market with long running pricing power.
The latest quarter showed relatively stable sales and earnings, so the short term picture looks mostly unchanged. The key near term catalyst remains how cleanly management executes around China. The biggest operational risk still sits with the 2029 U.S. heat pump mandate and whether A. O. Smith’s distribution strength holds up through that transition.
The most relevant update here is the revised 2026 guidance that strips out the China business and pegs net sales between US$3.27b and US$3.29b. That shift gives you a clearer read on the core North American operation that Brunhilde_Wagner argues has been carrying the investment case while China has been in structural decline.
By separating China from the outlook, management is giving investors a cleaner yardstick for tracking execution against the main catalyst, the outcome of the China review, and how it affects reported margins and earnings quality. It also helps you weigh the China decision against other moving pieces like the upcoming heat pump mandate and the relatively new leadership team.
Brunhilde_Wagner bases the US$55.00 fair value on a North American model that assumes revenue will expand at 4.1% a year and a future profit margin will settle around 13.1%. Together, these assumptions support the view that the franchise can justify that valuation level on its own economics.
Uncover why A. O. Smith's fair value points to a 16% potential downside to its current price, suggesting a valuation premium that may not hold.
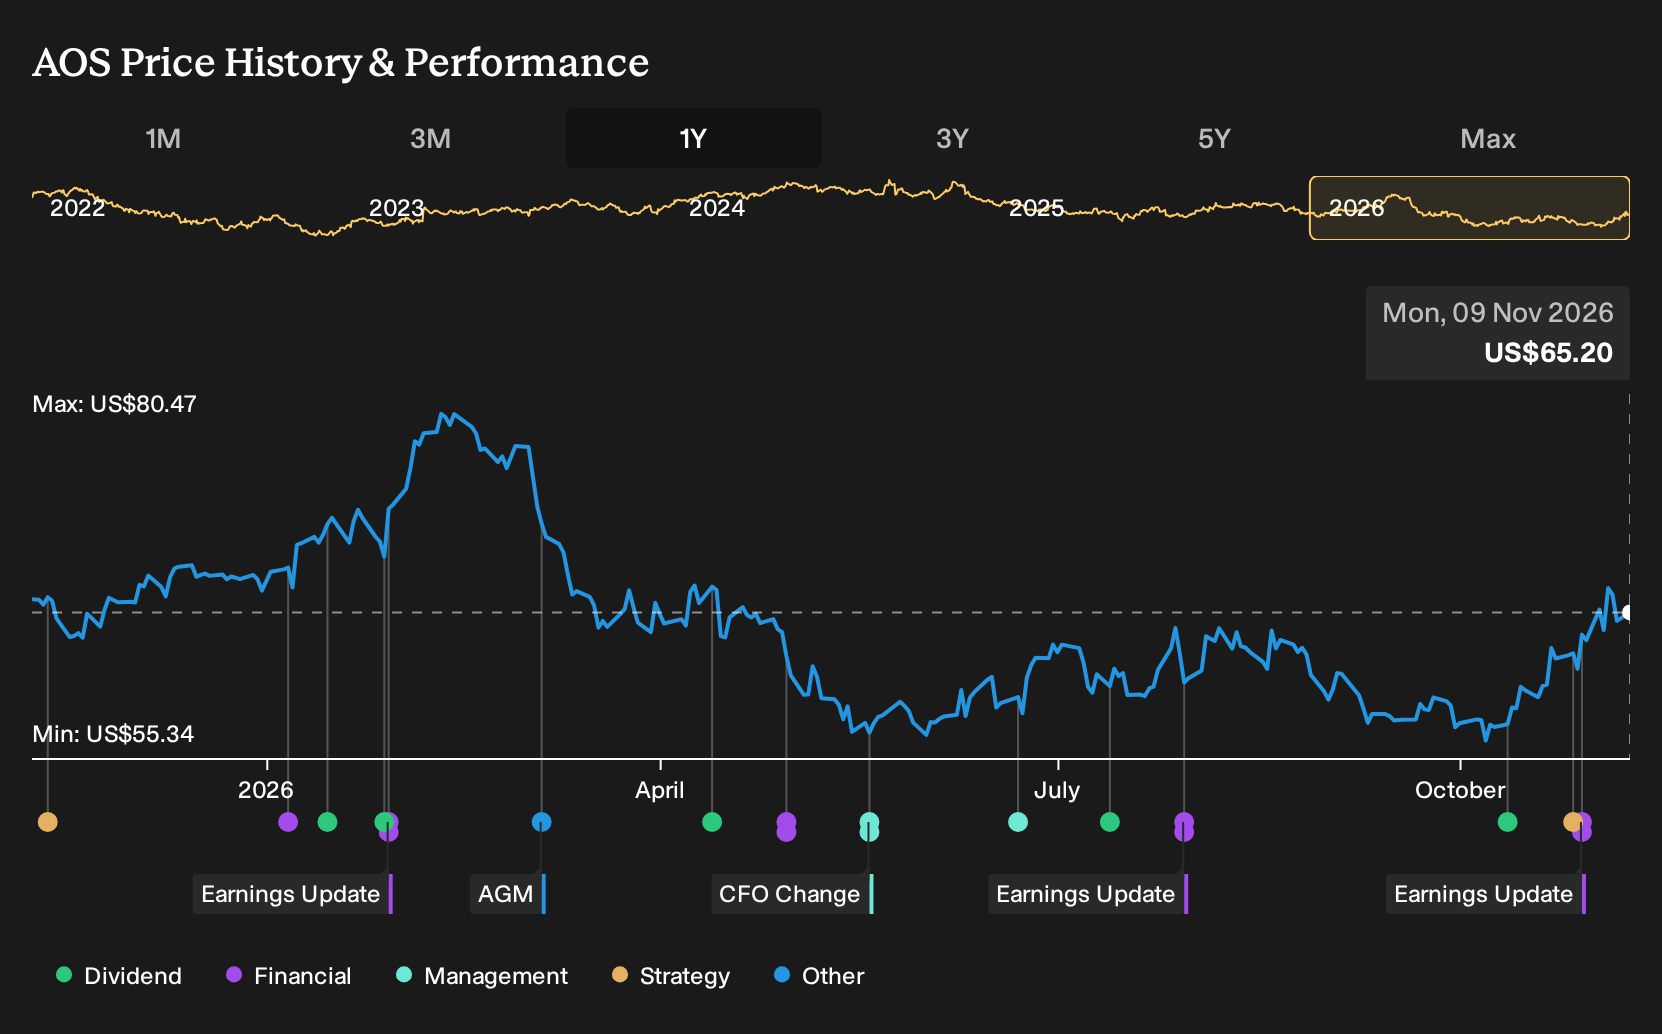
Exploring Other Perspectives
Some of the most optimistic analysts focus less on the 2029 heat pump risk and more on A. O. Smith’s boiler and India potential. Before this earnings update, a bullish group was modeling revenue around US$3.8b and earnings of US$608.3 million by about 2029, so their storyline could shift once this latest guidance fully filters through.
Explore 4 other A. O. Smith fair value estimates, including one that suggests as much as 31% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your A. O. Smith research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for A. O. Smith. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate A. O. Smith's overall financial health at a glance.
Looking For More Investment Ideas Beyond A. O. Smith?
If A. O. Smith has sharpened your view on what quality looks like, use that same filter across the market with the Simply Wall St Screener and build a watchlist that actually fits your style.
- For investors hunting for strong businesses trading at appealing valuations, scan a focused pool of 33 high quality undervalued stocks that already combine quality fundamentals with pricing that may look reasonable on closer inspection.
- If resilience matters most to you, concentrate on balance sheet strength and financial robustness by zeroing in on a list of solid balance sheet and fundamentals (25 results) that can help you stress test ideas under tougher conditions.
- When you want companies that the broader market might not be watching closely yet, broaden your opportunity set with a curated group of 19 high quality undiscovered gems that still show solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com