


Enbridge has delivered a 78.5% total return over the past 5 years, and with the stock recently closing at $66.87, the real question for investors is whether that price is still in line with what its earnings can justify.
- A 78.5% gain over 5 years puts real pressure on the current earnings multiple to carry more of the load in explaining where Enbridge trades today.
- Recent project additions, acquisitions in U.S. oil pipelines, and equity funding mean the earnings story now hinges more on how efficiently Enbridge can convert its large asset base and capital spend into cash flow.
- The analysts covering Enbridge have run their own numbers. See what analysts think Enbridge's shares could be worth.
The issue now is whether the earnings that support Enbridge can fully explain the current share price or if expectations have stretched beyond what the income statement reasonably supports.
If you want more context around whether Enbridge's 78.5% five year return and earnings profile still stack up, it can help to compare it with 6 high quality undervalued stocks.
Is Enbridge Fairly Priced on Earnings?
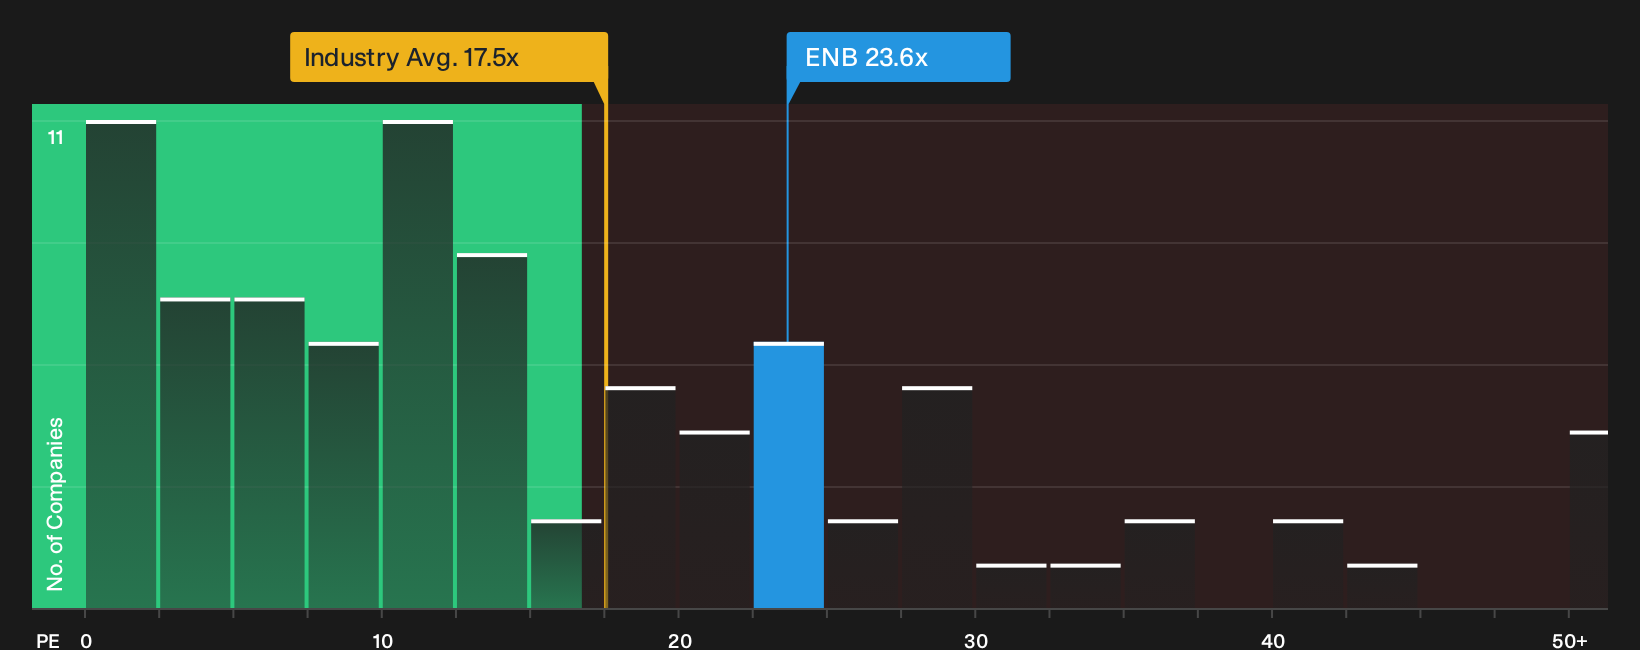
The P/E multiple is a useful yardstick for Enbridge because earnings and cash generation are central to how investors usually judge large pipeline and utility platforms. On this measure, Enbridge trades on about 23.6x earnings, which is above the Oil and Gas industry average of roughly 17.5x but slightly below the peer group near 25.1x.
The fair multiple that factors in Enbridge's size, sector, profitability and risk profile points to a level close to where the stock trades today. As a result, the current P/E looks about right rather than clearly cheap or expensive. Because recent project completions and acquisitions have supported earnings and distributable cash flow in 2026, that pricing suggests the market is recognising the pipeline and gas utility footprint without awarding an aggressive premium. For a closer sense of how much headroom that leaves relative to the modelled fair value, it helps to look at a full side by side multiple breakdown. Explore the numbers behind Enbridge's P/E valuation.
The Enbridge Narrative: What Would Justify Today's Price?
Narratives for Enbridge pick up where the P/E puzzle leaves off by spelling out which paths for growth, profit margins and earnings would need to hold for the stock to be worth materially more or less than today’s price. Each scenario ties a fair value estimate to a clear story about Enbridge's potential catalysts and key risks so you can track over time which version of events lines up with reality.
The bullish view on Enbridge leans heavily on project execution, while the bear case worries the recent run already prices in too much.
Bull case: 15% undervalued
This is drawn from the analyst consensus Narrative on Simply Wall St, which aggregates forward estimates into one combined view.
"Enbridge is positioned to use its approximately $41b secured growth backlog and roughly $50b identified organic opportunity set through 2030 to add new regulated and contracted assets…"
Discover why this Narrative puts Enbridge at 15% undervalued.
Bear case: 42% overvalued
According to andy_c, an investor in the Simply Wall St Community, the concern starts with what you pay for that quality profile.
"The recommendation is to HOLD because it is a quality business with solid fundamentals, but the limited margin of safety suggests a better entry point would be below $40…"
Explore why this Narrative puts Enbridge at 42% overvalued.
One big Enbridge question still sits off to the side
Valuation only tells you what the assets might be worth, not who is steering them or how those decision makers are rewarded for the choices they make. See who runs Enbridge and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com