


Why Welltower Is Back On Investors' Radar
Welltower (WELL) has drawn fresh attention after consistent quarterly sales growth around 38 to 40%, a 5.65% uplift in next-year revenue estimates, and a constructive technical setup pointing to a potential breakout pattern.
The recent technical setup is landing on top of strong price action, with a 30 day share price return of 9.70% and a year to date share price gain of 32.32% that hints at building momentum rather than a short term spike. At the same time, total shareholder return of 31.31% over one year and very large gains over three and five years suggest Welltower has already rewarded patient investors. As a result, the current breakout narrative is arriving after a substantial run rather than from a depressed base.
Scan for other potential breakouts with similar momentum and institutional-quality fundamentals by starting with our hand picked 30 resilient stocks with low risk scores alongside Welltower.
Welltower now combines a fast growing senior housing platform with a share price that has already moved hard. The real tension is simple: Are you paying up for quality, or just paying up?
Most Popular Narrative: 6% Undervalued
The analyst consensus Narrative on Simply Wall St places Welltower's fair value at $262.05, a touch above the last close of $247.35. It leans on execution in senior housing and capital recycling to justify that gap.
Significant off market acquisition activity, with about US$15.5b of largely newer senior housing assets bought or under contract at discounts to replacement cost and with room for occupancy improvement, gives Welltower a pipeline of properties that can contribute to future revenue and NOI expansion as they stabilize.
See why 32 investors see Welltower as 6% undervalued.
Result: Fair Value of $262.05 (UNDERVALUED)
Still, the bullish Welltower story can crack if recycled assets drag on FFO longer than expected or if concerns about governance and executive pay continue to escalate.
Find out about the key risks to this Welltower narrative.
Another View: What Multiples Say About Welltower
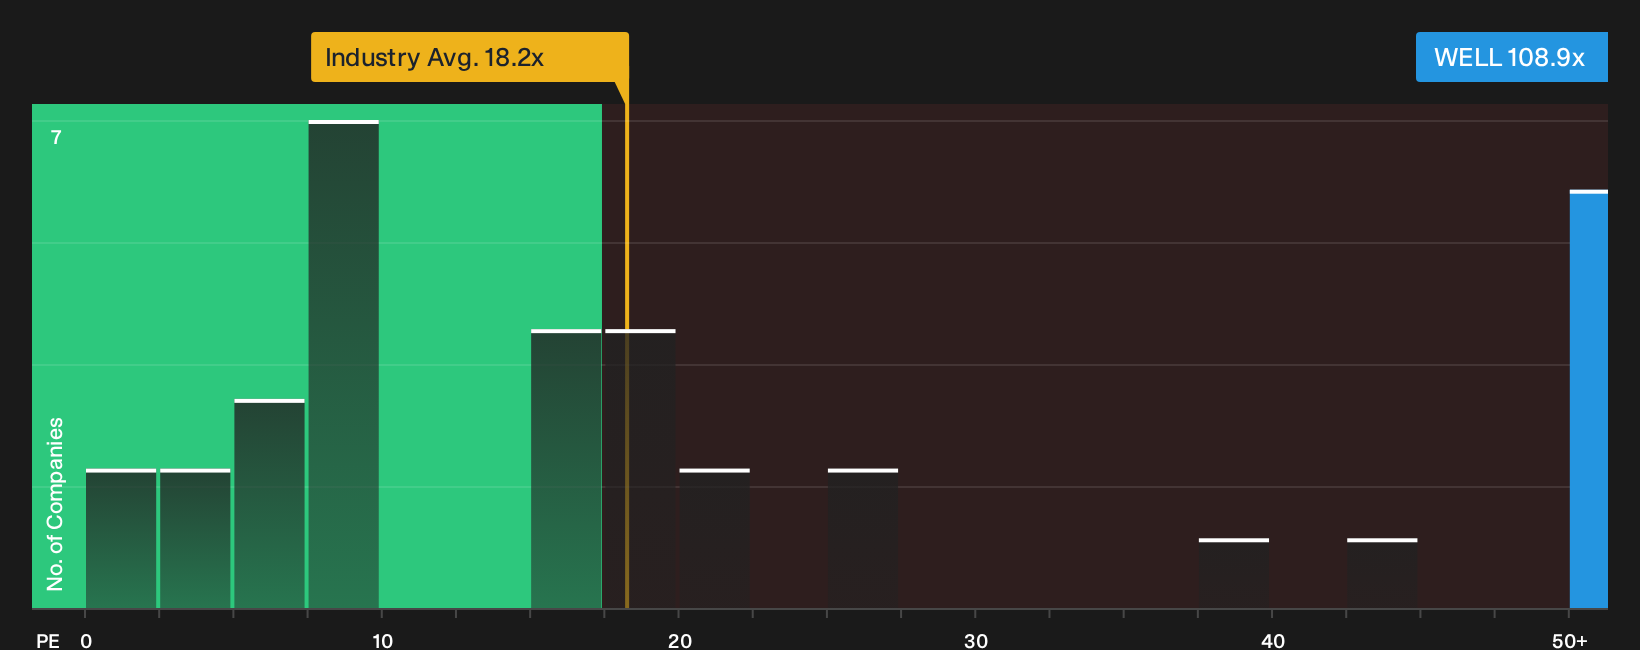
Welltower may look modestly undervalued against a $262.05 fair value, yet the P/E ratio of 108.9x tells a tougher story. That is richer than both the Global Health Care REITs average of 18.2x and peers at 95.1x, and far above the fair ratio of 41.1x. For investors, that gap points to real valuation risk if sentiment cools.
To see how that premium lines up with the underlying assumptions and whether the numbers justify it, take a closer look at the valuation breakdown with See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on the story so far? Put the headlines aside for a moment, review the full set of numbers, and weigh both the upside and the concern captured in 2 key rewards and 1 important warning sign.
Looking For More Ideas Beyond Welltower?
If the Welltower setup has you thinking more broadly about your portfolio, do not stop at a single opportunity. Cast the net wider and build a watchlist packed with clear, data backed candidates that can compete for your next dollar.
- Target rock solid balance sheets and dependable fundamentals with a curated list of solid balance sheet and fundamentals (25 results) that helps you focus on financial strength first.
- Hunt for mispriced quality by scanning a focused 33 high quality undervalued stocks that highlights companies where fundamentals and price tell two very different stories.
- Explore potential income streams by checking a hand built 6 dividend fortresses that concentrates on high yielding businesses with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com