


Merck has delivered a strong multi‑year share price run, and with the stock last closing at US$148.76, the live question is whether that level is supported by the cash the business can generate. Positive trial updates, portfolio reshaping and pipeline investments all feed into future cash flows, which is exactly what the Discounted Cash Flow (DCF) lens is built to weigh.
- Over the past 5 years, Merck has returned 107.1%, which puts a lot of weight on the assumption that its future cash flows can sustain that kind of market confidence.
- The recent Phase 2b success for efinopegdutide in MASH and liver fibrosis may support expectations for future cash flow from new therapies, while the planned CDMO divestment to Lonza could reshape how Merck allocates capital across its drug pipeline.
- Prefer to judge Merck on earnings? See why Merck's 149.5x P/E tells a different valuation story.
The issue now is whether Merck's current share price is appropriately grounded in the cash flows implied by its intrinsic value estimate under the Discounted Cash Flow (DCF) approach.
If you are weighing Merck through its cash flows, it can help to compare it with other healthcare groups screened on clear fundamentals, starting with solid balance sheet and fundamentals stocks screener (25 results).
Is Merck a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here values Merck on the cash it is expected to return to shareholders over time. Latest twelve month free cash flow sits at about $14.8b, and analyst projections in the model indicate increasing free cash flow into the early 2030s rather than a shrinking stream.
That profile helps explain why the DCF projections put Merck's estimated intrinsic value substantially above the current share price of US$148.76. Positive Phase 2b data for efinopegdutide in MASH and liver fibrosis fits this context, because it supports the idea that Merck's pipeline can continue contributing to that cash flow profile over the long term. Find out what Merck could be worth using our Discounted Cash Flow (DCF) estimate.
The Merck Narrative: What Would Justify Today's Price?
Merck’s Simply Wall St Narratives pick up where the DCF puzzle leaves off by spelling out which paths for future growth, margins and earnings would need to hold for the stock to be worth materially more or less than today’s price on the Community page. Each scenario ties a fair value to a particular storyline around Merck's potential catalysts and key risks, so you can monitor which version seems to be unfolding as new information emerges.
Bulls and bears are both leaning on Merck’s pipeline story, yet they split on how fully that execution risk is already baked into the price.
Bull case: 7% undervalued
The analyst consensus Narrative on Simply Wall St ties the optimistic view to how far Merck can push its next wave of medicines.
"Merck plans to bring over 20 new growth drivers to market in the coming years, and management now points to more than US$70b in non risk adjusted mid 2030s revenue potential from this next generation portfolio…"
Discover why this Narrative puts Merck at 7% undervalued.
Bear case: 20% overvalued
The bearish analyst Narrative on Simply Wall St focuses on how much Merck still leans on a few blockbusters as patents age.
"Bearish analysts expect Merck to remain heavily exposed to a small group of flagship drugs such as KEYTRUDA, which could leave long term revenue and margin trends vulnerable as loss of exclusivity and generic headwinds build…"
Explore why this Narrative puts Merck at 20% overvalued.
One more Merck signal worth checking before you move on
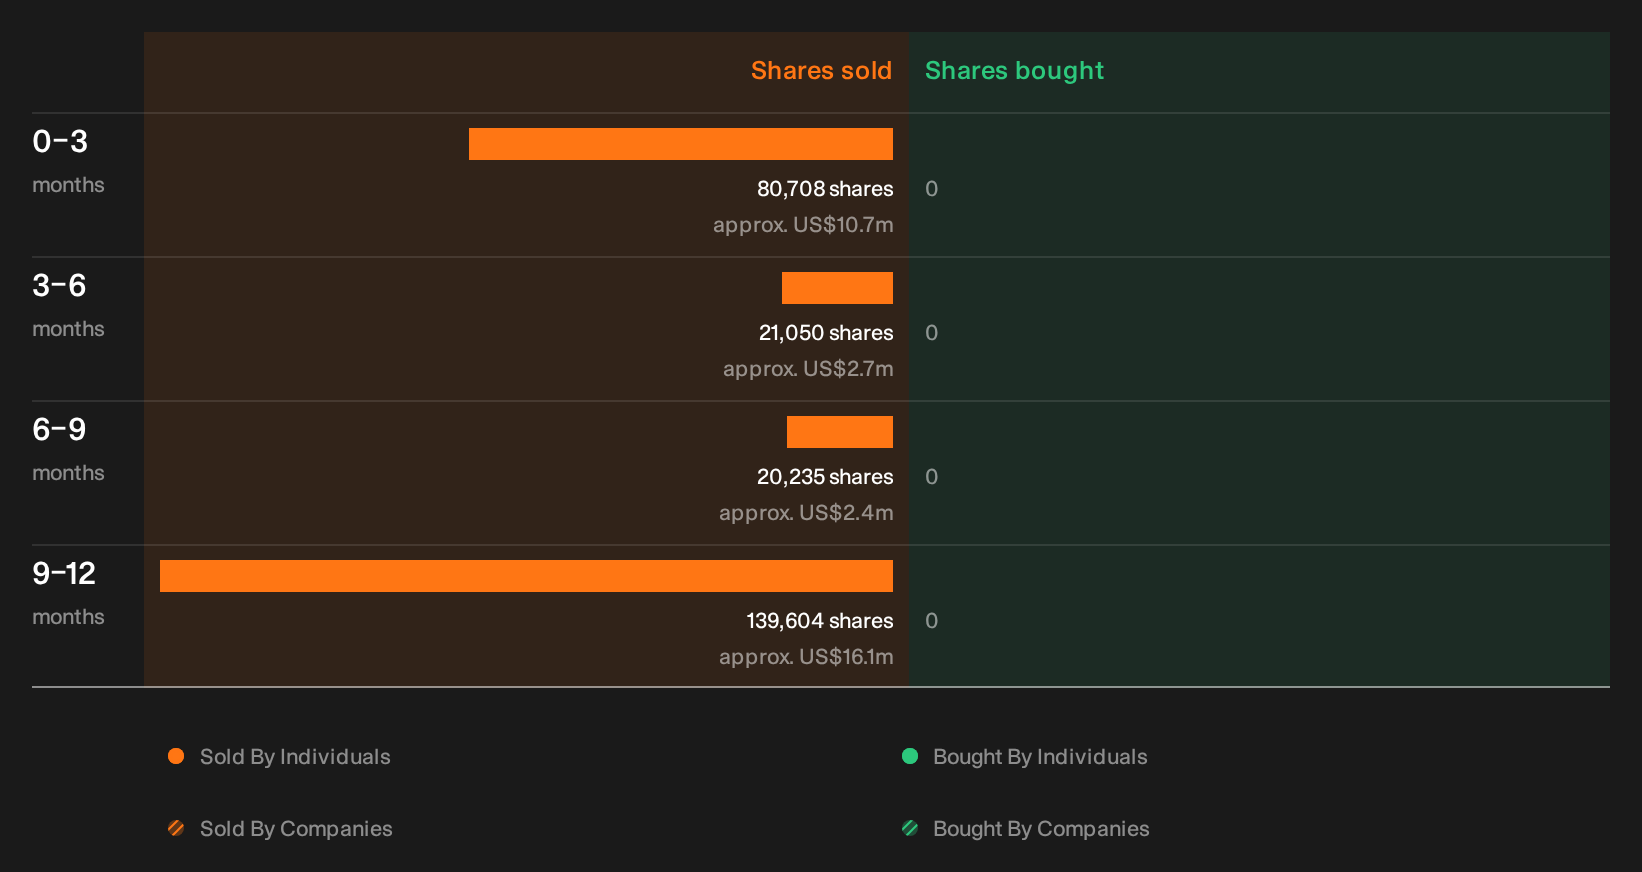
Before you rely too heavily on where the numbers say Merck should trade, it is worth seeing which executives have recently sold shares, how much stock changed hands, and what that activity might suggest. See the recent insider selling flagged for Merck.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com