


Q3 earnings and guidance shift the Progyny story
Progyny (PGNY) is back in focus after third quarter results showed higher sales and net income than a year earlier, along with raised full year guidance and favorable commentary from several research firms.
The recent guidance upgrade and record selling season have fed straight into the chart, with Progyny’s 7 day share price return of 22.24% and 30 day share price return of 28.71% helping push the stock to US$35.95. At the same time, the 1 year total shareholder return of 52.20% contrasts with a 5 year total shareholder return that is still down 42.44%, suggesting strong momentum has emerged only more recently.
Scan how Progyny’s latest breakout compares with other health-focused stocks on the move by checking the hand picked 36 healthcare AI stocks shaping this part of the market.
Progyny now trades just below both analyst targets and one fair value estimate after a sharp run. Is this a fresh discount, or is the market quietly pricing in risk?
Most popular Progyny narrative: 60% undervalued
Progyny’s last close at $35.95 sits well below the analyst consensus Narrative fair value of $36.17, which builds off blended earnings and cash flow assumptions from the analyst consensus Narrative on Simply Wall St and results in a discount to fair value of about 60% in that framework.
The valuation currently reflects that the recent share price decline following lower EBITDA guidance and modestly softer growth expectations is giving limited credit to Progyny's cash generation, debt free balance sheet, and share repurchases. These factors together support a more favorable view that the stock may be undervalued.
See why 26 investors see Progyny as 1% undervalued.
Result: Fair Value of $36.17 (UNDERVALUED)
Still, if employer cost cutting reduces appetite for premium fertility and women’s health benefits, or utilization stays soft, the bullish Progyny narrative could easily stall.
Find out about the key risks to this Progyny narrative.
Another view on Progyny’s valuation
The story so far leans on a blended analyst fair value of $36.17 that points to Progyny as undervalued. A simple earnings multiple tells a different story. PGNY trades on a P/E of 29.1x, above both the US Healthcare sector on 24.9x and its own fair ratio of 27.7x. That premium suggests investors are already paying up for quality, which can limit upside if execution or sentiment cools.
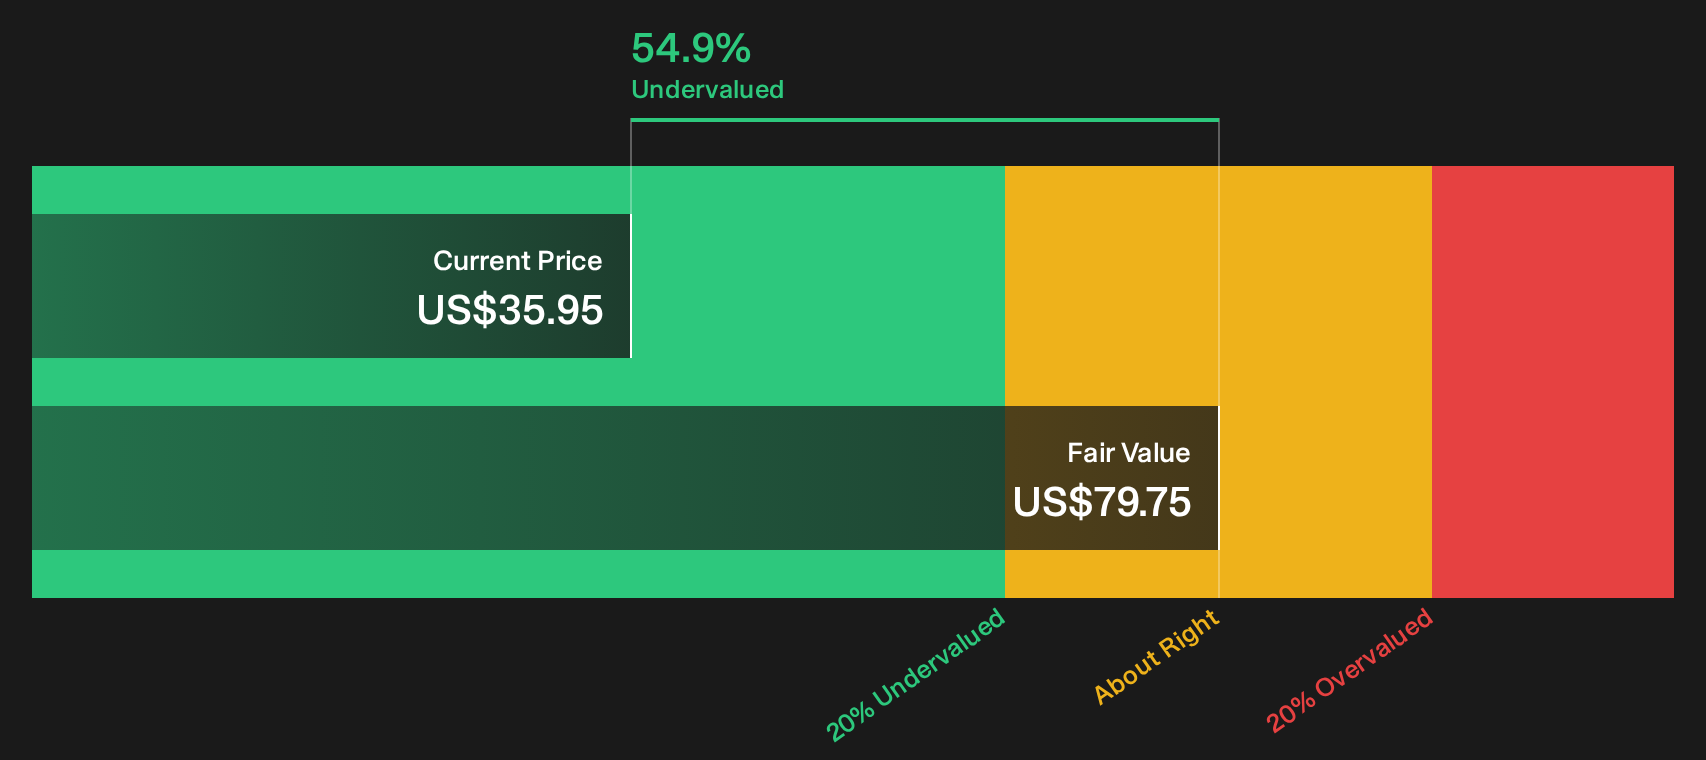
For a different angle built around future cash flows rather than earnings multiples, it is worth studying how our DCF model handles Progyny’s assumptions Look into how the SWS DCF model arrives at its fair value..
Next Steps
Feeling cautious or optimistic after reviewing Progyny’s setup is natural, although the clock never stops on new information. Take a moment to weigh the upside that some investors see in its profile by checking the 3 key rewards.
Looking for more investment ideas beyond Progyny?
If Progyny has sharpened your focus, do not stop there. Broader context across other opportunities can make your portfolio decisions more grounded and confident.
- Target resilient cash generators by scanning companies with long term balance sheet strength using the list of solid balance sheet and fundamentals (25 results).
- Seek out potential mispricings and compare valuations across the market through the 33 high quality undervalued stocks before committing fresh capital.
- Anchor your income plan by reviewing businesses that aim to combine stability with high payouts using the 6 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com