


Essex Property Trust (ESS) has investors’ attention after releasing third quarter and nine month 2026 results alongside a higher full year earnings outlook, combining softer profit figures with a more optimistic guidance range.
The higher earnings guidance has come amid gradually improving sentiment, with Essex Property Trust’s share price up 7.26% year to date and the 1-year total shareholder return at 10.12%. A 3-year total shareholder return of 49.79% contrasts with a weaker 5-year record and suggests that momentum has recently been rebuilding.
See how Essex Property Trust compares to other real estate players showing resilient earnings guidance in our hand picked list of list of solid balance sheet and fundamentals (25 results)
Essex Property Trust now trades between a higher earnings outlook and mixed profit trends, with analyst targets and intrinsic value estimates pulling in different directions. Where does a fair entry point really fall within that range?
Most Popular Narrative: 8% Undervalued
The analyst consensus Narrative on Simply Wall St places Essex Property Trust’s fair value at $298.03, above the last close of $275.54, framing the current price as a discount once those long term cash flow assumptions are applied.
Capital allocation that now includes a US$500m share repurchase authorization, alongside a reduced structured finance and preferred equity book of about US$100m and minimal near term debt maturities with over US$1b of liquidity, gives Essex Property Trust scope to direct cash flow toward accretive buybacks and high spread projects, which can influence core FFO per share and return on equity.
See why 12 investors see Essex Property Trust as 8% undervalued.
The Narrative relies on a discount rate of 7.241% and assumes annual revenue growth of about 2.57% with profit margins around 21.21%. As a result, the $298.03 figure reflects relatively moderate improvement rather than aggressive expansion. With Essex Property Trust also screened as trading 27.8% below an internal estimate of future cash flow value at $381.75, readers can compare the consensus fair value and the DCF style output to judge how much upside they feel comfortable underwriting at today’s share price.
Result: Fair Value of $298.03 (UNDERVALUED)
Still, the narrative can break if Southern California rent softness and Los Angeles delinquencies persist, or if new regional rules hit Essex Property Trust’s concentrated markets.
Find out about the key risks to this Essex Property Trust narrative.
Another View: Essex Property Trust Looks Expensive On Earnings
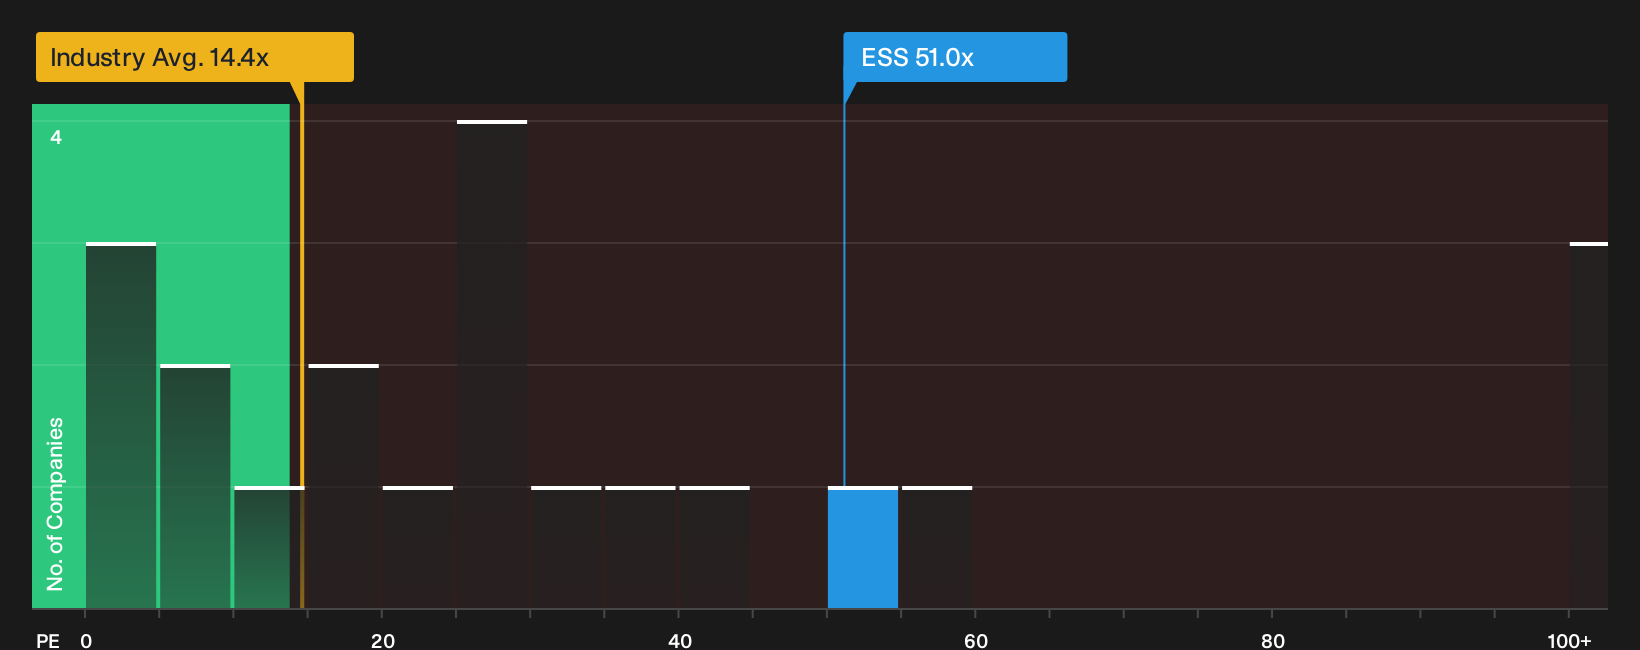
The simply-worded fair value narrative for Essex Property Trust leans on long term cash flows, yet the current P/E of about 51x tells a different story. That multiple sits well above peers at 29.8x, the Global Residential REITs average of 14.5x, and even a fair ratio estimate of 35.2x.
This kind of gap can matter in practice. If sentiment cools or earnings land closer to the lower end of forecasts, a high P/E can limit how much protection you get on the downside. The question is whether you are comfortable paying a premium multiple when another model points to value, or if you want a greater margin of safety before acting.
See what the numbers say about this price, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on value and risk often create real opportunity. Check the underlying figures, weigh the trade offs, and consider acting before sentiment shifts. To balance the optimism around potential rewards with caution on the flagged issues, study the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Essex Property Trust?
If Essex Property Trust has sharpened your focus on valuation and risk, do not stop here. Cast the net wider and let data rich screeners surface ideas for you before the crowd catches on.
- Target value opportunities by zeroing in on companies that combine quality fundamentals with attractive pricing through the 33 high quality undervalued stocks.
- Protect your downside by filtering for businesses that carry stronger balance sheets and consistent fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Explore potential opportunities among high quality smaller companies that many investors may be overlooking through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com