


AI just got a fresh stress test, with Anthropic targeting up to $90.4b in new capital and a potential $1t valuation at the same time as regulators circle and investors reassess anything with an AI label. That mix of hype, hard numbers, and huge chip commitments creates real fear of missing out and real risk. This piece walks through 3 stocks linked to Anthropic’s world, showing where the exposure looks helpful and where it might demand extra caution.
The three stocks in this article are just a starting sample, since the full screen surfaced 107 more companies with equally compelling narratives across the AI infrastructure and semiconductor supply chain that are not covered here. If you want to identify potential AI infrastructure and semiconductor suppliers that fit your own risk and return criteria, head straight into the AI Infrastructure & Semiconductor Suppliers screener to filter, analyze, and focus on the opportunities that match your playbook.
Advantest (TSE:6857)
Advantest is one of the purest ways to play the AI Infrastructure & Semiconductor Suppliers theme because its testers sit wherever GPUs, AI accelerators and high bandwidth memory roll off the line. This is exactly why the analyst consensus Narrative on Simply Wall St focuses so much on its AI linked SoC platform.
"The ongoing proliferation of AI inference and compute applications across GPUs, custom ASICs, CPUs and networking devices is expanding SoC tester demand, where Advantest reports high market share and broad 93000 platform coverage, which can support revenue and earnings as this test intensity is converted into orders."
What really matters now is how one quiet cost pressure shapes the gap between that test heavy demand story and the profits shareholders receive.
That quiet cost pressure is exactly where the story starts to diverge from the headline AI excitement, which is why the full narrative for Advantest digs into how test intensity, pricing power and capital needs could be decoupling beneath the surface.

CXMT (SHSE:688825)
CXMT focuses on DRAM chips that feed memory hungry GPUs and AI data-center servers, so it fits cleanly into the AI infrastructure and semiconductor suppliers theme. The business carries a market cap of about CN¥2,714.7b, reflecting its scale in this part of the chip supply chain.
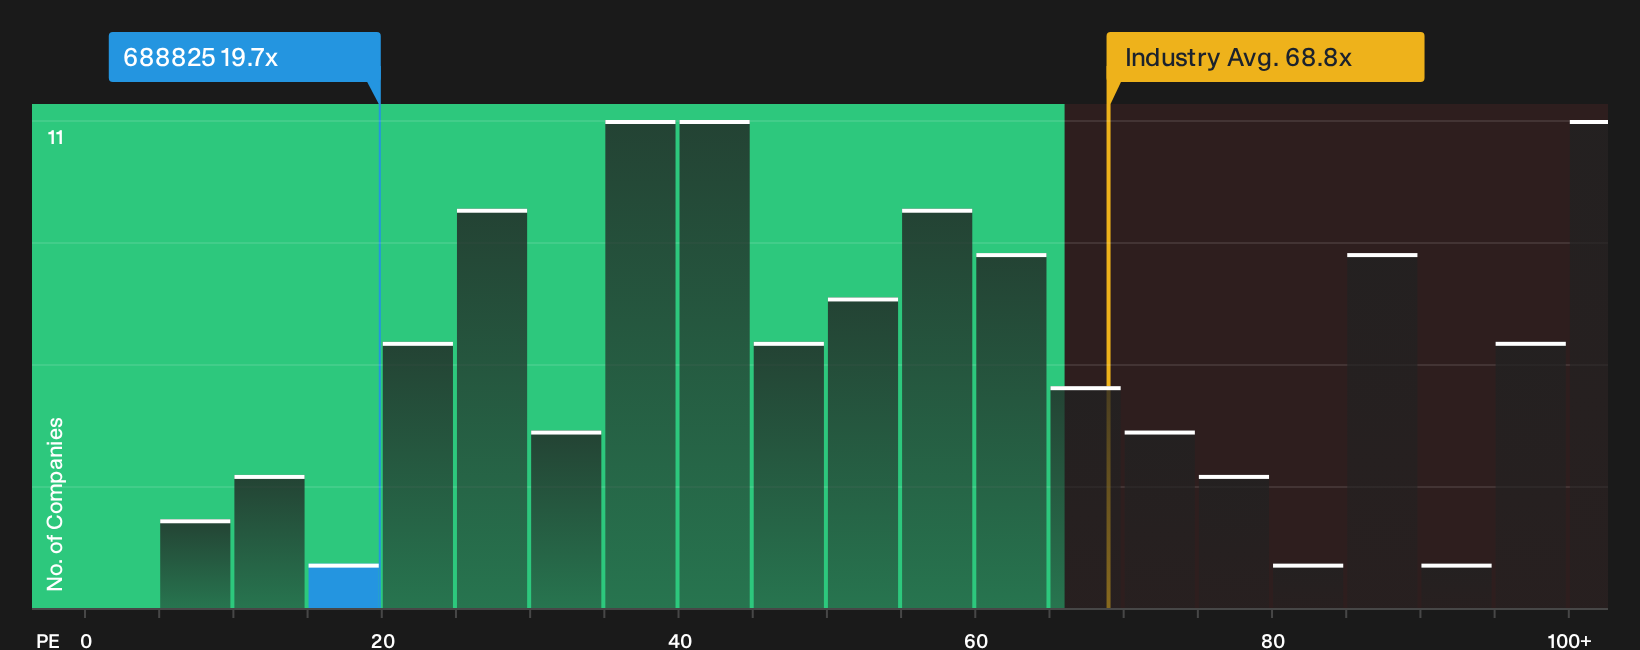
CXMT gives you pure exposure to AI grade memory, with DRAM feeding servers, PCs, mobiles and smart cars that need fast access to data. Forecast double digit revenue and earnings growth, high recent profitability and a P/E well below many semiconductor peers all sit on one unresolved pressure that could affect how that growth is ultimately reflected in investor outcomes.
That unresolved pressure is exactly why investors are turning to the 3 key rewards and 1 important warning sign to see whether CXMT’s valuation is masking upside or early warning signs.
KLA (KLAC)
KLA is effectively the quality gatekeeper for AI infrastructure, with its inspection and metrology tools sitting on the same production lines that turn capex into usable GPUs, high bandwidth memory and advanced packaging. The Semiconductor Process Control unit generates about US$13.1b of its revenue, with Specialty Semiconductor Process adding roughly US$604m and PCB and Component Inspection about US$803m, while the group’s market value sits around US$180.4b.
The draw with KLA in this AI infrastructure and semiconductor suppliers screen is simple. If chipmakers keep spending heavily on cutting edge fabs and packaging so data centers can handle Anthropic scale workloads, the analyst consensus Narrative on Simply Wall St sees this process control heavyweight as one of the clearest beneficiaries.
"Rising AI infrastructure and high bandwidth memory investment is lifting wafer equipment demand. KLA’s backlog of around US$12.5b, with lead times that extend into 2027 and 2028, supports multi year visibility that can translate into higher revenue and earnings quality."
The open question for investors is what happens to that visibility and earnings power if a single key assumption about future wafer equipment spending breaks.
If that assumption is wrong or accelerating, the full narrative for KLA explains how KLA’s backlog, AI capex and valuation could be quietly decoupling beneath the surface.

Seeking Fresh Alternatives Before They Fly
New themes move fast, and the strongest breakout stories rarely stay under the radar for long. Spot fresh momentum before the crowd, while it matters, and act now.
- Hunt for smaller players building real traction with AI, and scan the 12 AI small caps that could gain attention once the market catches up.
- Target resilient cash generators that still trade at appealing valuations by working through the curated 20 high quality undervalued stocks before renewed buying pressure closes the gap.
- Position for a potential power upgrade cycle and track companies in the 42 power grid technology and infrastructure stocks while grid spending stories are still being quietly priced.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com