


CenterPoint Energy, Inc. (CNP), headquartered in Houston, Texas, engages in the business of power generation and distribution. Valued at $27.1 billion by market cap, the company conducts activities in electricity transmission and distribution, natural gas distribution, interstate pipeline and gathering operations, and power generation.
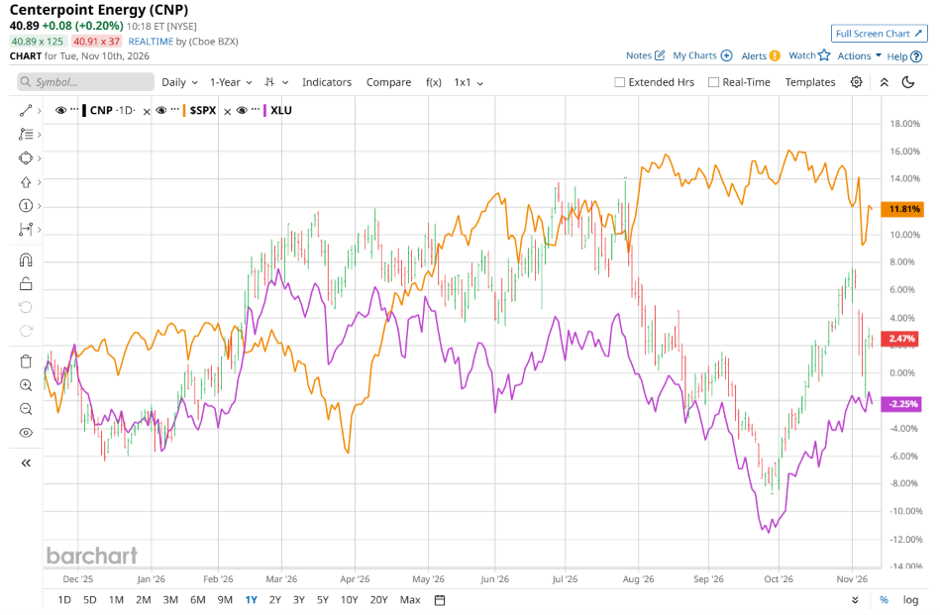
Shares of this leading electricity and natural gas provider have underperformed the broader market over the past year. CNP has gained 3% over this time frame, while the broader S&P 500 Index ($SPX) has rallied nearly 12.2%. In 2026, CNP stock is up 6%, compared to SPX’s 10.3% gains on a YTD basis.
Narrowing the focus, CNP’s outperformance is apparent compared to the State Street Utilities Select Sector SPDR ETF (XLU). The exchange-traded fund has declined about 3.3% over the past year. Moreover, CNP’s returns on a YTD basis outshine the ETF’s 1.6% gains over the same time frame.
CNP demonstrated resilient performance, highlighted by strong Q3 2026 results, prompting management to raise earnings guidance, increase its capital plan, and extend its higher growth outlook through 2030. The company’s fundamentals were bolstered by proactive grid resiliency and infrastructural investments, such as the Greater Houston Resiliency Initiative, which involved thousands of crew members installing storm-resilient poles and automation devices. While operations occasionally navigated severe weather headwinds requiring mutual aid deployments to assist with regional restoration efforts, CNP continued to deliver steady quarterly cash dividends of $0.24 per share and maintained positive momentum supported by Wall Street expectations of double-digit EPS growth.
On Oct. 27, CNP shares closed up by 1.9% after reporting its Q3 results. Its adjusted EPS of $0.53 topped Wall Street expectations of $0.50. The company’s revenue was $2.19 billion, topping Wall Street forecasts of $2.15 billion. CNP expects full-year adjusted EPS in the range of $1.90 to $1.92.
For the current fiscal year, ending in December, analysts expect CNP’s EPS to grow 8.5% to $1.91 on a diluted basis. The company’s earnings surprise history is mixed. It beat the consensus estimate in two of the last four quarters while missing the forecast on two other occasions.
Among the 20 analysts covering CNP stock, the consensus is a “Moderate Buy.” That’s based on nine “Strong Buy” ratings, and 11 “Holds.”
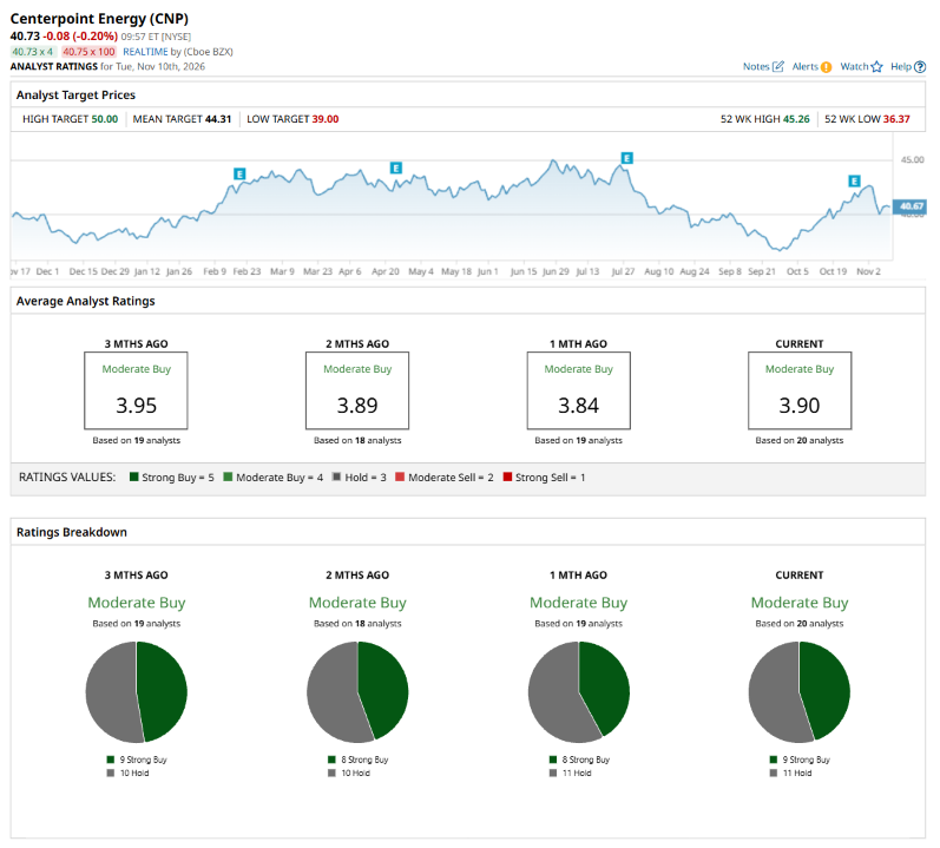
This configuration is more bullish than a month ago, with eight analysts suggesting a “Strong Buy.”
On Oct. 28, Wells Fargo & Company (WFC) analyst Shahriar Pourreza maintained a “Buy” rating on CNP, with a price target of $49, implying a potential upside of 20.3% from current levels.
The mean price target of $44.31 represents an 8.8% premium to CNP’s current price levels. The Street-high price target of $50 suggests an upside potential of 22.8%.
On the date of publication, Neha Panjwani did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.