


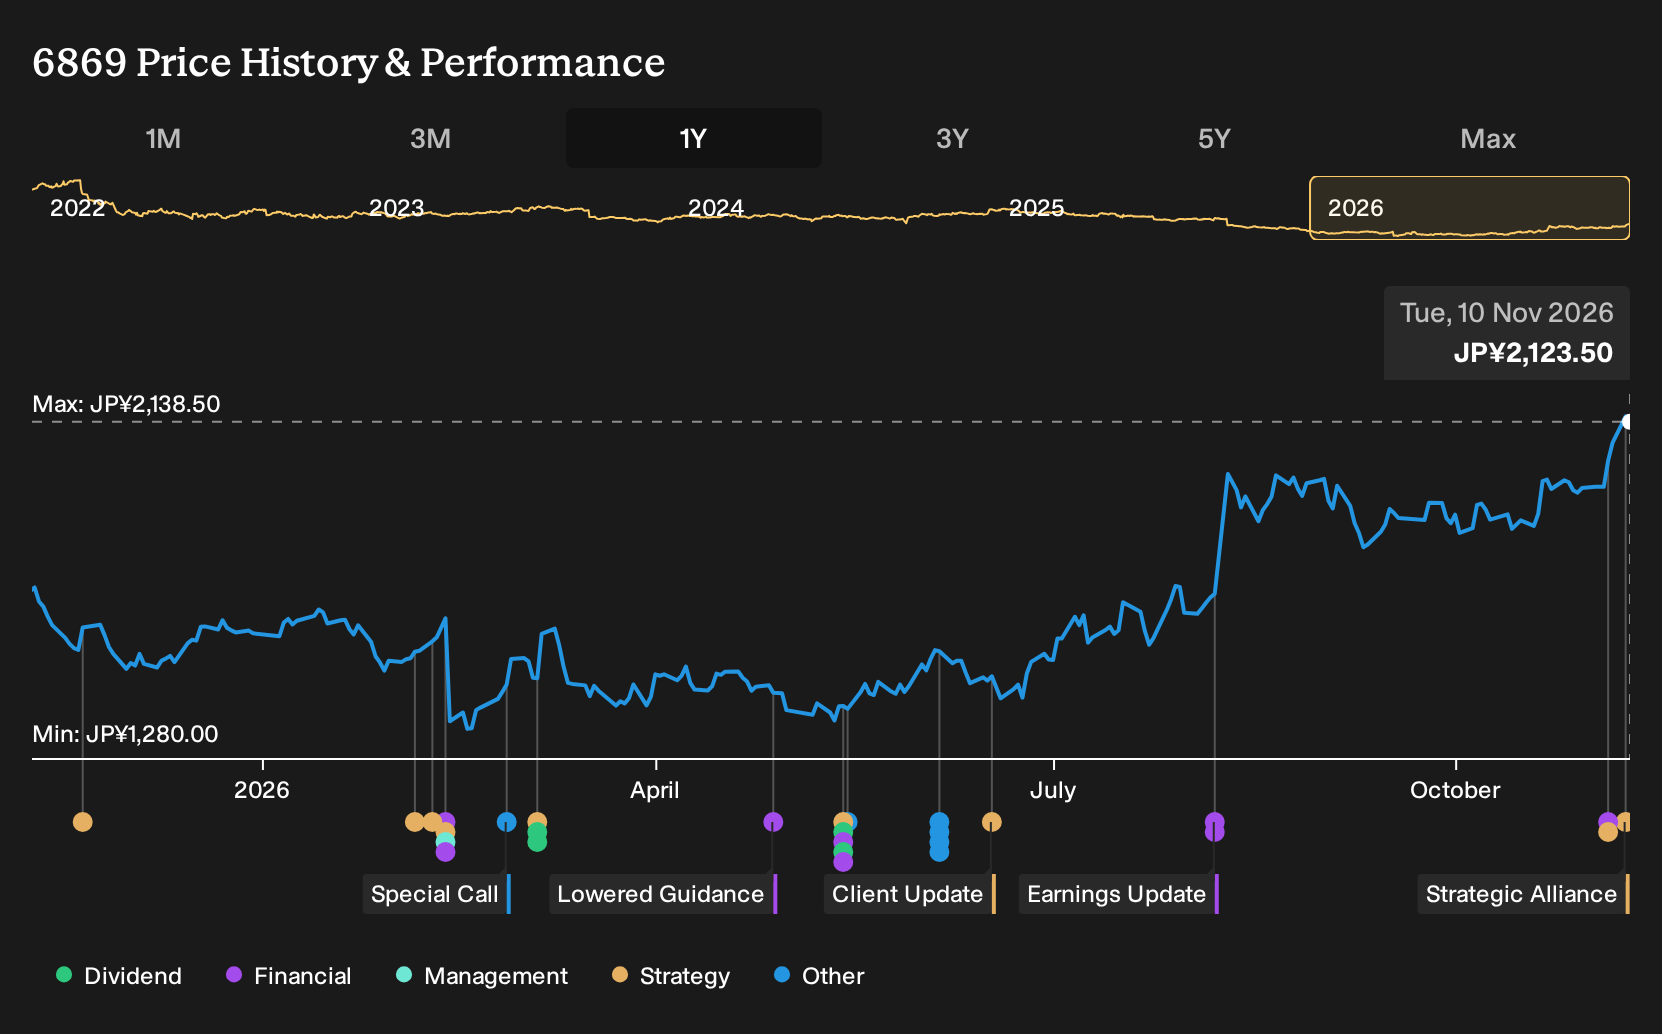
- Sysmex lifted its guidance for the six months to September 30, 2026, citing stronger operating results in the Americas, despite recording a JPY 5,769 million impairment tied to Sysmex BioMajesty.
- Hologen and Sysmex formed Saibogen to apply generative AI to hematology data, aiming to create software-based blood intelligence products delivered through existing analyzers without additional instruments or samples.
- Next, the focus will be on how Sysmex's higher earnings guidance, supported by strength in the Americas, reshapes the broader investment narrative.
Sysmex Investment Narrative Recap
To own Sysmex, you need to be comfortable with a diagnostics group that leans heavily on hematology systems, reagent pull through and regional expansion. The raised guidance for the half year points to a business that is currently executing well in the Americas, even while absorbing a sizeable impairment at Sysmex BioMajesty. The near term swing factor still looks like how efficiently those higher sales translate into cash.
The biggest operational risk right now is that portfolio clean up and heavier investment in direct sales, plants and clinical chemistry leave Sysmex with higher structural costs without enough high margin reagent volume. The impairment reinforces that concern but does not change it. Saibogen and the earnings upgrade both keep attention on whether management can rebuild trust after the prior midterm plan shortfall.
The Saibogen joint venture with Hologen is the announcement that most directly reshapes the story around Sysmex’s guidance upgrade. Management is trying to layer software and AI on top of the existing hematology installed base, using routine blood data without new hardware. That aligns with what the analyst consensus Narrative on Simply Wall St already frames as a reagent and recurring revenue centric model.
For you, the operational question is whether Saibogen can eventually deepen customer stickiness and support the hemostasis and hematology platforms in regions like the Americas and EMEA. Execution risk is real. The first Saibogen products are for research use only, so the near term catalyst remains core analyzer and reagent performance, while the AI effort remains a slower burn option on the existing footprint.
Sysmex's current analyst narrative points to revenues of ¥617.4b and earnings of ¥58.8b by 2029, based on an assumed 5.6% yearly revenue growth rate and an increase in profit from ¥39.6b today. This implies roughly a 1.5x earnings step up over that period.
Uncover why Sysmex's fair value is essentially aligned with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts frame Saibogen as a potential accelerator for Sysmex, not just a side project. Before this announcement, the bullish camp was already modeling revenue of about ¥674.4b and earnings near ¥75.8b by 2029. You can now weigh whether this AI push nudges those upbeat scenarios even higher or pulls them into question.
Explore 2 other Sysmex fair value estimates, including one that suggests it could be worth as much as ¥2189.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Sysmex research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Sysmex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Sysmex's overall financial health at a glance.
Looking For More Ideas Beyond Sysmex?
If the Sysmex story has sharpened your thinking around diagnostics and AI, it can be useful to cross check that view against other listed businesses using the Simply Wall St Screener.
- For investors who want quality at a sensible entry point, scan for companies that line up with your value criteria through the 20 high quality undervalued stocks.
- If capital preservation is high on your priority list, reduce left tail risk by filtering for businesses with steadier profiles using the 18 resilient stocks with low risk scores.
- When you want to back financially robust operators, sort for balance sheets and fundamentals that look resilient with the list of solid balance sheet and fundamentals (23 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com