


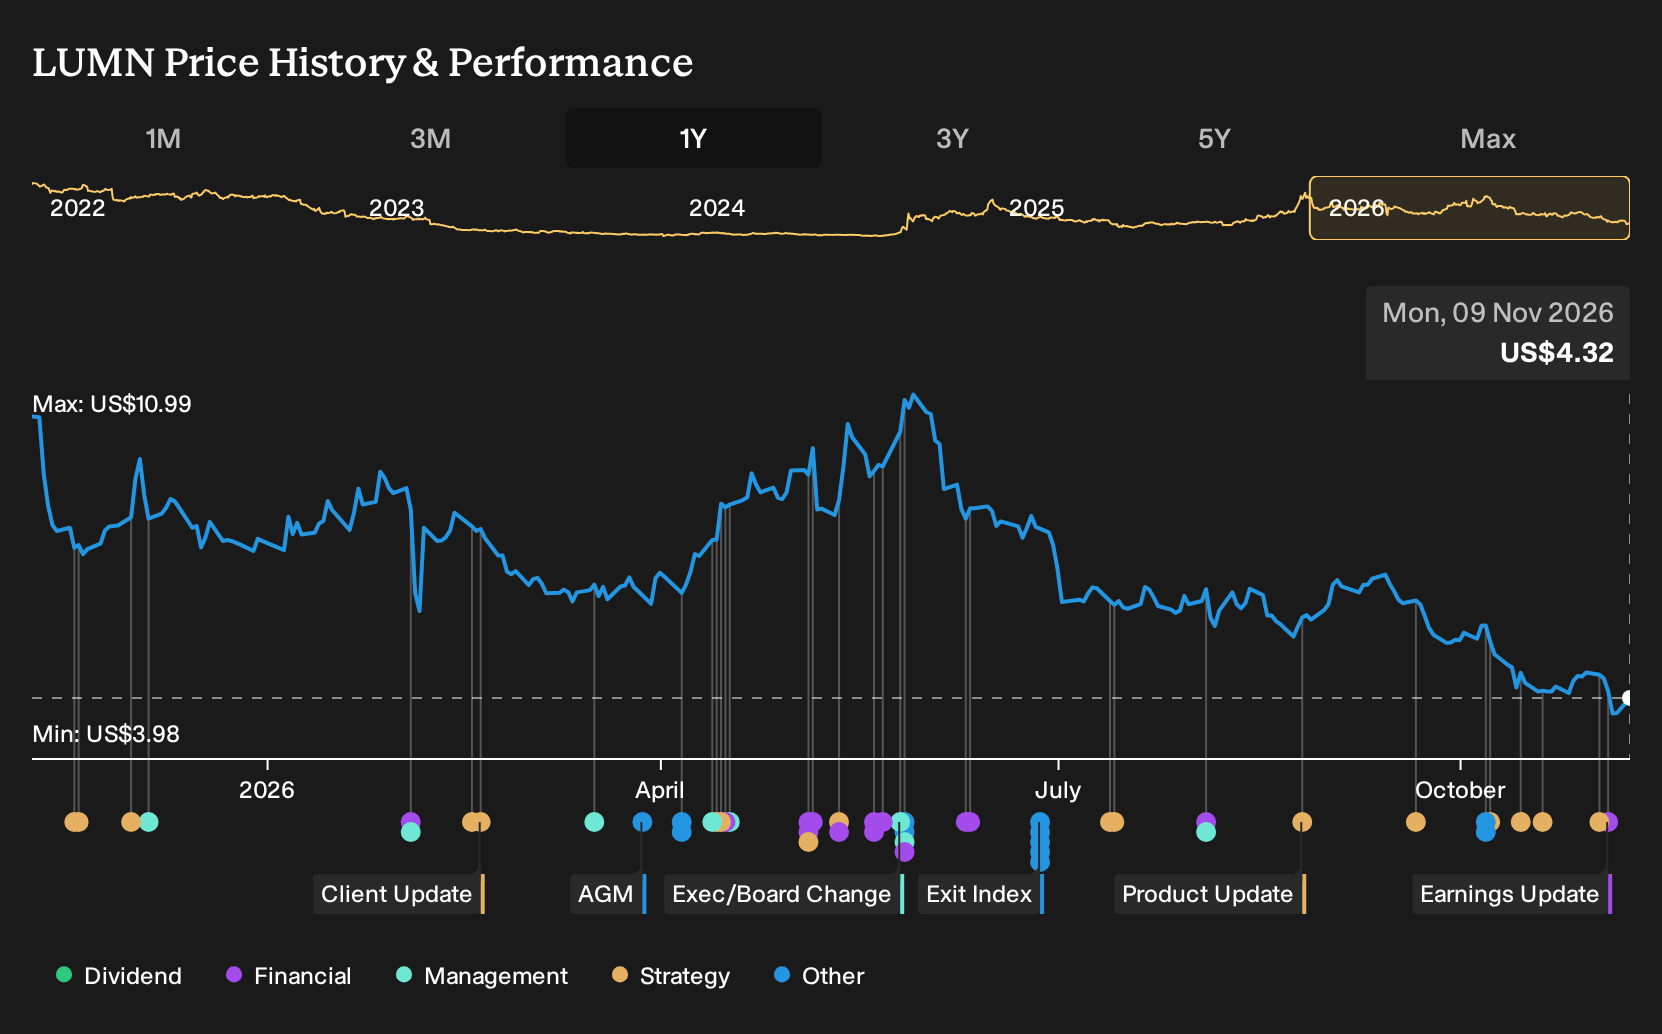
- Lumen Technologies reported Q3 2026 revenue of US$2.72b and a net loss of US$265m, while expanding its AI focused networking collaboration with Microsoft Azure for enterprise customers.
- The firm is placing greater emphasis on higher margin digital services, with private connectivity fiber contracts above US$13.5b and new co selling routes to market through Microsoft’s cloud ecosystem.
- This article now examines how Lumen Technologies' changing loss profile and AI focused Microsoft collaboration may influence its overall investment narrative.
Lumen Technologies Investment Narrative Recap
To own Lumen Technologies today, you need to believe the shift toward higher margin digital networking and AI ready connectivity can eventually matter more than shrinking legacy lines. Q3 2026 points in that direction, with a smaller net loss of US$265m and strategic services helping offset ongoing pressure on older products and voice.
The near term hinge is still execution on modernization and cost cuts, while funding about US$3b of annual CapEx and managing negative equity. The biggest risk remains that legacy revenue erosion and high investment needs keep squeezing cash, even as AI related demand and private connectivity contracts build in the background.
The expanded co selling collaboration with Microsoft Azure is the announcement that most clearly ties into this quarter. It plugs Lumen Technologies’ private connectivity fabric and Alkira based cloud networking into Microsoft’s distribution, giving enterprises a single way to treat networking, cloud migration, and AI workloads as one architecture instead of disconnected projects.
For potential catalysts, this matters because it can direct more AI heavy traffic onto Lumen’s US$13.5b plus of long term fiber commitments while using Microsoft Marketplace as an additional route to market. The operational risk is execution. Lumen needs to onboard customers smoothly, maintain performance, and convert that Azure aligned demand into durable cash generation.
Lumen Technologies' current earnings are a loss of US$1.0b, with analysts forecasting earnings of US$922.1m by 2029 on revenue of US$10.4b. This implies revenue is expected to decline 4.1% per year, and earnings would need to improve by roughly US$1.9b from today to reach that 2029 consensus level.
Uncover why Lumen Technologies' fair value indicates a 73% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You see one big fork in the story. Consensus focuses on slow revenue decline toward about US$10.4b and earnings of US$922.1m by 2029. The most optimistic analysts lean into Lumen Technologies’ AI partnerships and were already modeling roughly US$10.6b of sales and US$957.5m of earnings. Those views pre date this Azure news, so opinions may shift.
Explore 5 other Lumen Technologies fair value estimates, including one that suggests as much as 85% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Lumen Technologies research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Lumen Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Lumen Technologies' overall financial health at a glance.
Looking For More Investment Ideas Beyond Lumen Technologies?
If the Lumen Technologies story has you rethinking where you want AI, cash flow and balance sheet strength in your portfolio, it can help to widen the lens and compare it with other listed businesses using the Simply Wall St Screener.
- For investors who want potential upside but still care about quality and valuation checks, consider reviewing a curated set of 33 high quality undervalued stocks that may align more closely with your risk and return preferences.
- If consistent income sits high on your priority list, you can scan for companies classified as 6 dividend fortresses and then decide whether any fit your approach to yield and payout sustainability.
- When resilience and financial strength matter most, focus your search on our 30 resilient stocks with low risk scores to see which businesses the model tags with lower overall risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com