


Lincoln Electric Holdings (LECO) just released third quarter 2026 results, highlighting higher basic and diluted earnings per share from continuing operations compared with the same period in 2025, which puts profitability squarely in focus for shareholders.
Recent trading puts Lincoln Electric Holdings at a share price of $284.44, with a 1-day share price return of 3.30% and a 30-day share price return of 8.93%. The 1-year total shareholder return of 26.63% and 5-year total shareholder return of 109.94% point to momentum that long term holders will pay close attention to as they weigh these stronger earnings against what they believe the stock is already pricing in.
Scan how Lincoln Electric Holdings compares with other industrials showing strong profitability trends by reviewing the hand picked list of solid balance sheet and fundamentals (25 results) in the same toolkit.
After a quick jump on the earnings release, the question for Lincoln Electric Holdings is simple. Does paying up now for this profitability make sense, or does patience for a better entry look more attractive?
Most Popular Narrative: 9% Undervalued
Lincoln Electric Holdings is trading at $284.44 compared with a fair value estimate of $314.18 in the analyst consensus Narrative on Simply Wall St. This is built from aggregated earnings forecasts, margin assumptions and valuation inputs rather than a single opinion.
The RISE enterprise model targets a 300 basis point uplift in average operating margin and high-20s incremental margins by 2030 compared with prior cycles. This provides Lincoln Electric Holdings with a potential path to structural efficiency gains, which could support higher net margins and earnings over time.
See why 8 investors see Lincoln Electric Holdings as 9% undervalued.
Result: Fair Value of $314.18 (UNDERVALUED)
Still, the bullish Lincoln Electric Holdings story can fray if inflation pressures squeeze pricing power or if weaker automotive demand keeps consumable volumes under strain.
Find out about the key risks to this Lincoln Electric Holdings narrative.
Another View: Lincoln Electric Holdings Through A P/E Lens
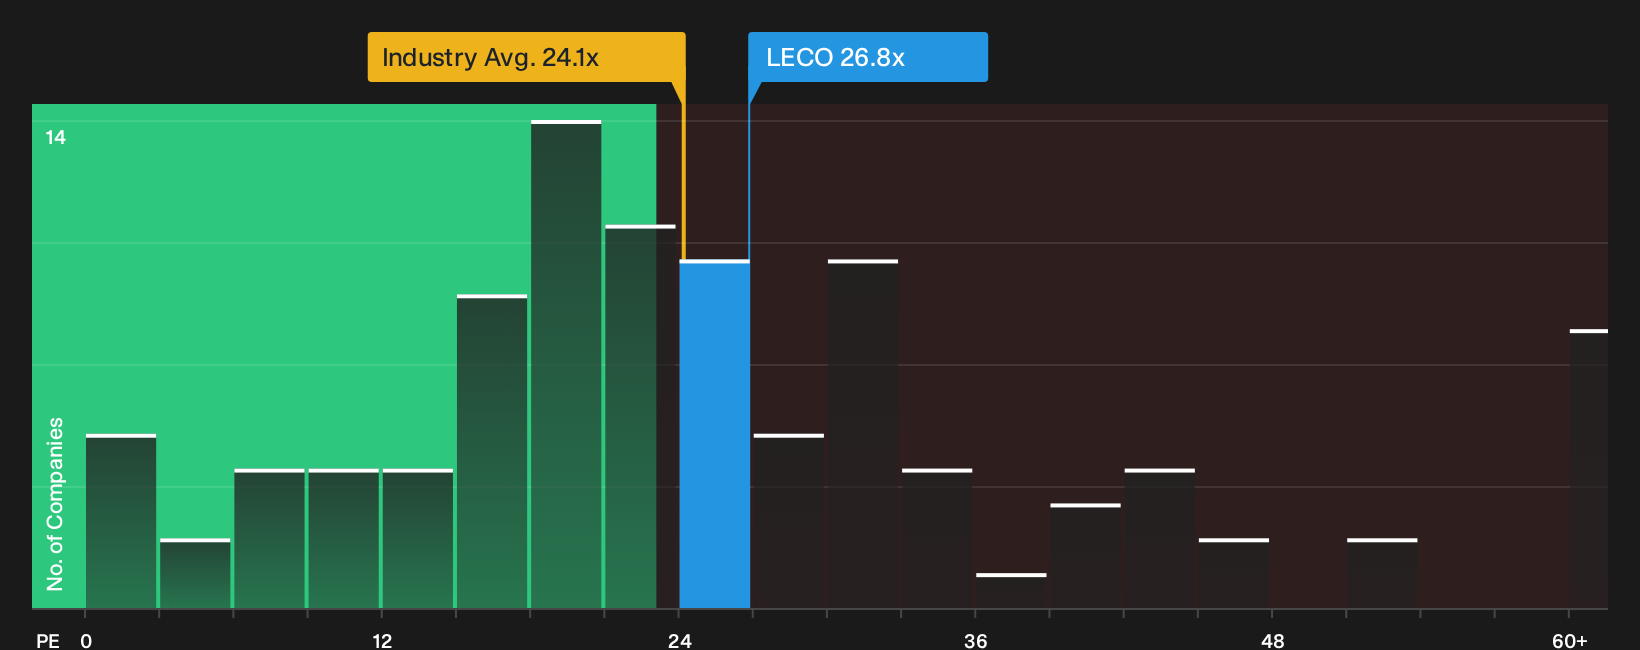
The SWS DCF model suggests Lincoln Electric Holdings trades about 32.1% below an estimated future cash flow value, which points to an undervalued picture. The P/E ratio tells a different story. At 26.8x, it is richer than the US Machinery industry on 23.2x and above a fair ratio of 22.8x, even though it sits below a 32.4x peer average. That mix indicates potential upside if the market moves toward the peer group and potential downside if pricing shifts back toward the fair ratio. This raises the question of which anchor to treat as more important when sizing a position.
For a closer look at how this pricing gap aligns with earnings power and risk, review the See what the numbers say about this price — find out in our valuation breakdown. and compare Lincoln Electric Holdings with other industrials facing similar trade offs.
Next Steps
Mixed messages on value and risk can be a good thing. They force you to move beyond headlines, act while information is fresh, and test the 3 key rewards and 1 important warning sign.
Looking for more Lincoln Electric Holdings style investment ideas?
If this earnings story has you energised, do not stop with Lincoln Electric Holdings. Use the Simply Wall St screener toolkit to surface other focused opportunities that could suit your plan.
- Target steadier compounding by scanning a curated 30 resilient stocks with low risk scores that screens for resilience when markets turn choppy.
- Hunt for better value by reviewing a hand picked 19 high quality undiscovered gems that highlights quality businesses the crowd has not fully embraced yet.
- Strengthen portfolio foundations by checking the 6 dividend fortresses that focuses on companies combining meaningful income with more durable fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com