


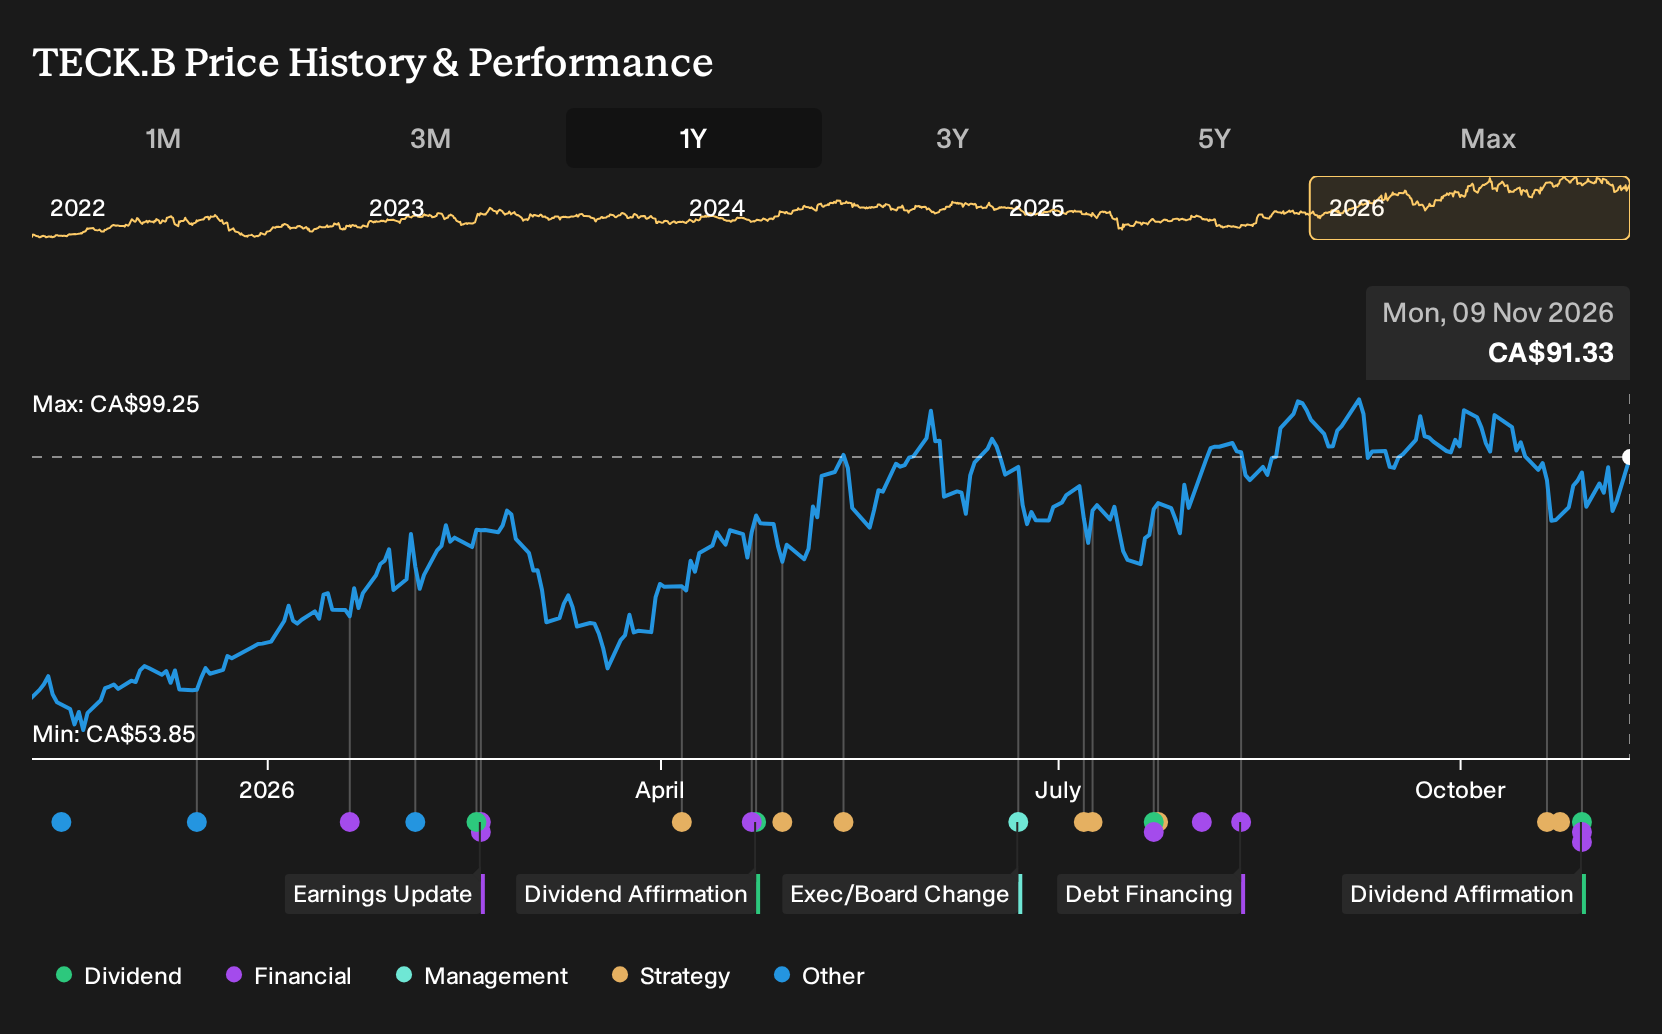
- Teck Resources reported third quarter 2026 sales of C$4,517 million and net income of C$1,592 million, alongside copper production of 115,700 tonnes, and affirmed a C$0.125 per share dividend payable on December 31, 2026, to shareholders of record on December 15, 2026.
- Copper volumes grew across almost all operations despite extreme weather at Carmen de Andacollo, highlighting how Teck Resources maintained production and earnings while dealing with real world operating disruption.
- Now the focus shifts to how Teck Resources' copper output and earnings profile might influence the existing investment narrative around its growth plans.
Scan how Teck Resources stacks up against other copper focused plays by reviewing our hand picked 16 top copper producer stocks alongside this latest earnings and dividend update.
Teck Resources Investment Narrative Recap
Teck Resources appeals to investors who want exposure to copper-focused growth projects alongside a portfolio that still generates cash today. To stay comfortable as a shareholder, you need to believe the firm can keep ramping copper output at assets like Quebrada Blanca while managing high 2026 capex and softer zinc economics.
The latest quarter showed Teck Resources handling extreme weather at Carmen de Andacollo while still lifting copper volumes and earnings. That supports the near term catalyst around cost control and higher copper production. The biggest risk remains execution on large projects and tailings work, where overruns or delays could squeeze free cash flow.
The most relevant update here is the third quarter earnings release. Sales of C$4,517 million and net income of C$1,592 million, alongside 115,700 tonnes of copper production, point to an operation that is currently running with strong profitability and scale. That matters because the analyst consensus Narrative on Simply Wall St leans heavily on copper-driven cash generation.
Stronger earnings and higher copper volumes give Teck Resources more room to fund projects like the Highland Valley Copper life extension and ongoing Quebrada Blanca work without relying as heavily on new funding. That supports the main copper growth catalyst while partially offsetting risk from elevated 2026 capex and weaker zinc volumes and unit costs.
Teck Resources' current analyst narrative points to CA$15.9b in revenue and CA$2.2b in earnings by 2029, built on 1.8% yearly revenue growth and an earnings decline of CA$1.6b from CA$3.8b today.
Uncover why Teck Resources' fair value indicates a 4% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts frame the Anglo Teck merger itself as the key catalyst. Before this latest Teck Resources earnings and dividend news, that bullish camp was working off forecasts of about CA$17.3b in 2029 revenue and CA$3.2b in earnings. You can compare those upbeat assumptions with your own view and see how opinions might shift from here.
Explore 4 other Teck Resources fair value estimates, including one that suggests potential upside of as much as 37% from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Teck Resources research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Teck Resources. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Teck Resources' overall financial health at a glance.
Looking for more Teck Resources sized investment ideas?
If this Teck Resources update has sharpened your view on copper, use the Simply Wall St Screener to size up other opportunities that fit your risk profile and income goals.
- For investors who want resilience first and returns second, start with a set of 9 resilient stocks with low risk scores that score well on overall risk metrics.
- If capital preservation and clean balance sheets matter most to you, focus on our list of solid balance sheet and fundamentals (5 results) to see which businesses pair financial strength with fundamental support.
- When you are aiming for growth potential the market may be overlooking, scan the 7 high quality undiscovered gems that combine quality markers with relatively low current attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com