


Earnings rebound puts Albemarle in focus
Albemarle (ALB) is back on many investors’ screens after third quarter results showed a swing from loss to profit, with higher sales and positive earnings per share reshaping how the market may view the stock.
The quick rebound in earnings comes after a tougher stretch for Albemarle shareholders. The 7-day share price return of 9.45% contrasts with a year-to-date share price decline of 31.13% and a 5-year total shareholder return that is down 61.16%.
Scan Albemarle’s rebound in context and size up other potential turnaround plays with the hand picked 33 high quality undervalued stocks that are drawing attention after fresh earnings shifts.
The sharp earnings recovery at Albemarle and the 7 day bounce in the share price tell different stories. Are you looking at a real business reset, or just sentiment snapping back after a rough stretch?
Most popular Albemarle narrative: 36% undervalued
Albemarle last closed at $99.12, while the analyst consensus Narrative on Simply Wall St points to a fair value of $154.68 based on discounted future cash flows using a 7.53% discount rate. That gap frames Albemarle as materially undervalued in that Narrative and sets up a very earnings focused view of where the lithium specialist could go from here.
The company is executing aggressive cost reduction and productivity initiatives (achieving a $400M annual run-rate in savings, 6 months ahead of plan), ramping low-cost asset expansions, and optimizing its conversion network. This is likely to structurally reduce operating costs and increase net margins in a lower price environment.
See why 196 investors see Albemarle as 36% undervalued.
Result: Fair Value of $154.68 (UNDERVALUED)
Still, the Albemarle narrative breaks quickly if lithium prices stay weak for years or if geopolitical and regulatory setbacks disrupt key Chile and China operations.
Find out about the key risks to this Albemarle narrative.
Another view on Albemarle’s valuation
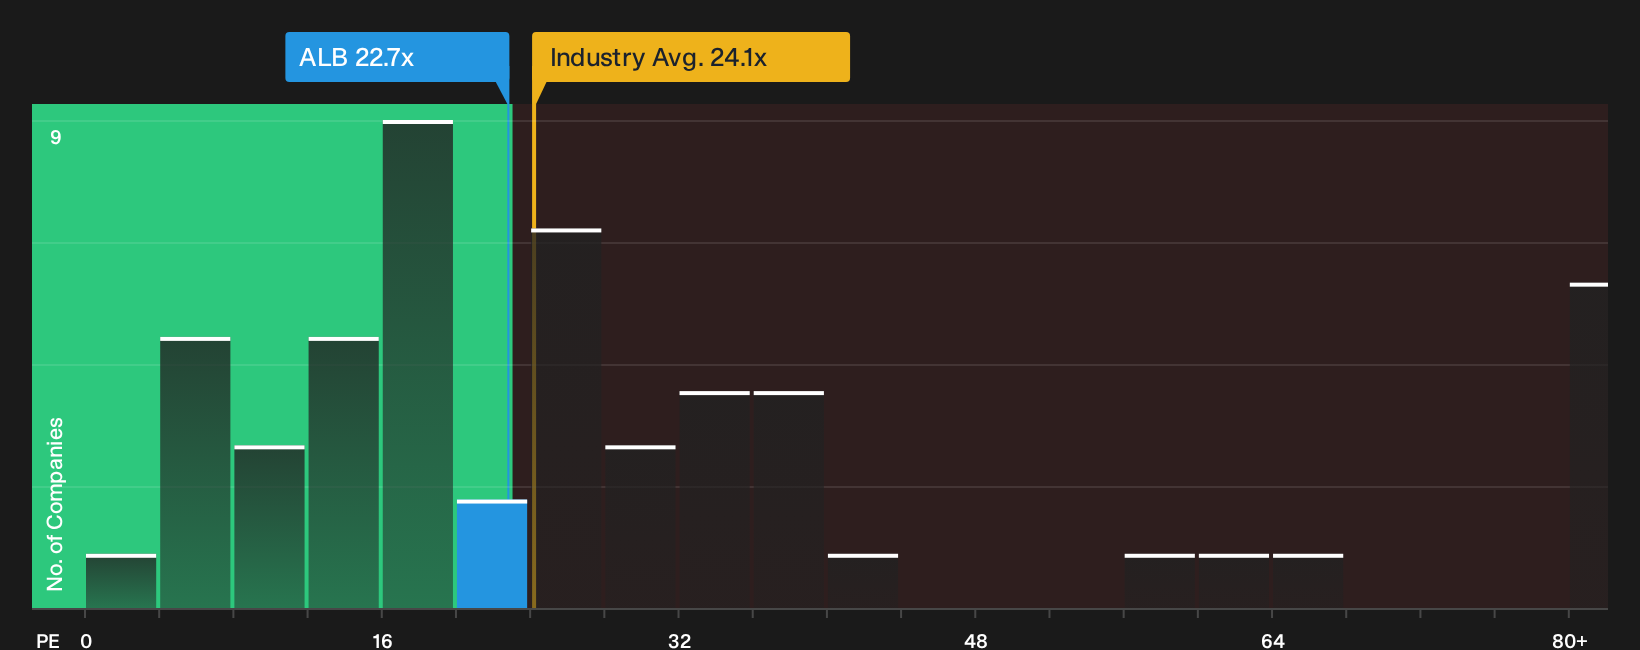
On simple earnings multiples, Albemarle looks less clear cut. The P/E sits at 22.7x, which is higher than the 16.9x peer average, yet below the US Chemicals industry on 24.1x and below an estimated fair ratio of 26.7x. That mix points to both valuation risk and potential catch up. Which side do you think matters more for your thesis?
See what the numbers say about this price in more detail with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the Albemarle story feels finely balanced between concern and optimism, consider moving quickly, work through the data yourself, and weigh both sides. Then let the full picture of risks and potential upsides guide your decision with 4 key rewards and 1 important warning sign.
Looking for more Albemarle style investment ideas?
Do not stop with Albemarle. The best opportunities often come from comparing several strong candidates side by side using clear, consistent criteria.
Use the Simply Wall St Screener to uncover more possibilities that could fit your approach and avoid leaving attractive ideas on the table.
- Target underpriced quality by scanning the 33 high quality undervalued stocks that combine solid fundamentals with room for sentiment to catch up.
- Build income resilience by focusing on companies in the 6 dividend fortresses that offer higher yields with supporting financial strength.
- Reduce portfolio stress by concentrating on the 30 resilient stocks with low risk scores that show stronger balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com