


Why LTC Properties’ Latest Earnings Matter For Investors
LTC Properties (LTC) just posted third quarter and nine month 2026 figures that reshaped its income statement, backed up by reaffirmed full year earnings guidance and a clear push toward seniors housing operations.
The real estate investment trust reported third quarter sales of US$98.04 million and revenue of US$115.25 million, alongside net income of US$348.15 million compared with a loss in the same quarter last year.
For the first nine months of 2026, LTC Properties recorded sales of US$256.09 million and revenue of US$309.52 million, with net income of US$401.38 million compared with a smaller profit a year earlier.
Earnings per share reflected the shift in performance. Basic EPS from continuing operations reached US$6.44 for the quarter and US$7.77 for the nine month period, with diluted EPS at US$6.39 and US$7.70 respectively.
Management kept full year 2026 diluted earnings guidance in a narrow range of US$8.08 to US$8.10 per share. This gives investors a reference point when comparing the latest reported numbers with expectations for the rest of the year.
LTC Properties’ latest report lands after a strong run in the market, with the share price up 18.03% over 90 days and a 29.81% year to date share price return, while total shareholder return over five years sits at 79.92%. Investors are now weighing this momentum against the reaffirmed earnings guidance and the recent senior leadership addition in corporate finance and investor relations.
Spot similar REIT momentum by comparing LTC Properties with a curated 33 high quality undervalued stocks that pairs income potential with balance sheet strength.LTC Properties has just logged a sharp run in both earnings and the share price, so the real question now is whether the current valuation still leaves enough upside to justify the risk you are taking.
Price-to-Earnings of 5x for LTC Properties: Is it justified?
LTC Properties closed at $44.98, and on a P/E of 5x it screens as inexpensive compared with both its own fair ratio and the wider Health Care REITs group.
The P/E ratio compares what investors are paying for each dollar of earnings, which can matter a lot for an income focused landlord like LTC Properties. A lower P/E can indicate the market is pricing in weaker future profits or elevated risk. A higher P/E suggests investors are comfortable paying more for earnings power.
Here, LTC Properties trades on a P/E of 5x against an estimated fair P/E of 12.5x. It also trades against a Global Health Care REITs average of 18.2x and a peer average of 41.9x. That is a steep gap, and it points to a situation where the market has assigned a heavy discount relative to both sector norms and the level the fair ratio indicates the multiple could move toward if sentiment or earnings quality shifted.
Explore the SWS fair ratio for LTC Properties.
Result: Price-to-Earnings of 5x (UNDERVALUED)
Still, LTC Properties faces real pressure points, including annual net income growth that currently trends lower and concentration in a single country and sector.
Find out about the key risks to this LTC Properties narrative.
Another View On LTC Properties’ Value
The P/E gap already looks wide, and our DCF model goes further and values LTC Properties at about $74.93 per share versus the current $44.98 price. That points to a large implied discount. The real question is how comfortable you are with the assumptions that sit inside that cash flow curve.
Look into how the SWS DCF model arrives at its fair value.
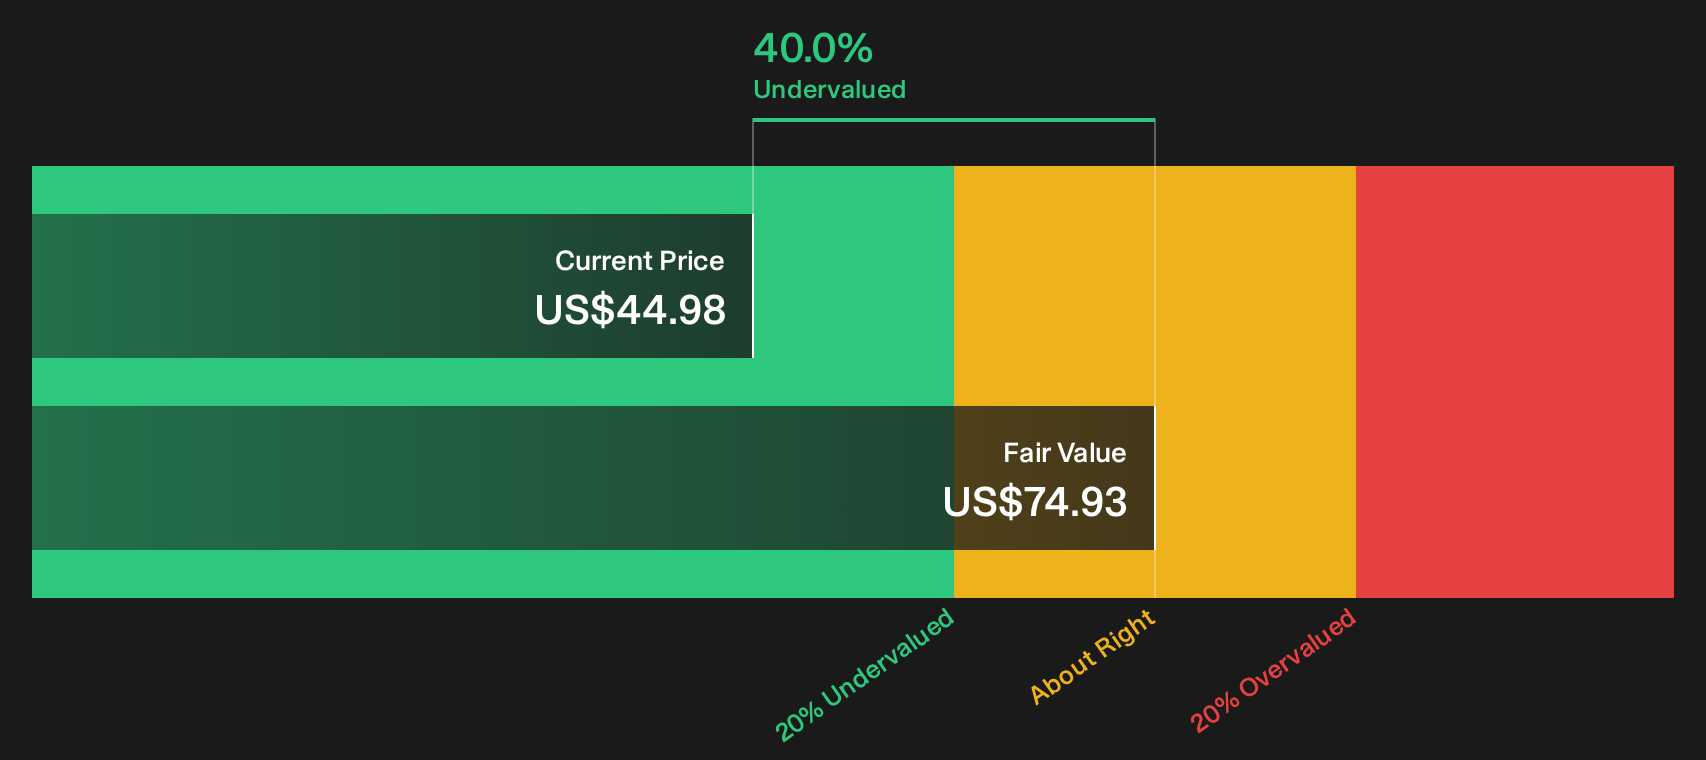
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out LTC Properties for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
After all of this around LTC Properties, the real test is your own conviction. Move fast, stress test the thesis, then weigh the 5 key rewards and 4 important warning signs.
Looking For More Investment Ideas Beyond LTC Properties?
If LTC Properties has sharpened your focus on value, do not stop here. Broaden your watchlist now so you are not chasing opportunities after they move.
- Target dependable balance sheets by scanning a list of solid balance sheet and fundamentals (25 results) that filters for financial strength and fundamentals that can support long term plans.
- Hunt for mispriced potential using a curated 19 high quality undiscovered gems that highlights quality businesses the wider market may not yet be watching closely.
- Prioritise capital protection by reviewing a 30 resilient stocks with low risk scores built to spotlight companies with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com