


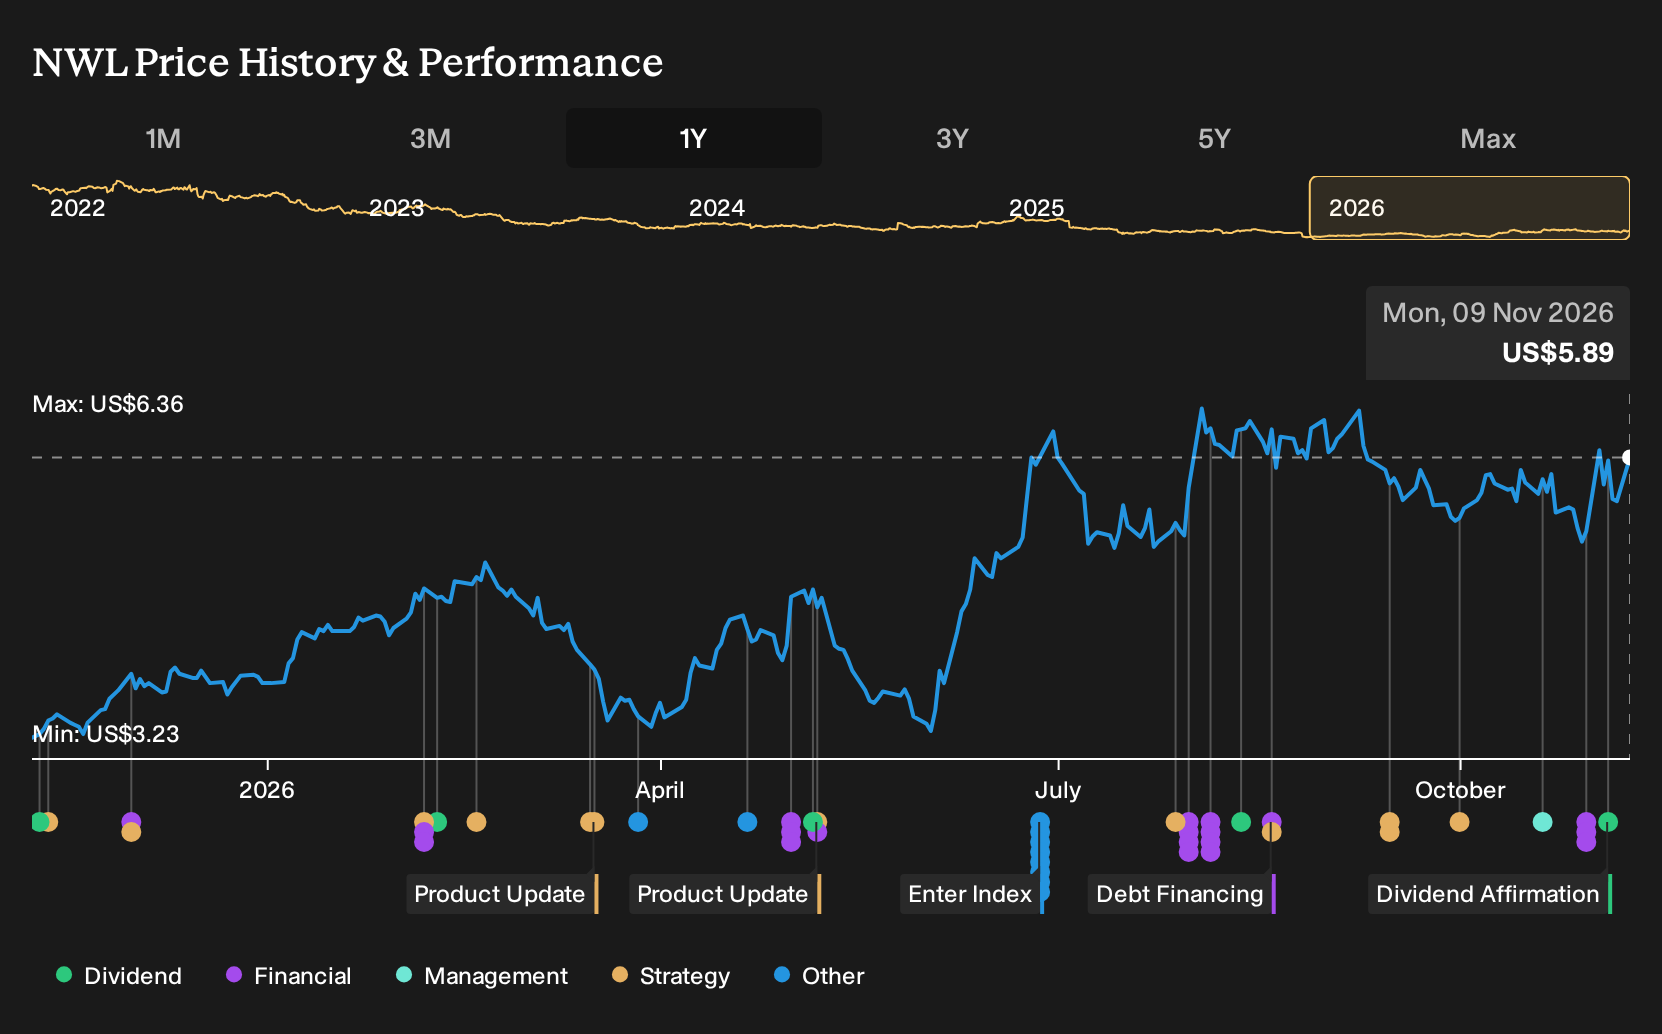
- Newell Brands reported third quarter 2026 sales of US$1,873 million and a net loss of US$81 million, affirmed a quarterly dividend of US$0.07 per share, and previously announced the upcoming addition of former Constellation Brands CEO Bill Newlands to its board effective January 1, 2027.
- The combination of ongoing dividend payments, raised full year 2026 net sales guidance, and an incoming director with experience in consumer brands and capital allocation shows how Newell Brands is seeking to balance near term earnings pressure with longer term execution on its turnaround plan.
- The next step is to consider how Newell Brands' raised 2026 sales guidance could influence the broader investment narrative around its turnaround.
Newell Brands Investment Narrative Recap
For an investor to stay with Newell Brands right now, the core belief is that the turnaround can convert modest top line progress into healthier margins and better cash generation once temporary items wash through. The raised 2026 net sales outlook points to slightly firmer demand, but the recent quarterly net loss keeps execution on productivity and mix the main short term catalyst.
The biggest near term risk sits in cash flow and cost pressure. Management now anticipates about US$150 million in 2026 operating cash flow instead of about US$400 million, while inflation of roughly US$370 million across 2026 and 2027 still needs offsetting. If the FUEL and PEAK savings or pricing actions underdeliver, leverage and earnings pressure could linger.
The most relevant piece of recent news for that thesis is the raised full year 2026 net sales growth guidance to 2% to 3%. It ties directly into what the analyst consensus Narrative on Simply Wall St highlights as key drivers, namely the rebuilt product development system producing around 25 large launches a year and a focus on higher value brands.
If core demand holds up around that guidance range, it gives Newell Brands more room to work on margins while absorbing higher input costs and lower receivables factoring benefits. If sales growth softens from here, inflation of US$150 million in 2027 on top of US$220 million in 2026 and the roll off of roughly US$100 million of tariff recoveries could quickly become more visible in earnings and keep leverage reduction slower than hoped.
Newell Brands' current analyst narrative points to forecast revenue of US$7.8b and earnings of US$522.8 million by 2029, based on an assumed 2.0% yearly revenue growth rate and an earnings swing of about US$845.8 million from a loss of US$323.0 million today to the forecast level.
Uncover why Newell Brands' fair value indicates a 9% potential upside to its current price before the gap closes.
Exploring Other Perspectives
One alternate view sees the dividend as the real pressure point for Newell Brands. The most cautious analysts were baking in only about US$7.5b of revenue and US$390.0 million of earnings by 2029 before this news. That is a far more constrained story than consensus. Use this board change and guidance upgrade as a prompt to compare a few different narratives yourself.
Explore 3 other Newell Brands fair value estimates, including one that suggests it could be worth just $6.41.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Newell Brands research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Newell Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Newell Brands' overall financial health at a glance.
Looking For More Investment Ideas Beyond Newell Brands?
If Newell Brands has you thinking about turnarounds, income streams, or balance sheet strength, it can help to line it up against other opportunities that share similar traits but face different sets of risks and potential rewards.
- For investors focused on resilient businesses that still look attractively priced, compare Newell Brands with a curated 33 high quality undervalued stocks that blend quality fundamentals with discounted valuations.
- If capital preservation and steadier risk profiles matter most to you, set Newell Brands alongside companies in our 30 resilient stocks with low risk scores and see how their volatility and financial risk stack up.
- When balance sheet strength is the priority, measure Newell Brands against firms in a list of solid balance sheet and fundamentals (25 results) that pair conservative leverage with robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com