


- Bayer received U.S. FDA approval for SUNHARBO 50 mg, a once-daily Factor XIa inhibitor used with antiplatelet therapy to reduce ischemic stroke risk after recent non-cardioembolic stroke or high-risk TIA, based on the Phase 3 OCEANIC STROKE trial of 12,327 patients.
- The SUNHARBO decision gives Bayer a first-in-class anticoagulant in the U.S., adding a new branded therapy to support its pharmaceuticals mix while carrying clear safety management needs around gastrointestinal bleeding, liver enzyme elevations and drug interactions.
- The focus now turns to how Bayer’s investment narrative around pipeline-driven earnings quality could be affected by SUNHARBO’s first-in-class approval.
Bayer Investment Narrative Recap
To hold Bayer, an investor needs to believe the pharma pipeline can steadily rebalance the group while Crop Science efficiency work and litigation containment improve cash generation. The analyst consensus Narrative on Simply Wall St highlights that earnings are forecast to grow, but the recent approvals only matter if they translate into disciplined execution and cleaner free cash flow.
The SUNHARBO launch fits that story but does not immediately change the biggest swing factors. Litigation payouts, large capital projects like the Ohio plant and Crop Science restructuring remain the key short term risk and catalyst pair. Q4 cash flow and 2027 guidance are likely more important than any single drug win.
The SUNHARBO approval lines up directly with that pharma renewal theme. Bayer now has a first in class Factor XIa inhibitor in U.S. stroke prevention, on top of KERENDIA extensions and oncology assets. This gives the pharmaceuticals portfolio a clearer set of fresh products while older therapies face pressure and the group works through restructuring.
Sevabertinib’s approvals in China, the U.S. and Japan for HER2 mutant NSCLC pull in the same direction. Together with SUNHARBO, they increase operational complexity, from safety monitoring to post marketing commitments and trial readouts. At the same time, they sit among the clearest operational catalysts investors can watch alongside litigation cash outflows and Crop Science margin progress.
Bayer’s current narrative points to revenues of €49.0b and earnings of €3.7b by 2029, based on analyst forecasts. This setup assumes annual revenue growth of 2.6% and an earnings change of €5.4b from a loss of €1.7b today to the projected profit level.
Uncover how Bayer's fair value indicates a 3% potential upside to its current price, even before the discount becomes less apparent.
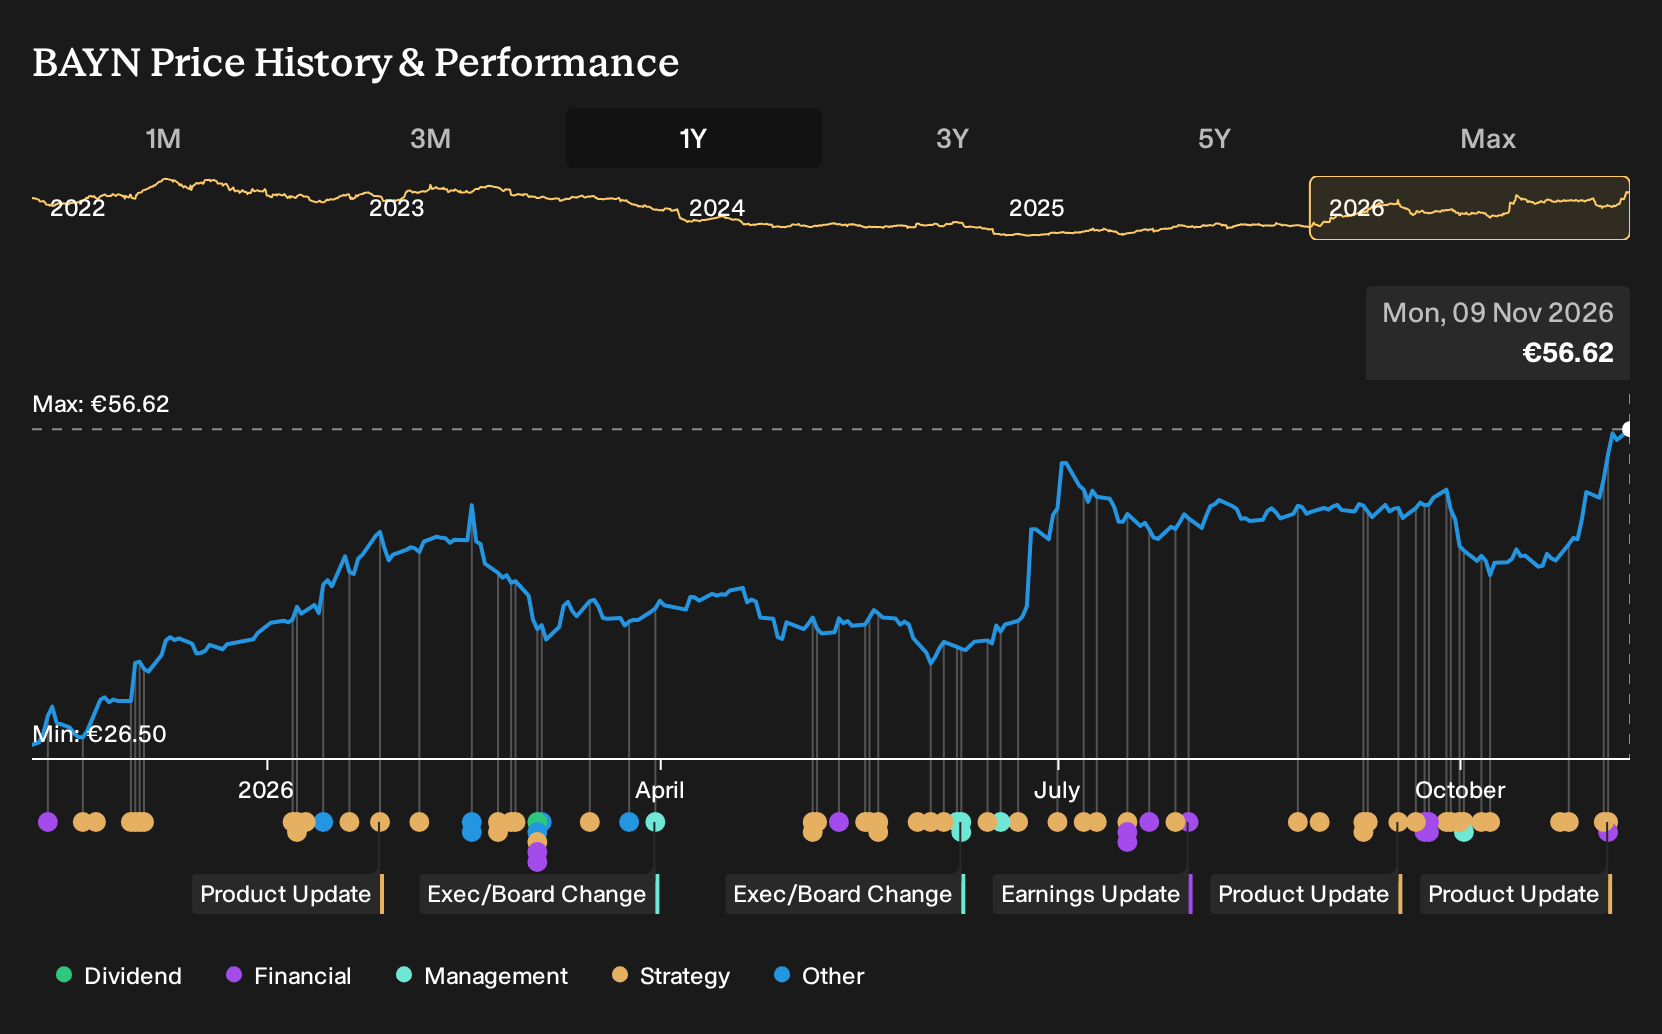
Exploring Other Perspectives
One bearish twist you might want to weigh is litigation cash drain. The most pessimistic analysts were already assuming Bayer only reaches about €47.3b in revenue and €3.5b in earnings by 2029, with a €46.0 fair value. SUNHARBO’s approval could shift that story, or it could leave these concerns largely intact. Exploring both angles helps you frame your own view.
Explore 7 other Bayer fair value estimates, including one that suggests up to 92% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Bayer research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Bayer. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Bayer's overall financial health at a glance.
Looking for more investment ideas beyond Bayer?
If SUNHARBO has sharpened your interest in Bayer, it can be useful to compare that story with other businesses that fit different return and risk profiles using the Simply Wall St Screener.
- For potential mispriced opportunities with solid fundamentals, scan our 200 high quality undervalued stocks to see which companies currently trade below their assessed worth.
- If capital preservation matters most to you, consider our 203 resilient stocks with low risk scores which is aimed at businesses with more resilient financial and risk profiles.
- For investors hunting for future leaders before they gain wider attention, check out the 573 high quality undiscovered gems that combine strong metrics with lower market visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com