


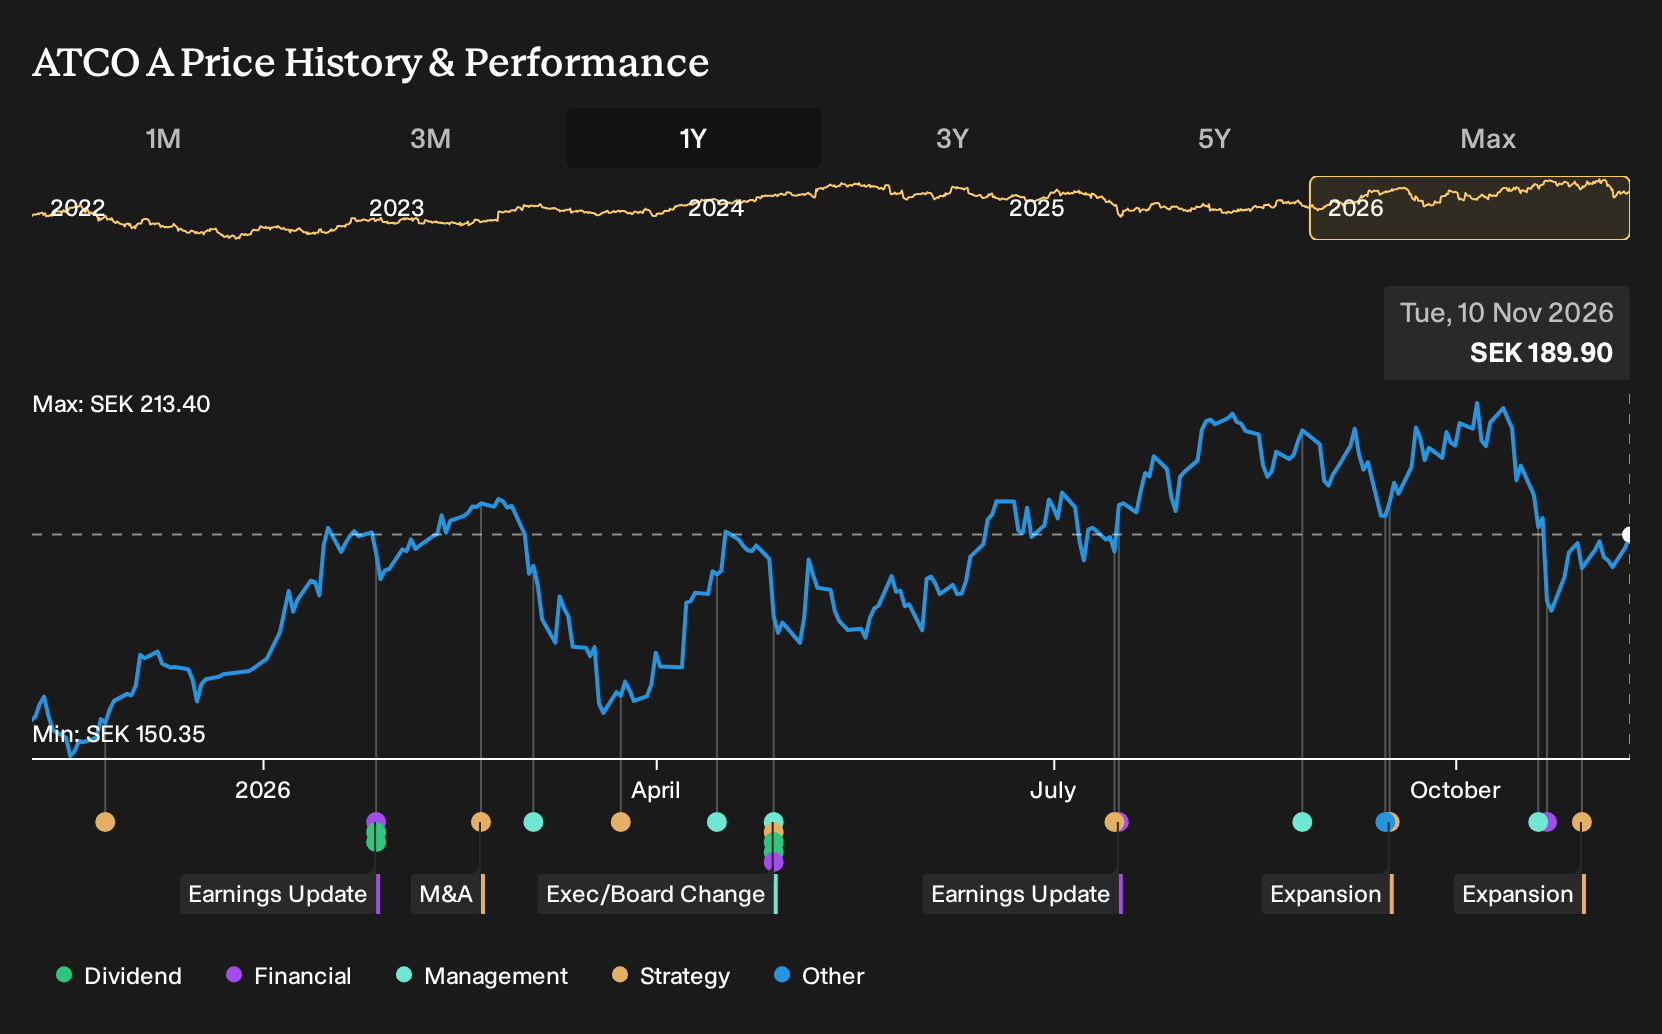
- Atlas Copco Group marked Expansion Week US in late October 2026 with three major US manufacturing projects across New York and South Carolina, adding hundreds of jobs and significant new capacity for oil free compressors, dry vacuum pumps, and gas and process equipment.
- The decision to assemble Z range oil free compressors and advanced vacuum pumps inside the US shifts more production closer to key customers. This may change Atlas Copco’s cost profile, supply resilience, and exposure to tariffs over time.
- We will now look at how Atlas Copco's US capacity build out, particularly for semiconductor vacuum pumps, feeds into the existing investment narrative.
Atlas Copco Investment Narrative Recap
To hold Atlas Copco, you need to be comfortable with a story built on semiconductor related demand, a growing service mix, and an active acquisition program, as set out in the analyst consensus Narrative on Simply Wall St. The US expansions tie directly into that, because extra compressor and vacuum pump capacity can support output where order books are already tight.
The key near term swing factor remains how efficiently Atlas Copco converts strong orders in Vacuum Technique and compressors into delivered equipment and recurring aftermarket work. The biggest risk still sits with cost pressure and integration friction, including tariffs, currency moves and acquisition related dilution, which these projects may not fully offset.
The Edwards Vacuum facility in New York, focused on advanced dry vacuum pumps for semiconductors, looks closest to the main catalyst around record semi related orders. Extra US capacity and hydro powered production can help Atlas Copco support fabs that need more tools and service contracts without stretching existing factories.
Execution at this plant will matter. Smooth ramp up, on time deliveries and reliable quality would support the view that Atlas Copco can handle factories needing to more than double output. Any delays or cost overruns would feed straight into the existing concerns about margin pressure, especially when P/E multiples are already above Swedish Machinery peers.
Atlas Copco's narrative projects SEK 240.6b revenue and SEK 42.9b earnings by 2029, which implies 12.3% yearly revenue growth and an earnings increase of about SEK 16.3b from current earnings of SEK 26.6b.
Uncover why Atlas Copco's fair value indicates a 21% potential upside to its current price before the discount narrows.
Exploring Other Perspectives
Some of the most optimistic Atlas Copco analysts focus on the US semiconductor buildout as the real swing factor. They were already modelling around SEK 270.2b of revenue and SEK 52.3b of earnings by 2029 before this Expansion Week news, so you can see how views differ and why it might be worth comparing several narratives yourself.
Explore 3 other Atlas Copco fair value estimates, including one that suggests as much as 25% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Atlas Copco research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Atlas Copco. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Atlas Copco's overall financial health at a glance.
Looking for more Atlas Copco style investment ideas?
If the Atlas Copco story has sharpened your thinking about quality, pricing power, and execution risk, it can be useful to widen the lens and compare it with other opportunities that share some of those strengths. The Simply Wall St Screener lets you filter for specific traits so you can build a watchlist that fits your own risk profile instead of relying only on one industrial stock.
- If resilience matters most to you, focus on companies that pair steady operations with lower risk scores and start with 204 resilient stocks with low risk scores.
- If you want strong balance sheets that can handle rough patches, look for businesses with solid finances and run a search using the list of solid balance sheet and fundamentals (195 results).
- If you are hunting for opportunities that the market may have overlooked, scan for underfollowed quality with the 568 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com