


- Burberry Group continues to push its Timeless British Luxury positioning by leaning into digital commerce, owned retail and higher full price sales, supported by AI enabled clienteling tools to improve operating efficiency.
- The brand’s role in the European Accelerator’s new Decarbonisation Accelerator Framework, including supplier self assessment and renewable energy feasibility work in Italy, signals a focus on supply chain emissions that could matter for long term luxury positioning and costs.
- We will now look at how Burberry’s push into higher margin direct to consumer sales could influence the broader investment narrative.
Burberry Group Investment Narrative Recap
For Burberry Group, the core belief is that the Timeless British Luxury refresh can support higher full price sell through and a richer direct to consumer mix. The recent push into digital commerce and owned stores keeps that thesis intact in the near term. The most important short term catalyst still sits in rebuilding gross margin and proving that higher margin channels can offset ongoing cost pressure.
The key risk has not shifted much. Softer luxury demand and weaker licensing, including fragrance destocking, could limit revenue progress if trends persist. Cost inflation around store rollouts and digital investments could also weigh on the margin rebuild if sales productivity does not keep pace.
The most relevant development for this story is Burberry Group’s deeper focus on direct to consumer, combined with AI enabled clienteling tools in stores and online. That fits closely with the analyst consensus Narrative on Simply Wall St, which links higher full price sales and more efficient operations to an earnings ramp.
This same mix shift sits alongside the Decarbonisation Accelerator Framework work in Italy. Cleaner energy and more efficient suppliers may not move near term earnings, yet they speak to future cost and brand resilience. Both factors matter when you are weighing the durability of Burberry’s premium positioning against today’s margin and demand risks.
Burberry Group's narrative projects £2.8b revenue and £271.5 million earnings by 2029. This assumes 5.4% yearly revenue growth and an earnings increase of about £250 million from £21.0 million today.
Uncover why Burberry Group's fair value indicates a 14% potential upside to its current price, which could narrow quickly.
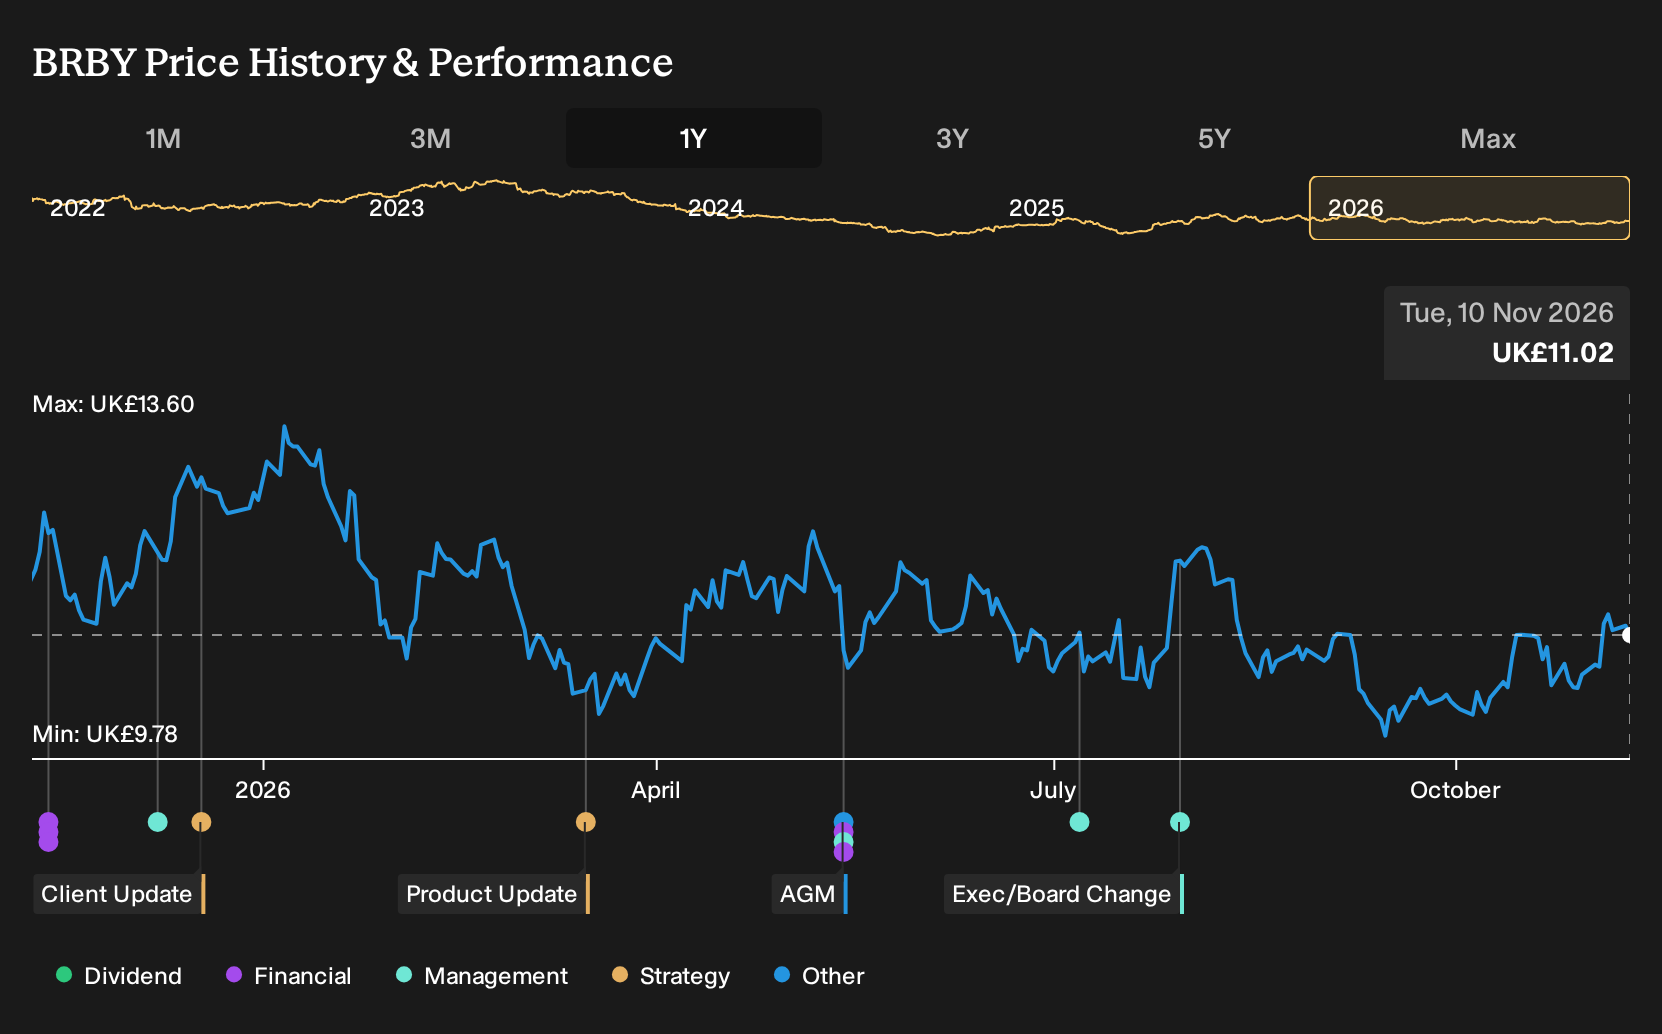
Exploring Other Perspectives
One bearish twist on Burberry Group focuses on the risk that weaker luxury demand and softer tourism leave new trench and scarf investments underused. That cohort was pencilling in revenue growth of 4.6% a year and earnings of about £227.6 million by 2029. These more cautious voices might rethink things after this news, just as you might when comparing different scenarios.
Explore 3 other Burberry Group fair value estimates, including one that suggests it could be worth just £12.51.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgment.
- A great starting point for your Burberry Group research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Burberry Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Burberry Group's overall financial health at a glance.
Looking for more Burberry Group style investment ideas?
If the Burberry Group story has you thinking about what else might fit your watchlist, the Simply Wall St Screener can help you cast a wider net while still keeping your criteria tight.
- If you want potential mispricing with solid fundamentals to back it up, start by scanning a focused set of 16 high quality undervalued stocks.
- For investors who care about balance sheet strength and staying power, filter for companies on the list of solid balance sheet and fundamentals (9 results).
- If resilience and steadier return profiles matter most to you, narrow your search to a group of 4 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com