


- OPC Energy reported third quarter 2026 sales of US$575 million and net income of US$100 million, with basic and diluted EPS from continuing operations at US$0.32, and nine month 2026 sales of US$1.271b and net income of US$124 million with EPS of US$0.40.
- The company paired these earnings figures with commentary about strong business momentum, supported by higher electricity demand and ongoing construction and financing progress on large power projects in the U.S. and Israel.
- We will look at how OPC Energy's investment narrative is shaped by this earnings step up and commentary on sustained electricity demand.
What Is OPC Energy's Investment Narrative?
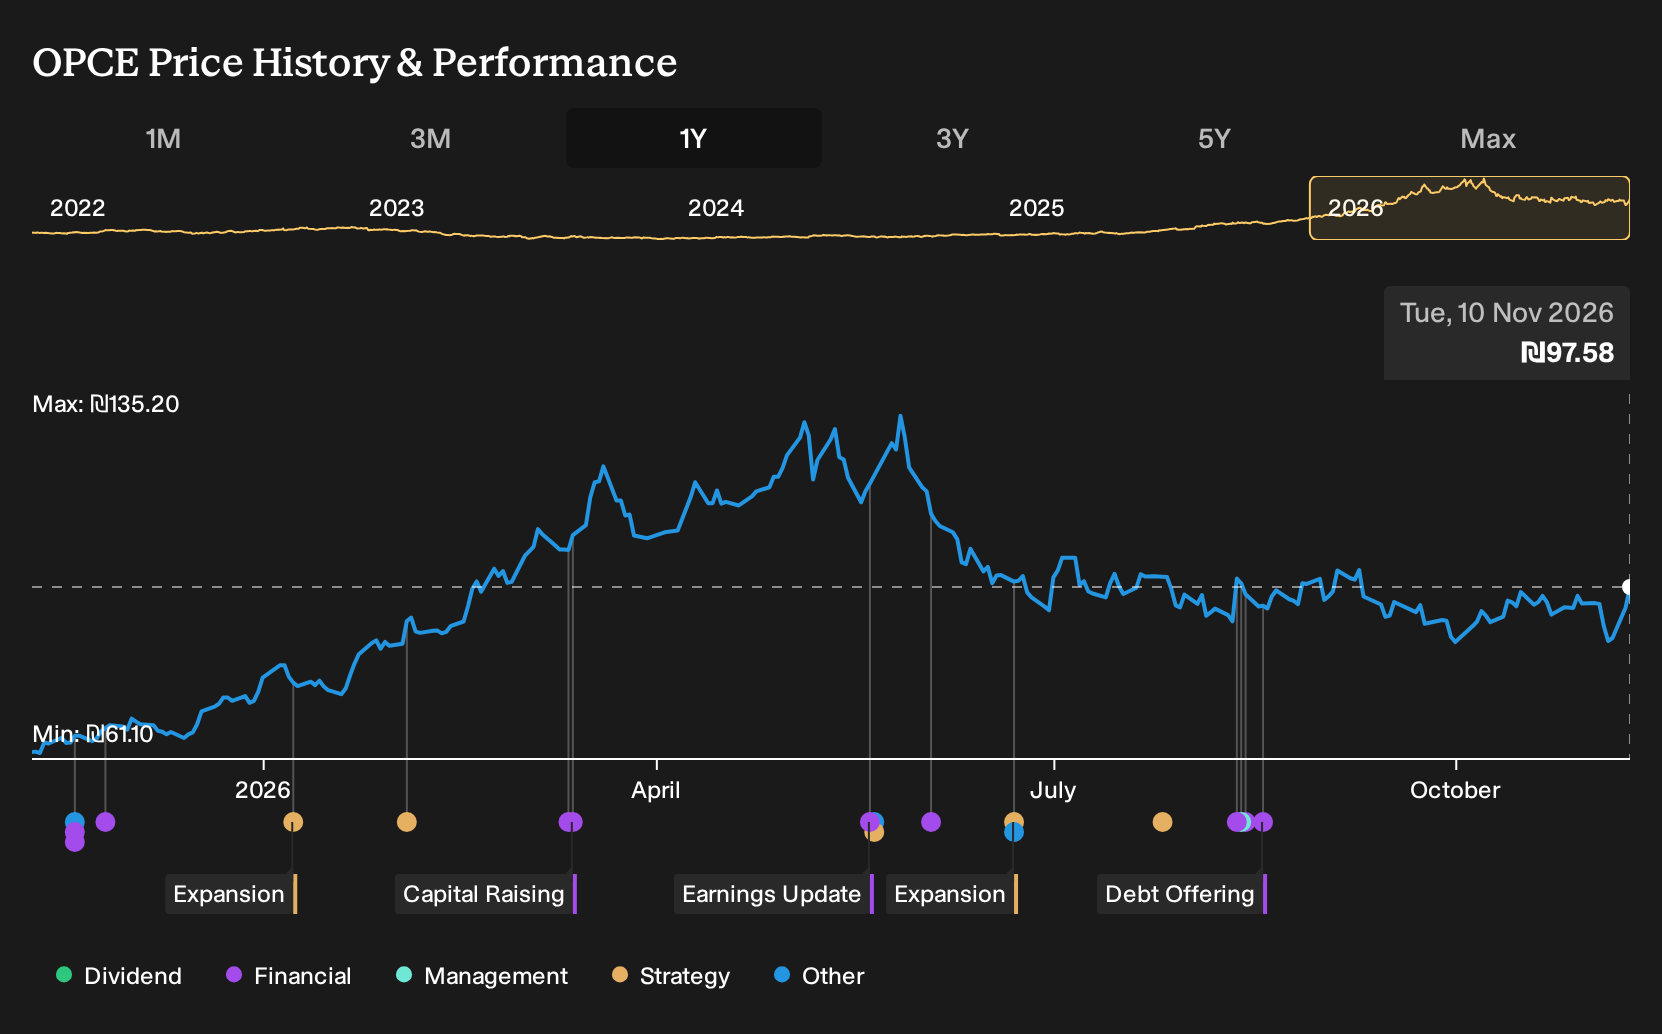
To own OPC Energy, you need to be comfortable with a capital hungry build out story that leans heavily on large U.S. and Israeli power projects and persistent electricity demand. The latest quarterly report, with US$575 million in sales and US$100 million in net income, indicates that the existing asset base is generating meaningful earnings while construction and financing work on projects like Ramat Beka and Shay continues in the background.
The immediate swing factors are execution on those large projects, the reliability of power plant operations, and how pricing and volumes in power markets evolve. Earnings growth over the past year has been strong. However, the stock trades on a P/E of 79.7x and interest costs are not well covered by earnings, so the bar for future cash generation is high and missteps on schedule, budget or refinancing would matter quickly.
Even so, there is one pressure point in the OPC Energy story that rarely gets top billing until you look closely at...
There's only one way to know the right time to buy, sell or hold OPC Energy. Head to Simply Wall St's company report for the latest analysis of OPC Energy's Fair Value.
Form Your Own Verdict
Disagree with this assessment? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your OPC Energy research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for OPC Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OPC Energy's overall financial health at a glance.
Looking for more investment ideas beyond OPC Energy?
If the OPC Energy story has you thinking about how to position your portfolio around different risk profiles and income streams, the Simply Wall St Screener can help you scan for other opportunities using the same data driven approach.
- If you want resilience to be the starting point, consider stocks highlighted in our 204 resilient stocks with low risk scores that may suit a more defensively minded approach.
- If reliable cash generation is a priority, income focused investors can review companies in the 217 dividend fortresses that match their yield and payout preferences.
- If you are hunting for under appreciated stories, look at the 568 high quality undiscovered gems that pair stronger fundamentals with less crowded investor attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com