


Frontier Group Holdings (ULCC) recently reported third quarter 2026 results that paired higher revenue with a wider loss, a combination that put profitability and cost pressures in sharp focus for investors.
Recent price action suggests investors are reassessing Frontier Group Holdings in light of the earnings update. A 1‑month share price return of 42.49% and year to date share price return of 82.71% point to strong positive momentum. That move sits alongside a 1‑year total shareholder return of 119.16% and a 3‑year total shareholder return of 139.94%. However, the 5‑year total shareholder return is down 50.06%, which shows how sharply sentiment around the stock has shifted more recently.
Scan how traders are reacting to Frontier Group Holdings and compare this surge with a curated list of 33 high quality undervalued stocks that also pair strong momentum with fundamental support.
After a run like Frontier Group Holdings has just logged, the real tension is simple. Is the big repricing already in the rear‑view mirror, or does the current valuation still leave meaningful upside on the table?
Most Popular Narrative: 26% Overvalued
On Simply Wall St, the analyst consensus Narrative on Frontier Group Holdings points to a fair value of $6.61 per share, which sits below the last close at $8.35 and presents the recent rally in the context of a more cautious long term valuation view built from detailed earnings and revenue forecasts using a 12.54% discount rate.
Execution on the multi-year cost and reliability program, including early return of 37 aircraft, planned maintenance savings of about US$400 million over five years, and a targeted mid US$0.07s stage-adjusted CASM ex-fuel by 2027, is intended to lift operating margins and narrow the gap between adjusted results and GAAP profitability.
Product upgrades such as first-class seating now being installed, strong paid load factors for the UpFront Plus extra-legroom product, and scheduled Starlink Wi-Fi rollouts from early 2027 are intended to increase ancillary and premium revenue per passenger and support both RASM and earnings.
See why 13 investors see Frontier Group Holdings as 26% overvalued.
Result: Fair Value of $6.61 (OVERVALUED)
Still, the Frontier Group Holdings story can break if fuel costs remain elevated or if persistent losses and tough funding conditions force equity dilution.
Find out about the key risks to this Frontier Group Holdings narrative.
Another View: Frontier Group Holdings On Sales-Based Valuation
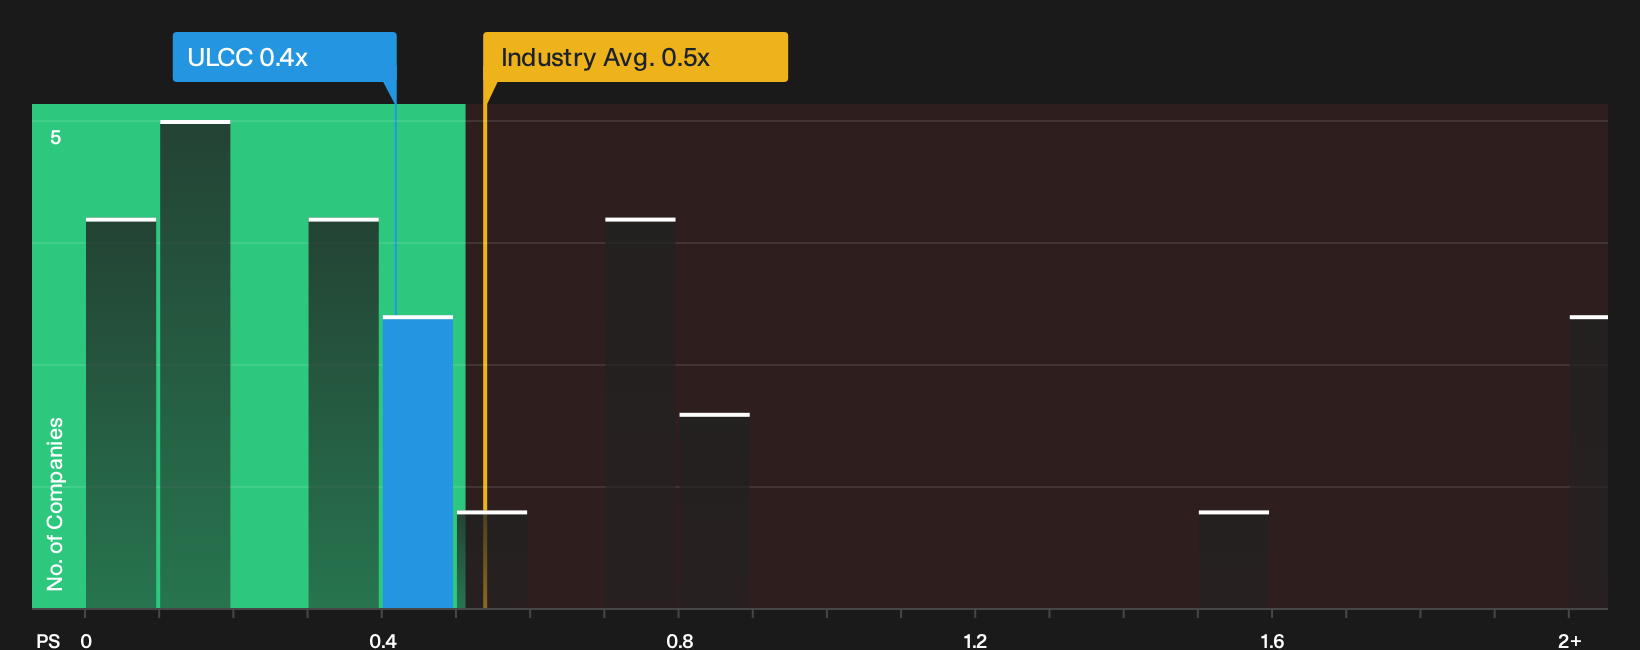
There is a split picture on Frontier Group Holdings when looking at simple sales multiples. The stock trades on a P/S of 0.4x, which is cheaper than both the global airlines average and its peer group at 0.5x. It also sits in line with the 0.4x fair ratio our model suggests the market could move toward. That points to limited multiple upside and shifts the focus back to whether the underlying business can earn into this price or if the risk sits in the earnings delivery instead of the headline valuation.
For a closer look at how this sales-based view stacks up against detailed valuation work and where that fair ratio might leave room for surprise, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in Frontier Group Holdings can be exactly where opportunity or risk hides, so move quickly and consider both sides of the story by checking the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Frontier Group Holdings?
If Frontier Group Holdings has your attention, do not stop there. Broaden your opportunity set with focused screeners that surface shares matching different risk and return preferences.
- Target strong value and quality combinations by scanning a curated set of 33 high quality undervalued stocks that pair supportive fundamentals with appealing pricing.
- Prioritise resilience by filtering for companies on a list of solid balance sheet and fundamentals (25 results) so you can focus on businesses with sturdier financial foundations.
- Spot potential early movers by reviewing 19 high quality undiscovered gems before they land on every other investor's radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com