


Shenzhen International Holdings (SEHK:152) just reported nine month 2026 results that show revenue falling year-on-year, while net income and earnings per share moved higher. This shift in profitability helps explain recent share price moves.
At a latest share price of HK$4.685, Shenzhen International Holdings has seen its 30 day share price return fall 9.9%, and the year to date share price return decline 45.6%, while the 1 year total shareholder return is down 41.1%. This points to momentum that has weakened despite the recent earnings improvement and the boardroom appointment of Ji Lei, which may potentially signal shifting priorities around capital allocation and risk.
Scan beyond Shenzhen International Holdings and review a curated set of infrastructure and logistics plays with resilient balance sheets using the list of solid balance sheet and fundamentals (195 results) for comparison.
The share price reset and the fresh profit profile pull in different directions. Given the gap between HK$4.685 and current fair value estimates, where does a reasonable valuation for Shenzhen International Holdings actually land now?
Price-to-Earnings of 4.9x: Is it justified?
On simple valuation math, Shenzhen International Holdings trades on a P/E of 4.9x, while also sitting well below some cash flow based fair value estimates such as HK$8.79 from the SWS DCF model, compared with the last close at HK$4.685.
The P/E ratio links the current share price to earnings per share, so a lower figure often signals either discounted expectations or concerns about the durability of profit. For a business like Shenzhen International Holdings that spans toll roads, logistics hubs and environmental projects, investors often watch this metric closely because earnings quality and cyclicality can differ from pure growth sectors.
Here, the 4.9x P/E is far below the Asian infrastructure industry average of 13.3x and also below the estimated fair P/E of 11.4x. Our fair ratio work suggests the market could move towards that level over time if sentiment and fundamentals align more closely.
Explore the SWS fair ratio for Shenzhen International Holdings.
Result: Price-to-Earnings of 4.9x (UNDERVALUED)
Still, Shenzhen International Holdings faces clear risks, including execution missteps across toll roads and logistics projects, as well as potential setbacks in environmental and wind power operations.
Find out about the key risks to this Shenzhen International Holdings narrative.
Another View: Cash Flow Says HK$8.79
The P/E story presents Shenzhen International Holdings as inexpensive, while the SWS DCF model estimates a cash flow-based value of HK$8.79 per share. This is almost double the HK$4.685 market price and is flagged as undervalued. If both earnings and cash flows point in the same direction, what is the market still concerned about?
Look into how the SWS DCF model arrives at its fair value.
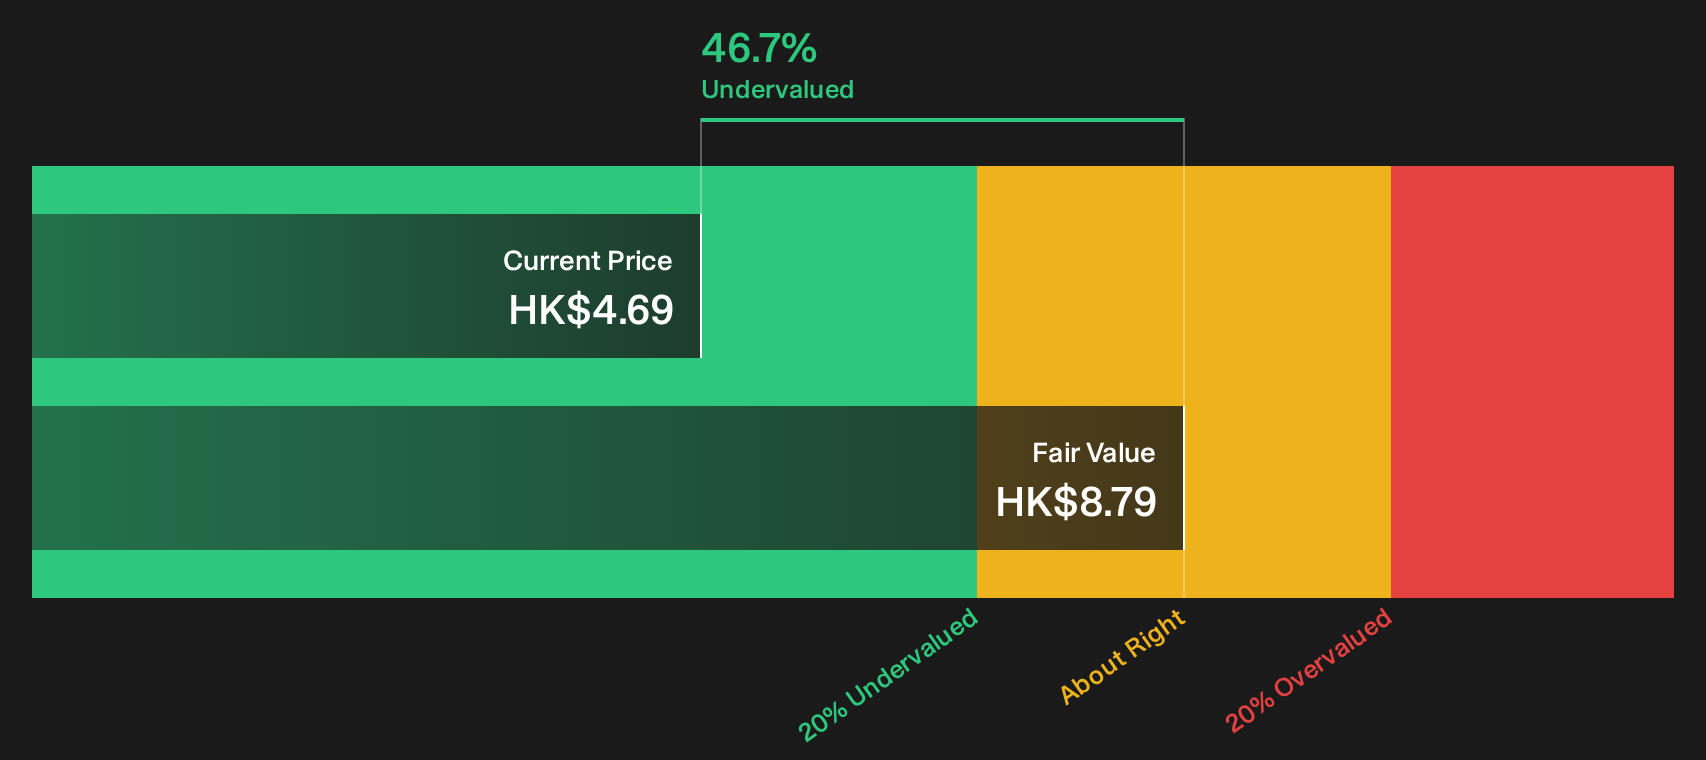
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shenzhen International Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 198 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Shenzhen International Holdings can feel confusing, so consider reviewing the situation while the numbers and news are fresh and pressure test the story yourself using the 4 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Shenzhen International Holdings?
If Shenzhen International Holdings has sharpened your focus on value and risk, you can use this moment to widen your opportunity set while the thesis is still fresh.
- Target reliable income streams by reviewing companies screened as potential dividend fortresses through the 217 dividend fortresses.
- Look for potentially mispriced quality by scanning a curated pool of possible bargains using the 198 high quality undervalued stocks.
- Prioritise capital preservation by filtering for resilient businesses via the 204 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com