


- A recent industry study projects the global vehicle recycling market to reach about US$229.6b by 2032, with Copart identified as a key participant alongside other major recyclers.
- The report highlights that rising end-of-life vehicle volumes and tighter environmental rules are pushing more formal recycling. This trend directly aligns with Copart’s storage, auction and dismantling infrastructure.
- The following section examines how Copart’s investment narrative interacts with the growing vehicle recycling market and its emphasis on regulated recovery.
Scan beyond Copart and see how other recyclers are positioned in this shift to regulated recovery with the curated list of list of solid balance sheet and fundamentals (25 results).
Copart Investment Narrative Recap
To own Copart, you need to be comfortable with a business that looks more like critical infrastructure for end of life vehicles than a simple auction website. The key belief is that its yard footprint, insurance relationships and title processing know how remain hard to replicate. The recent recycling market study mostly reinforces that context rather than changing the near term story.
The near term swing factor still sits in execution across a mature US operation and a growing international arm, as WealthAP, an investor in the Simply Wall St Community, argues. The biggest risk remains that slower headline growth could turn Copart into a steady but unexciting cash generator rather than a compounder the market once priced in.
There have been no fresh company announcements tied directly to this recycling report. As a result, the more interesting reference point is the earlier discussion of Jay Adair’s return as CEO and Jane Pocock’s promotion to President. That leadership mix places experienced hands over a network that now sits squarely in the spotlight of regulated vehicle recovery.
WealthAP frames the catalyst as proof that Copart can replicate its profitable US model abroad without eroding margins or overpaying for growth. In that light, the recycling market study simply raises the stakes on execution. It highlights a growing pool of end of life vehicles and tighter rules, while Copart still has to show that its global footprint and conservative balance sheet convert that backdrop into resilient auction volumes and disciplined capital allocation.
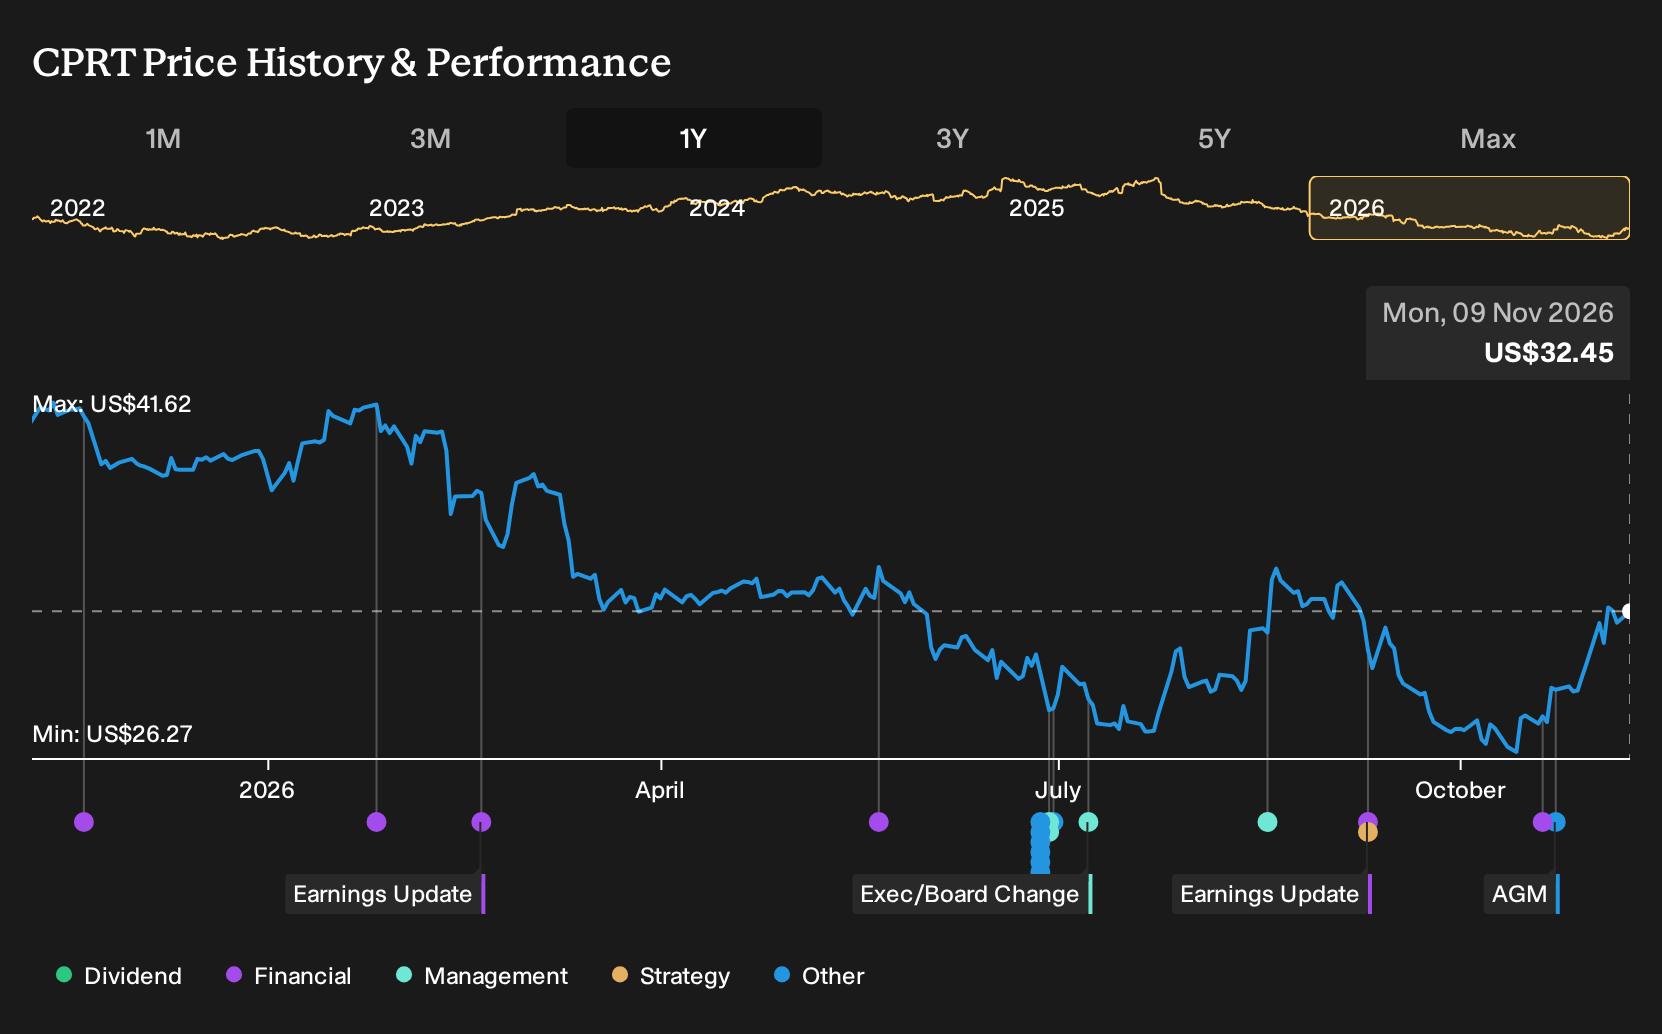
WealthAP’s own fair value of US$49.00 for Copart comes from assuming revenue growth of 15.0% a year and a future profit margin of 33.5%. Together, these assumptions imply a business that still compounds earnings at a healthy clip, even if the share price currently reflects fatigue rather than failure.
Discover why Copart's fair value suggests a 51% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate angle on Copart focuses on the recycling potential. The most bullish analysts were already estimating revenue of about US$6.9b and earnings of US$2.1b by 2029, along with a higher P/E and ongoing buybacks. Those forecasts came before this recycling study, so views on Copart could easily change from here.
Explore 8 other Copart fair value estimates, including one that suggests potential upside of up to 108% from the current price.
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Copart research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Copart. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Copart's overall financial health at a glance.
Looking For More Investment Ideas Beyond Copart?
Once you have a view on Copart, it can help to compare it with other opportunities that share similar qualities or offer a different balance of risk and reward. The Simply Wall St Screener gives you curated sets of stocks that fit clear filters, so you can quickly build a watchlist tailored to how you like to invest.
- If you care most about quality at a reasonable entry price, start with our hand picked group of 33 high quality undervalued stocks that combine fundamentals with attractive valuations.
- If resilience matters more than excitement, focus on companies that score well on stability and downside protection through our curated set of 30 resilient stocks with low risk scores.
- If you want to get ahead of the crowd, look at under-the-radar businesses with strong underlying numbers using our collection of 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com