


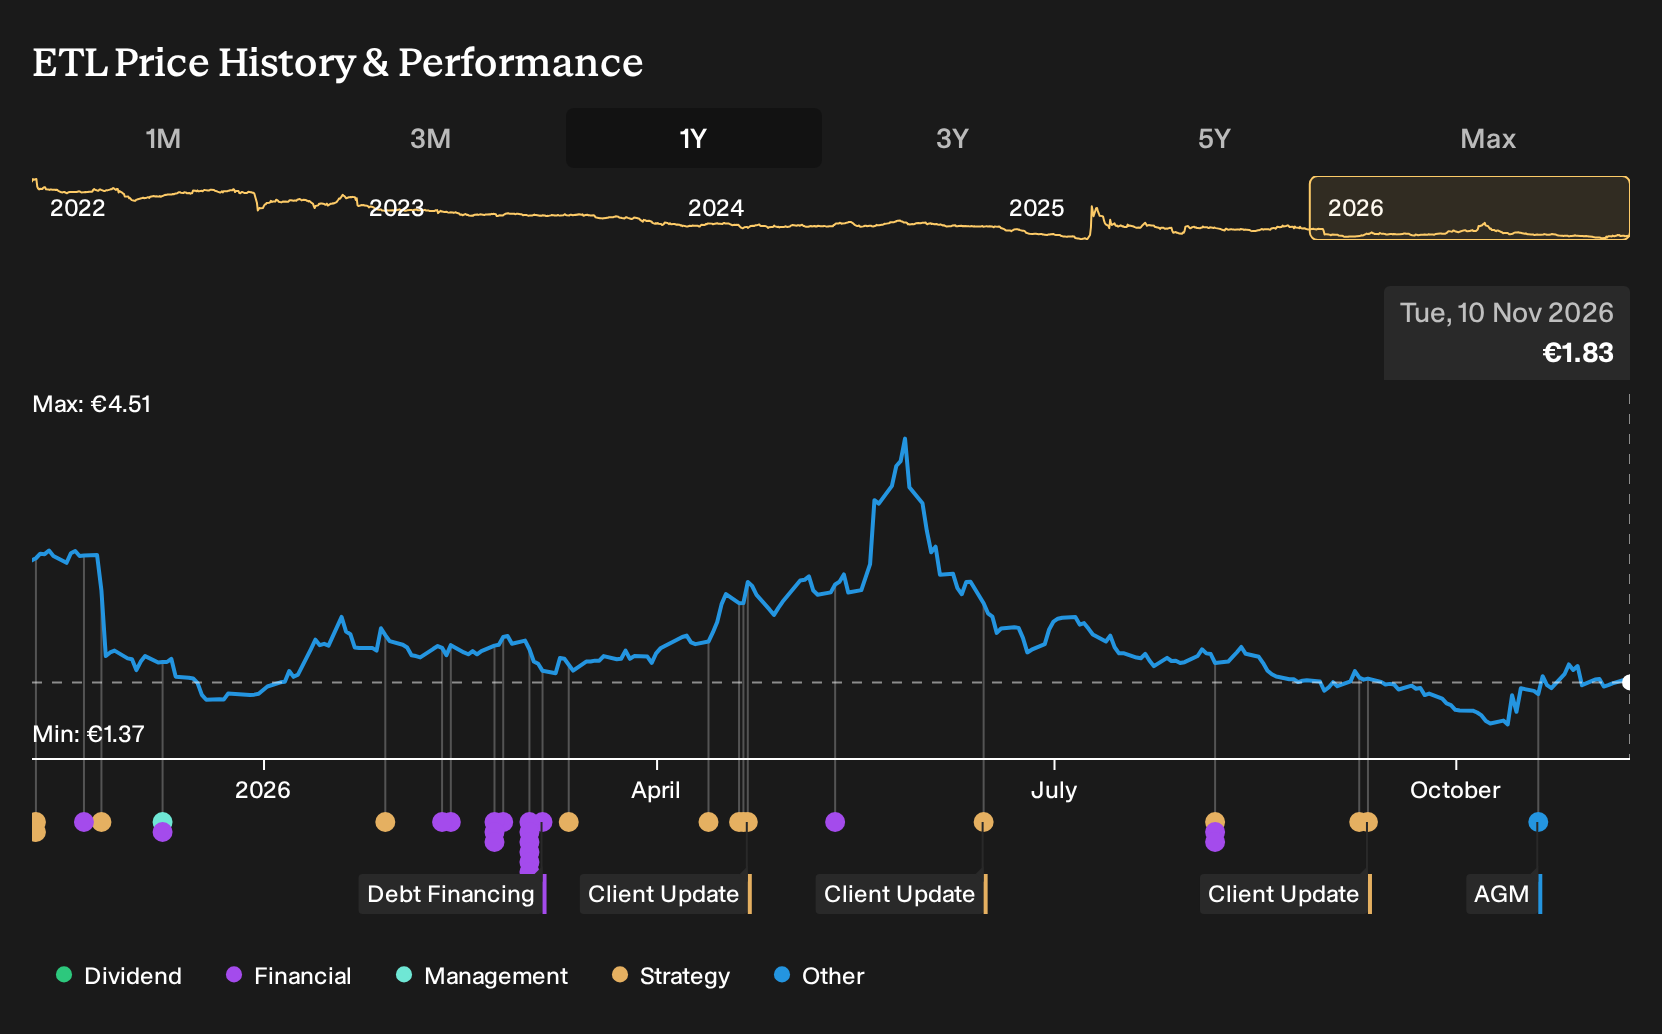
Headline wins did not help Eutelsat Communications holders. Investors who held Eutelsat Communications over the past year are down 27.6%, including dividends. That drop came even as the group reported higher revenue in H2 2026 and secured a central role in Europe’s IRIS² programme. If you were weighing a purchase back on 2025-11-10, what early clues were on record that profits and margins might still move the wrong way?
The easy part of this move is behind Eutelsat Communications. Zero in on 198 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Choose Between On Eutelsat Communications
The shares cost €3.19 at the start of the period, and Eutelsat Communications sat between two very different stories about where the business might go next.
On the optimistic side, the SpaceRISE and IRIS² bullish narrative pointed to a Fair Value of €3.39. This price was implied by assumptions such as 2.7% annual revenue growth and profit margins reaching 6.7% as low Earth orbit projects scaled.
The more cautious August 2025 bear case anchored on a Fair Value of €1.2. This scenario was built on slower 1.1% revenue growth and concern that rising terrestrial and LEO competition would keep pressure on pricing and cash generation.
What The Results Changed For The Eutelsat Communications Story
Eutelsat Communications confirmed higher H2 2026 revenue of €644.3 million and an €8.9 billion IRIS² backlog, which backed the bullish focus on LEO and sovereign projects. The same half brought a deeper net loss of €220.8 million and a net margin that slipped further to -34.3%, so the hoped for profitability shift remained unproven. Overall, the evidence cut both ways.
The lesson is simple. When a thesis rests on margin repair, track net income and the reported net margin line by line, even when headline contract wins look strong.
What You Are Really Paying For In Eutelsat Communications Today
Today Eutelsat Communications trades at €1.83, while the bullish analyst Narrative on Simply Wall St sees Fair Value above that quote based on its own assumptions about LEO, sovereign and hosted payload cash flows.
The key bet a buyer tests is that heavy LEO and IRIS² CapEx still leads to healthier margins and balance sheet resilience over time.
"The current valuation implies the market discounts Eutelsat’s LEO growth, government contracts such as the up to €350m NEXUS framework, and emerging hosted payload revenues, so the share price embeds limited credit for these cash flow sources."
That disagreement has a full argument behind it. → Uncover the higher Fair Value this Narrative argues for
How Could You Get There Earlier?
This company's disappointment is already part of the story. Your next idea could come from looking where the price and the possibilities still seem far apart. Here are three companies priced below our estimates.
- Company 1 - 41% below our estimate - converts subsea opportunity lists into higher margin projects and long duration services contracts.
- Company 2 - 26% below our estimate - offers a large gold reserve base that supports long mine lives and ongoing conversion drilling.
- Company 3 - 38% below our estimate - handles high complexity freight and customs work as AI related cargo volumes reshape air demand.
Three companies from the same screener. Open all 195 companies with the balance sheet to back it up →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com