


AI lab Anthropic is racing toward a potential US$1t plus valuation, and its founders are keeping tight voting control. That mix of rapid technology change and deeply invested leadership is exactly what many Australian investors now look for. This article walks through why founder led businesses can matter for your portfolio and highlights three Australian stocks where founders still have serious skin in the game.
The three stocks highlighted here offer a compelling starting point if you want exposure to founder led businesses where leadership is closely tied to long term outcomes. However, if you want the names that matter most, these 7 top founder-led companies are the strongest companies we've found.
Flight Centre Travel Group (ASX:FLT)
Overview: Flight Centre Travel Group runs founder led Flight Centre and Corporate Traveller brands alongside a wide mix of leisure, corporate and destination travel services across global markets.
Operations: Flight Centre Travel Group generates about A$1.4b from Leisure, A$1.2b from Corporate and A$0.2b from Global HQ across Australia, New Zealand, the Americas, EMEA and Asia.
Market Cap: A$2.5b
Flight Centre Travel Group shows what the founder led theme looks like in the real world, with long serving leaders still closely involved. At the same time, the bearish analyst Narrative on Simply Wall St stresses the pressure that business mix can put on returns.
"Although Flight Centre is reallocating capital toward cruise, luxury, Meetings & Events and foreign exchange, the recent guidance cut linked to a mix shift toward lower margin carriers highlights a risk that product mix and supplier choice continue to dilute yield, which can cap revenue per transaction and keep operating margins under pressure."
This raises the question of what happens if one quiet shift in how Flight Centre Travel Group earns each travel dollar lands either firmly in its favour or against it.
If that mix shift is what really moves the dial, the full narrative for Flight Centre Travel Group maps how founder control, product economics and capital allocation could still accelerate value.

Pro Medicus (ASX:PME)
Overview: Pro Medicus provides founder led medical imaging software that helps hospitals and radiology groups manage, view and interpret complex diagnostic scans.
Operations: Pro Medicus generates about A$261.7 million from healthcare software, with revenue concentrated in Australia and North America, supported by European clients.
Market Cap: A$21.5b
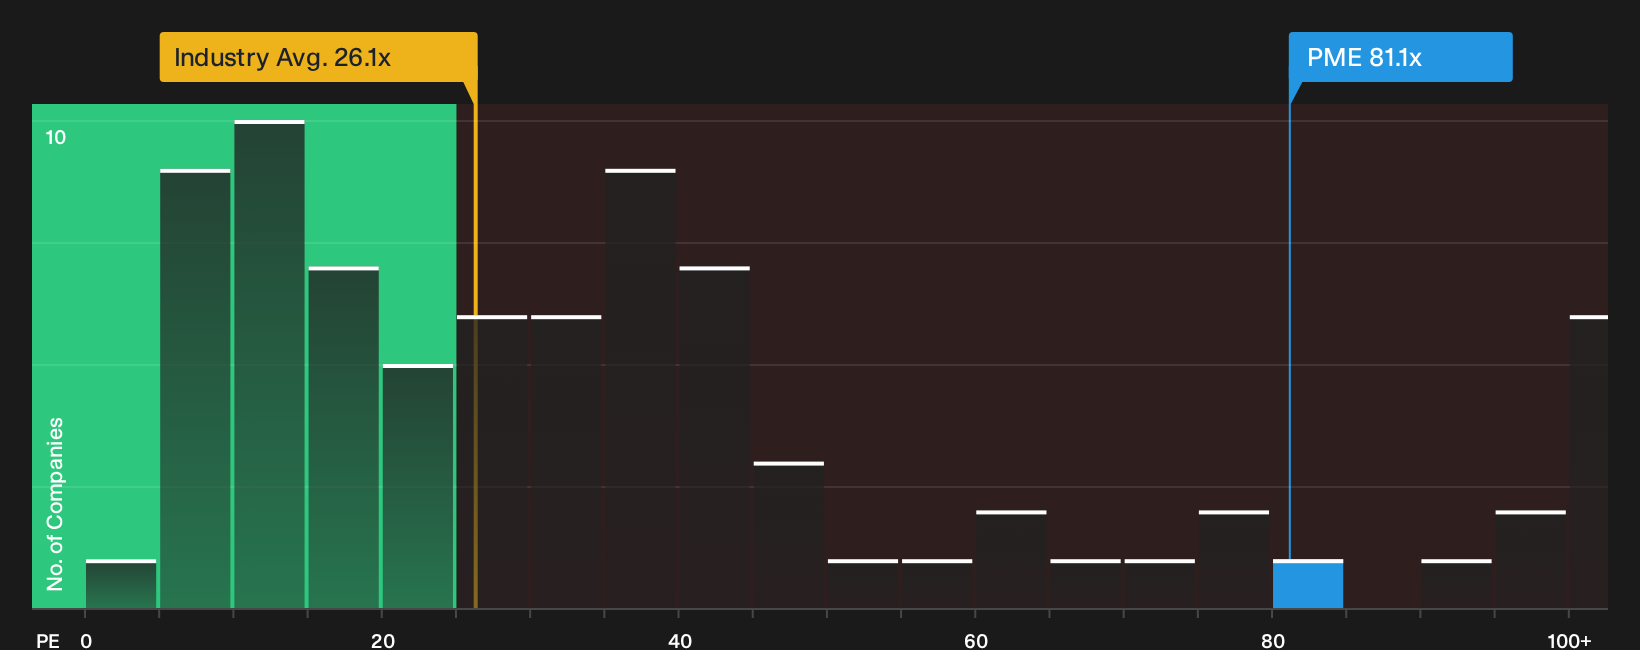
Pro Medicus fits this founder led screen because Dr. Sam Hupert still runs the business he co created. This links Visage 7 and Visage RIS/PACS directly to long term owner leadership that focuses on software quality, customer stickiness and contract depth, according to ZayaanS, an investor in the Simply Wall St Community who wrote a detailed Narrative on the stock.
"Radiologists at top US hospitals have started demanding it as a condition of employment, they simply won't join institutions that don't run Visage, the company's flagship imaging platform."
The real test for Pro Medicus will be how one quiet shift in customer buying power shapes future pricing strength and contract economics.
That power balance is exactly what the full narrative for Pro Medicus unpacks for Pro Medicus, including where pricing strength could be accelerating faster than headline contracts suggest.
Mesoblast (ASX:MSB)
Overview: Mesoblast develops founder led regenerative medicine therapies using mesenchymal lineage cells to address severe inflammatory, cardiac and musculoskeletal diseases.
Operations: Mesoblast generates about $120 million from developing and commercializing its allogeneic cellular medicines platform focused on mesenchymal lineage therapies.
Market Cap: A$2.7b
Mesoblast fits the founder led theme because the business still follows a co founder driven roadmap for its Ryoncil and MPC programs. The bullish analyst Narrative on Simply Wall St argues that this long term mindset is starting to show up in how capital, manufacturing and clinical priorities are being set.
"The planned “Generation 2” manufacturing process that adds a proprietary recombinant growth-factor supplement, together with automation and US onshoring of production, points to a step change in cell yields and cost of goods. This could widen gross margins as higher volume indications come through."
What really matters now is how one quiet shift in how each new Ryoncil procedure flows through the cost base ends up shaping earnings power.
That earnings power question sits at the center of the full narrative for Mesoblast, which tracks how Mesoblast's founder-led roadmap could turn manufacturing shifts into accelerating economic outcomes.

Seeking Fresh Alternatives Beyond These Founders?
Fresh ideas move first. By the time every fund manager is talking about a sector, the easy breakout momentum can be gone. Scan these under the radar lists while it matters and aim to position early.
- Look for cash generative bargain opportunities before they get fully priced by institutions and run your filters across the 2 high quality undervalued stocks while they are still under the radar for now.
- Focus on structural demand for uranium, enrichment and reactor build outs by concentrating on infrastructure players inside the 17 nuclear energy infrastructure stocks before additional capital enters the space.
- Explore recurring royalty streams and potential production upside by scanning the 34 elite gold producer stocks where producers with stronger balance sheets may attract attention if bullion momentum continues.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com