


Why Swiss Re’s fresh guidance and Q3 numbers matter now
Swiss Re (SWX:SREN) put fresh numbers on the table with new 2026 earnings guidance of US$4.5b in expected group net income, alongside third quarter results that pulled investor focus back to the stock.
Against that backdrop, Swiss Re’s 1-month share price return of 4.76% and 90-day gain of 9.95% point to building momentum around the current CHF150.85 level, while a 5-year total shareholder return of 125.19% shows how longer term holders have already seen substantial value created.
Fresh 2026 earnings guidance, mixed Q3 net income trends and the appointment of Lori Goltermann as chief commercial officer for Corporate Solutions have all landed within days of each other. This gives investors new reasons to reassess both recent price strength and the longer term total return profile.
Scan Swiss Re alongside handpicked insurers with similar earnings momentum and capital strength through our 204 resilient stocks with low risk scores.
Recent gains and fresh guidance suggest a stronger Swiss Re, while the softer Q3 net income muddies the picture. Is this move mainly about improving fundamentals, or a reset in investor sentiment as valuation comes into focus?
Most Popular Narrative: 18% Overvalued
On the Simply Wall St analyst consensus Narrative, Swiss Re’s fair value sits at CHF127.98 against the last close of CHF150.85. This frames the current share price as richer than that implied estimate based on analyst forecasts that are discounted at 3.95%.
The current valuation suggests the share price already reflects strong capital strength, high recent earnings and active buybacks despite pressure on new business margins and risk-adjusted P&C pricing, which sustains the view that Swiss Re may be overvalued.
See why 72 investors see Swiss Re as 18% overvalued.
Result: Fair Value of CHF127.98 (OVERVALUED)
Still, that overvaluation story can easily crack if real reinsurance pricing weakens further or if casualty pruning shuts Swiss Re out of profitable US liability demand.
Find out about the key risks to this Swiss Re narrative.
Another angle on Swiss Re’s valuation
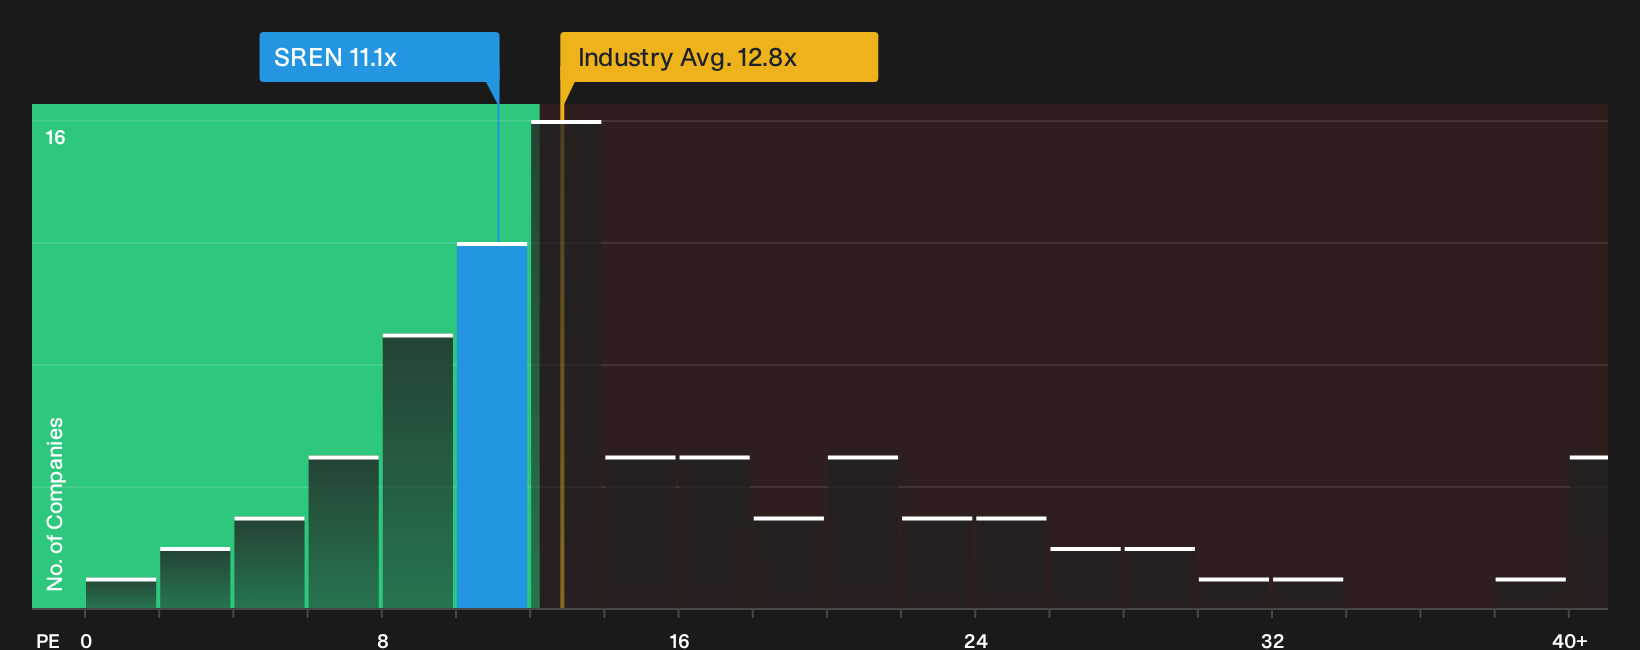
The analyst Narrative argues that Swiss Re looks 18% overvalued at CHF150.85 versus a CHF127.98 fair value. Yet on simple P/E, the picture flips. SREN trades at 11.1x earnings compared with a 19.5x fair ratio, 12.8x for the European insurance group and 30.8x for peers. That kind of discount can signal mispricing or reflect concerns the analyst model already captures. Which story do you think fits better with your own view of Swiss Re?
See what the numbers say about this price in our valuation breakdown, then weigh how it lines up with your return expectations See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Swiss Re can either tempt or worry you, so move quickly, test the data against your own thesis, and weigh both sides through the 2 key rewards and 2 important warning signs.
Looking for more ideas beyond Swiss Re?
If Swiss Re has you thinking harder about where your money works best, broaden your radar with a few focused idea lists built from real fundamentals.
- Target resilient balance sheets by scanning companies with robust finances and consistent fundamentals through our list of solid balance sheet and fundamentals (194 results).
- Hunt for quality at a potential discount by reviewing our curated pool of opportunities that screen as attractively priced using the 202 high quality undervalued stocks.
- Lock in potential portfolio income by checking companies that combine higher yields with staying power via our 216 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com