


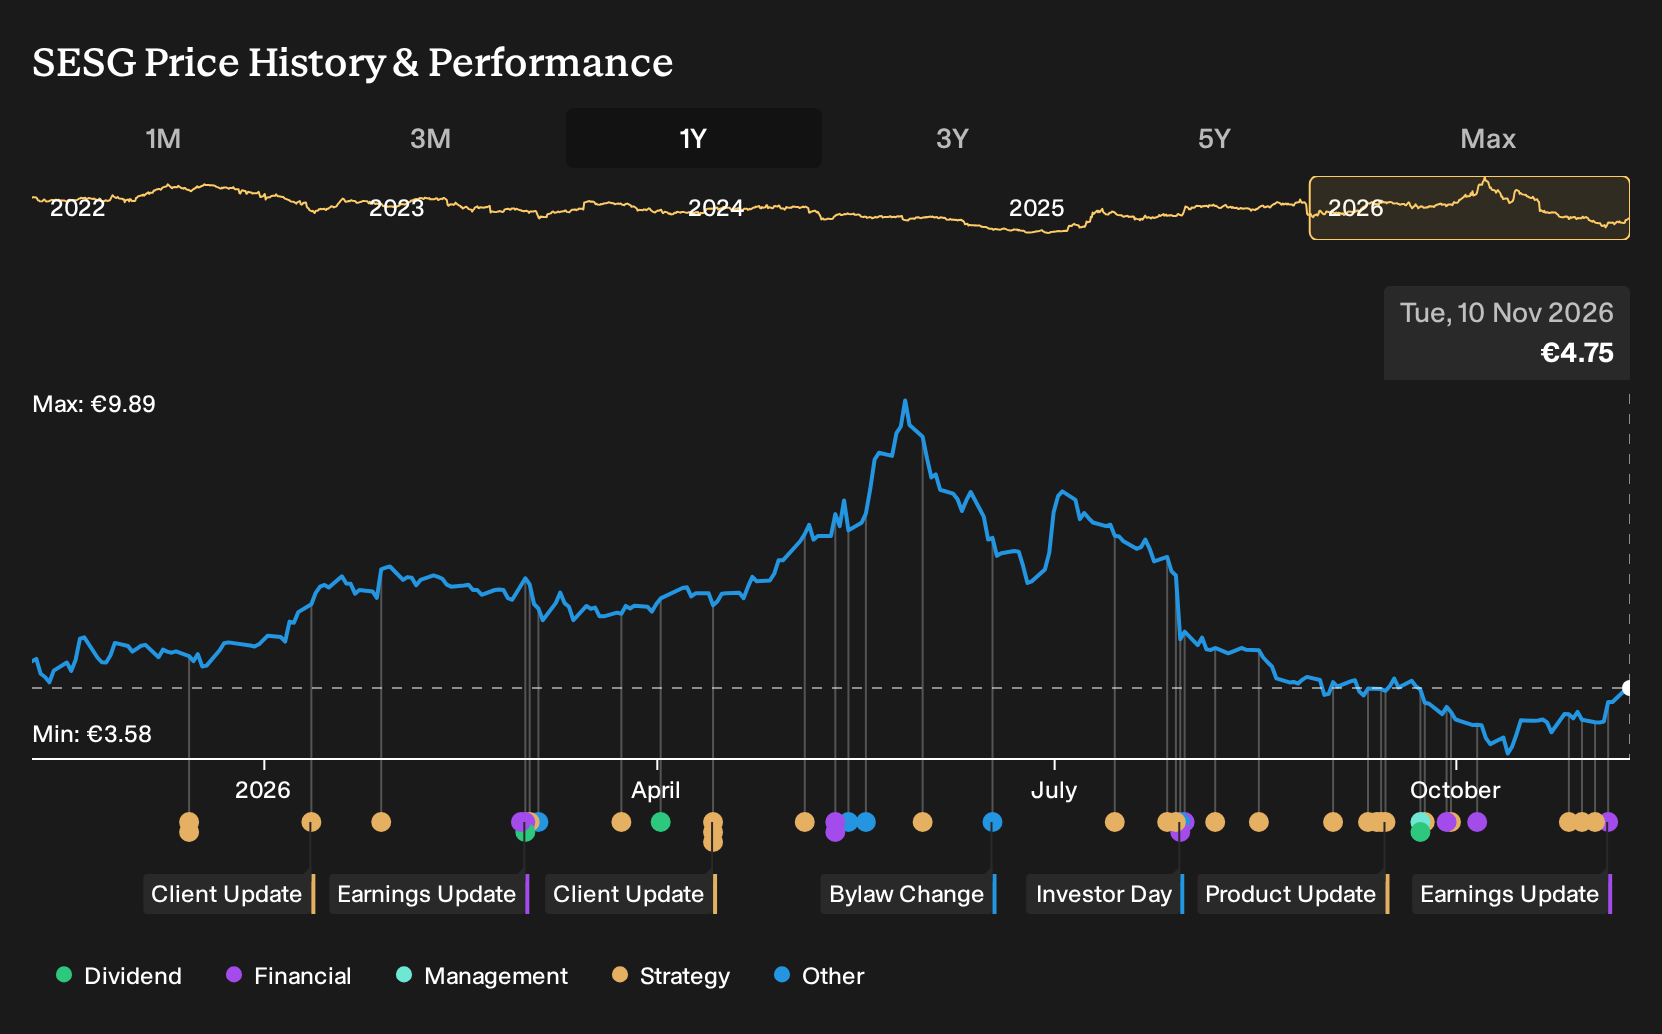
- SES reported third quarter 2026 sales of €765 million compared with €870 million a year earlier, with a net loss of €62 million, even as new inflight connectivity agreements with Finnair and Air Astana and a long term CANAL+ capacity extension were signed in recent weeks.
- The combination of weaker quarterly profitability and fresh multi orbit aviation and video distribution contracts highlights the tension between SES’s current earnings profile and its longer term connectivity commitments.
- This article now examines how SES’s return to quarterly net losses, together with new long dated connectivity deals, could influence the broader investment narrative.
Scan other satellite and connectivity stocks that pair long term contracts with challenged earnings profiles by running the curated 204 resilient stocks with low risk scores alongside SES in your watchlist.
SES Investment Narrative Recap
To own SES, you need to believe the multi orbit connectivity and government contracts described in the analyst consensus Narrative on Simply Wall St can eventually outweigh the drag from loss making quarters and heavy CapEx. The latest quarter showed sales of €765 million and a net loss of €62 million, which keeps the focus firmly on execution and capital discipline.
The most important short term catalyst is still progress on turning that growing contract backlog into profitable, cash generative services while managing debt and dividend pressure. The biggest current risk is that continued losses and high investment needs make deleveraging slower than expected, which this quarter’s numbers do little to ease.
The CANAL+ extension to 2040 looks particularly important in this context. It gives SES very long dated visibility in parts of the traditional video unit that analysts already viewed as a key supporting cash generator. That sort of duration can help underpin funding for projects like O3b mPOWER and IRIS2 when earnings are under strain.
For catalysts, this contract matters because it aligns with the idea that legacy Media can still carry meaningful cash flow even as like for like revenue faces structural pressure. Investors now have to weigh that long term video commitment against the fresh aviation wins and the recent quarterly loss to judge whether SES is stretching its balance sheet or simply pre investing for future usage.
SES' narrative projects €3.4b revenue and €81.6 million earnings by 2029. This implies 5.1% yearly revenue growth and an earnings increase of about €232.6 million from current earnings of a €151.0 million loss.
Uncover why SES' fair value indicates that its current price may have a 74% potential upside that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses on Media pressure rather than new aviation wins. In that version of the SES story, longer TV deals might not fully steady cash generation. The most cautious analysts were assuming revenue would slip about 1.3% a year and pencilled in around €3.1b revenue by 2029 before this news. That is a far more skeptical script than the consensus, so treat today’s CANAL+ and airline connectivity updates as fresh information that could shift those expectations.
Explore 2 other SES fair value estimates, including one that suggests it could be worth just €7.52!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your SES research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for SES. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SES' overall financial health at a glance.
Looking For More Investment Ideas Beyond SES?
If SES has sharpened your focus on contract quality, balance sheets and earnings resilience, it can be useful to compare it with other businesses that share some of those traits but sit in very different corners of the market. The Simply Wall St Screener is one way to quickly surface candidates that match the kind of risk and return profile you want to research next.
- For investors hunting for smaller companies with room to scale, start with 122 elite penny stocks with strong financials that already show stronger financial underpinnings than the typical micro cap.
- If capital preservation sits high on your checklist, balance out exposure to SES by researching a list of solid balance sheet and fundamentals (194 results) that can help you stress test your portfolio under tougher conditions.
- When you want upside potential backed by fundamentals rather than hype, look through a 568 high quality undiscovered gems that may not yet be widely followed but already pass key quality filters.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com