


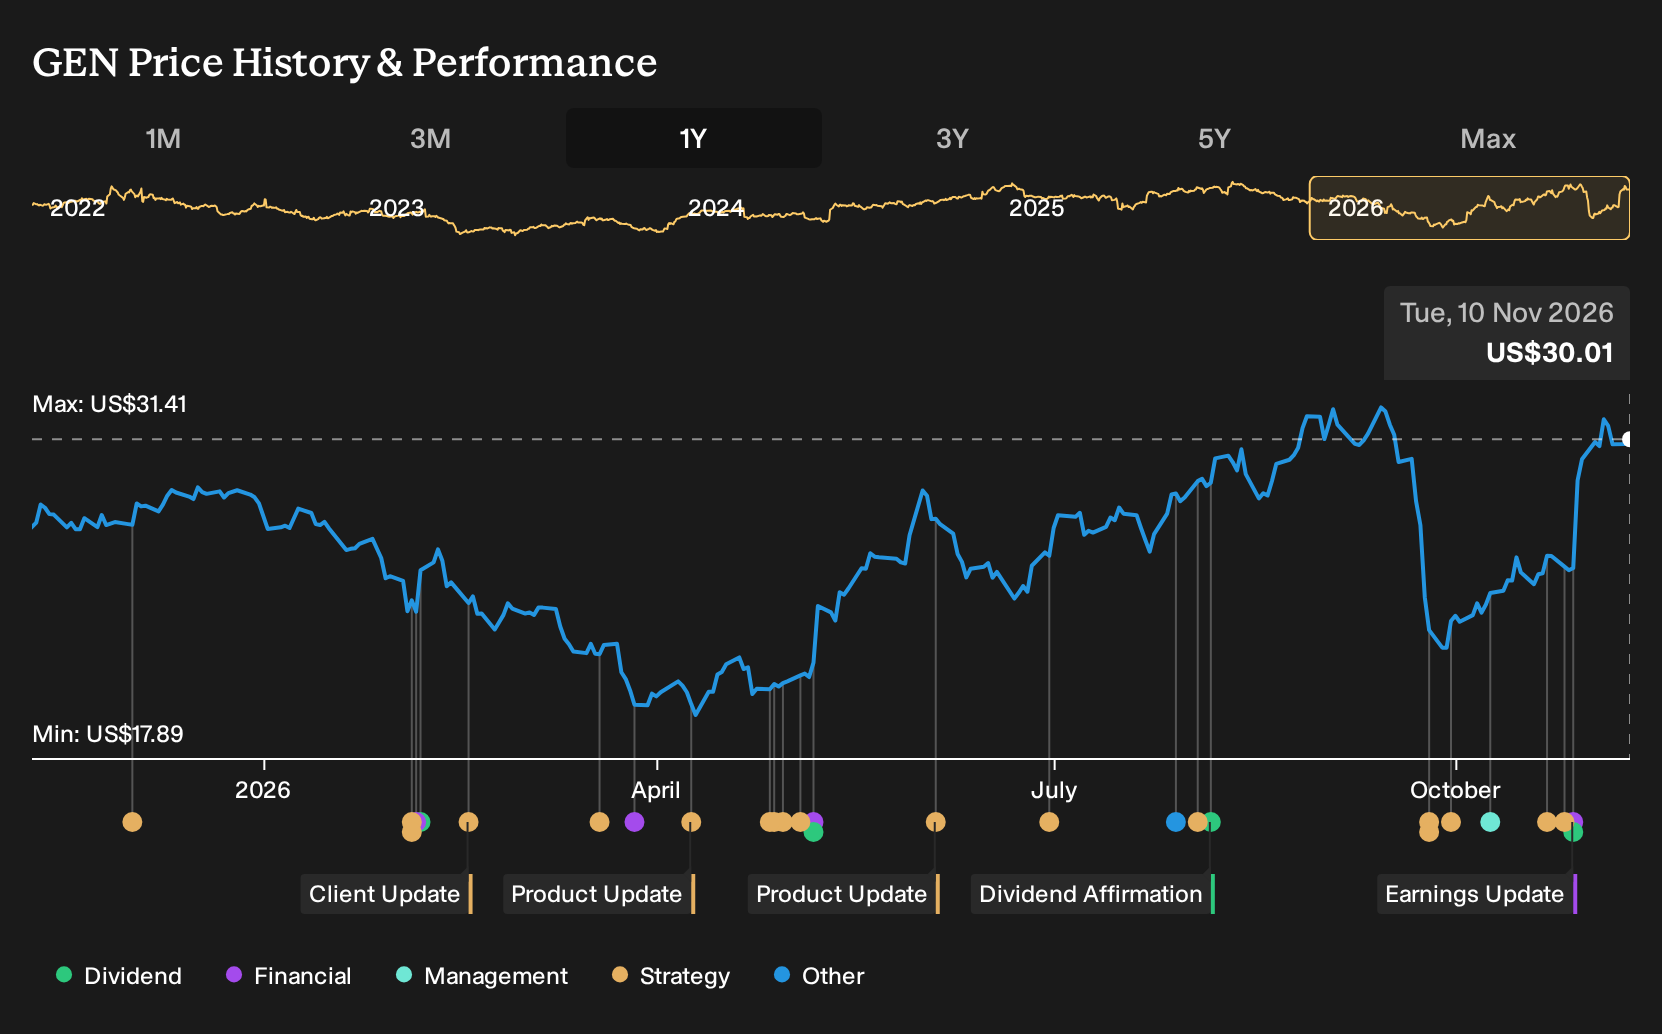
- Gen Digital reported quarterly sales of US$1,369 million and net income of US$287 million for the second quarter ended October 2, 2026, alongside an affirmed quarterly dividend of US$0.125 per share.
- The combination of higher earnings per share from continuing operations and a maintained cash dividend indicates that Gen Digital is balancing profit levels with ongoing capital returns to shareholders.
- We will now see how Gen Digital's investment narrative could be influenced by this reported change in quarterly net income.
Gen Digital Investment Narrative Recap
To own Gen Digital, you need to believe its cyber safety and financial wellness platform can keep attracting users into higher tier memberships, while holding pricing power in a crowded security market. The latest quarter showed higher sales and net income alongside stronger earnings per share, which reinforces that the current operating model is working off today’s cost base.
The near term swing factor is execution on membership bundling and partner channels described in the analyst consensus Narrative on Simply Wall St. The main risk still sits around security incidents or a large GoDaddy style deal that could strain a balance sheet that already carries about US$8b of net debt, and this earnings release does not materially change that.
The regular quarterly dividend of US$0.125 per share is the announcement that ties most directly to this update. Management is pairing higher basic and diluted EPS from continuing operations with a steady cash return, which signals confidence in current cash generation, even with an unstable dividend track record flagged in the risk summary.
For you as a shareholder, that payout interacts with catalysts like expanding membership penetration and partner revenue, because sustained distributions depend on subscription resilience and efficient use of AI in the business. It also sits alongside risks such as high debt and any potential GoDaddy acquisition, which could influence how much financial flexibility Gen Digital has for buybacks or future dividends.
Gen Digital's current earnings are about US$1.1b, and analysts collectively see that figure reaching roughly US$1.3b by 2029. This implies an earnings increase of about US$0.2b alongside forecast revenues of US$6.0b in that same year, supported by an assumed 5.8% yearly rise in sales.
Uncover why Gen Digital's fair value indicates a 6% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle focuses on GoDaddy deal risk. The most pessimistic Gen Digital analysts were already baking in slower expansion, with revenue growth at 4.1% a year and earnings near US$1.3b by 2029 from about US$1.2b. After this earnings and dividend update, those pre news assumptions may be revisited, so explore both narratives before deciding what matters most to you.
Explore 5 other Gen Digital fair value estimates, including one that suggests as much as 17% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Gen Digital research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Gen Digital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Gen Digital's overall financial health at a glance.
Looking for more investment ideas beyond Gen Digital?
Once you understand where Gen Digital fits in your portfolio, it can help to compare it with other opportunities that share similar earnings power, balance sheet strength, or risk profile. The Simply Wall St Screener lets you filter the market quickly so you can focus on companies that match the kind of story you want to own.
- If you want potential upside with more cushion on the downside, start with sturdier balance sheets and filter for companies on our 30 resilient stocks with low risk scores.
- For investors hunting for mispriced quality, compare Gen Digital with peers that combine fundamentals with appealing valuation using the 37 high quality undervalued stocks.
- To widen your watchlist with under-the-radar opportunities, scan through companies that have strong metrics but less attention using the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com